Loan Programs Available


Blogs
The Top 5 Mortgage Mistakes to Avoid
Buying your first home can be both exciting and nerve-wracking at the same time. With so many things to consider and....
Mortgage Do and
Do not list
Mortgages can be tricky, and it's easy to make mistakes that can end up costing you dearly. That's why we've put together this list....
Tips On How To Improve Your Credit Score
Let's talk about some ways you can improve your credit score! Your credit score is actually a big deal, and it can affect...
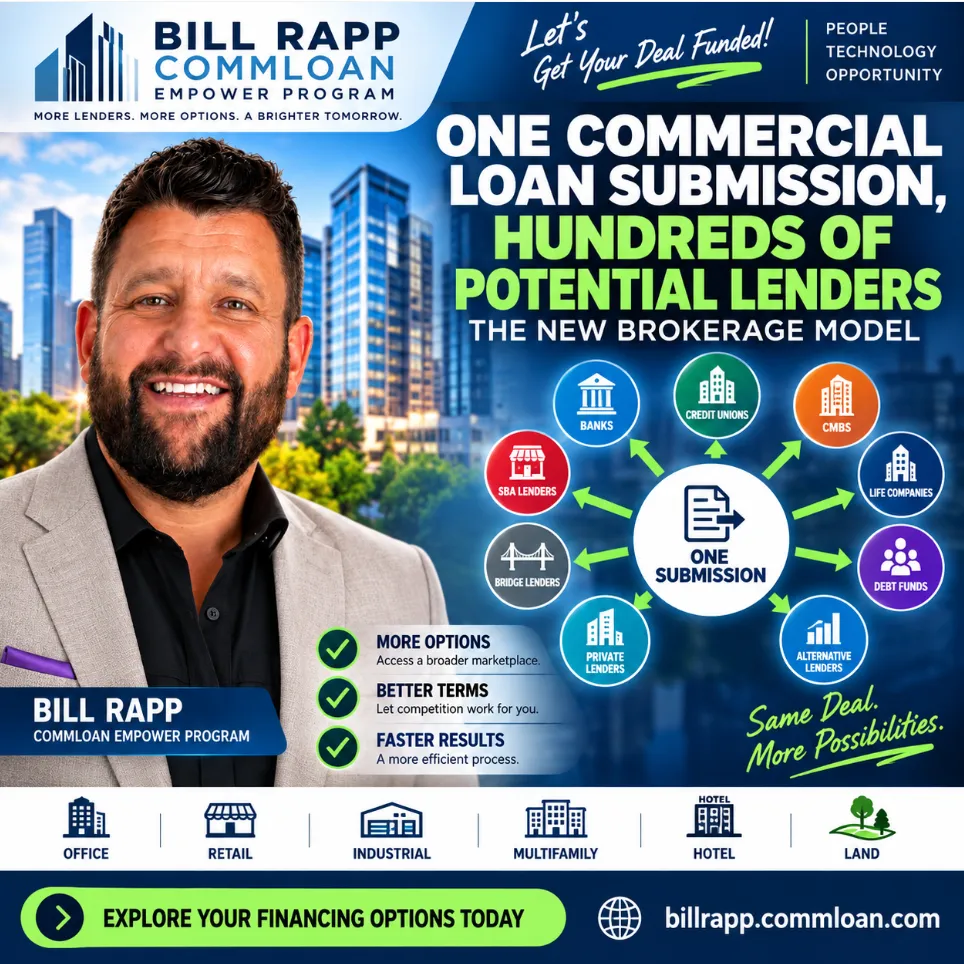
🚀 One Commercial Loan Submission, Hundreds of Potential Lenders: The New CRE Financing Model 🏢
🚀 One Commercial Loan Submission, Hundreds of Potential Lenders: The New CRE Financing Model 🏢
💻 Commercial Real Estate Financing Is Changing: How Technology Connects One Deal to Hundreds of Lenders 💰
One Commercial Loan Submission, Hundreds of Potential Lenders: The New Brokerage Model
Commercial real estate financing has traditionally been a relationship-driven business.
An investor or business owner needed financing, contacted a bank, submitted financial information, waited for the lender to review the transaction and hoped the deal fit that institution's lending criteria.
If the answer was no—or the proposed structure wasn't competitive—the borrower might start the process again with another lender.
Technology is changing that model.
Today's commercial mortgage broker can combine capital markets expertise, technology and a broad lender marketplace to help borrowers evaluate financing opportunities across multiple sources of capital.
Instead of starting with the question, "Which bank should I call?", the better question may be:
"Which capital source is the best fit for this particular transaction?"
That distinction can fundamentally change how investors and business owners approach commercial real estate financing.
The Problem With the Traditional One-Lender Approach
Commercial real estate loans are not commodities.
Two lenders can evaluate the exact same property and reach very different conclusions regarding:
·Loan amount
·Interest rate
·Amortization
·Loan term
·Recourse
·Prepayment structure
·Debt service coverage requirements
·Loan-to-value limits
·Property eligibility
·Borrower requirements
That happens because lenders have different balance sheets, credit policies, concentration limits, geographic preferences and risk tolerances.
A bank may like multifamily but have limited appetite for hospitality.
A credit union may aggressively pursue owner-occupied commercial real estate while another lender prefers stabilized investment properties.
A bridge lender may consider a transitional property that conventional lenders will not finance.
A CMBS lender may be competitive on a stabilized investment transaction but have an entirely different structure than a community bank.
The challenge isn't simply finding a lender.
It's identifying the lenders whose capital programs align with the specific transaction.
The Commercial Mortgage Broker Is Becoming a Capital Marketplace
This is where technology can create significant value.
The modern commercial mortgage brokerage model combines the expertise of a capital advisor with technology designed to efficiently evaluate a transaction against a much larger universe of potential lending sources.
At CommLoan, technology helps support access to a broad marketplace of potential commercial real estate lenders.
Depending on the transaction, potential capital sources can include:
·Banks
·Credit unions
·CMBS lenders
·Agency lenders
·SBA lenders
·Life insurance companies
·Debt funds
·Bridge lenders
·Private lenders
·Alternative financing sources
Instead of assuming one institution has the right solution, the objective is to identify financing structures that align with the property's economics and the borrower's objectives.
One Commercial Loan Submission Can Create a More Efficient Process
Think about the traditional process.
You approach Lender A.
You submit documents.
You wait.
The lender decides the property doesn't meet its requirements.
Then you approach Lender B and potentially repeat much of the same process.
A technology-enabled commercial loan marketplace is designed to make lender discovery more efficient.
The transaction can be organized around the information lenders actually need to evaluate the opportunity:
Property → Borrower → Cash Flow → Loan Request → Business Plan → Exit Strategy
From there, the transaction can be evaluated against potential capital sources whose lending parameters may align with the deal.
That doesn't mean every loan goes to hundreds of lenders.
It means technology can help identify appropriate potential matches from a much broader lending marketplace rather than restricting the search to the handful of institutions a borrower happens to know.
Why More Lender Options Matter
Access to a larger lending marketplace isn't valuable simply because the number is bigger.
The real benefit is optionality.
Imagine an investor refinancing a $3 million commercial property.
One lender might offer:
65% LTV with a 20-year amortization.
Another might consider:
70% LTV with a 25-year amortization.
Another might provide a lower rate but include a more restrictive prepayment structure.
Yet another lender may offer greater proceeds at a higher interest rate.
Which is best?
That depends on the borrower's objectives.
If the investor expects to sell the property in three years, prepayment flexibility may matter significantly.
If the investor's priority is maximizing cash flow, amortization and debt service may carry greater weight.
If the borrower needs cash-out proceeds, leverage may become the primary consideration.
The objective is not necessarily finding the lowest advertised interest rate.
It's finding the capital structure that fits the business plan.
Technology Doesn't Replace the Commercial Mortgage Broker
This is an important distinction.
Technology can improve lender discovery, data organization and efficiency.
But commercial real estate financing still requires judgment.
A financing platform doesn't change the underlying economics of a transaction.
Someone still needs to understand:
·Net operating income
·Debt service coverage ratio
·Loan-to-value ratio
·Debt yield
·Lease rollover
·Tenant concentration
·Property condition
·Sponsor liquidity
·Borrower experience
·Market conditions
·Exit strategy
The strongest model combines technology with human capital markets expertise.
Technology helps expand and organize the search.
The commercial mortgage broker helps structure, position and communicate the transaction.
Different Deals Require Different Capital
Consider several examples.
Owner-Occupied Commercial Real Estate
A business purchasing its own warehouse, office or retail property may potentially consider conventional bank financing, credit unions or SBA financing.
The optimal structure could depend on down payment, business cash flow, expansion plans and whether equipment or working capital is also needed.
Multifamily Investment Property
A stabilized apartment property could potentially attract banks, credit unions, agency lenders, CMBS lenders and other capital sources depending on property size, leverage and economics.
Transitional Commercial Property
A property undergoing renovation, lease-up or repositioning may not qualify for permanent financing today.
A bridge lender or debt fund may provide a transitional structure until the property reaches stabilization.
Commercial Real Estate Refinance
An owner facing an upcoming maturity may need to compare proceeds, DSCR requirements, amortization and prepayment terms across several lender categories.
Different transactions require different capital strategies.
That's exactly why starting with the deal rather than a predetermined lender can be so important.
The New Question: Which Lender Fits the Deal?
For years, commercial borrowers often approached financing from the opposite direction.
They started with their banking relationship and tried to determine whether the deal fit the bank.
The technology-enabled brokerage model starts with the transaction.
What is the property?
How much is it worth?
How much NOI does it generate?
What is the borrower trying to accomplish?
How much leverage is needed?
How long does the borrower expect to own the asset?
What risks need to be addressed?
Once those questions are answered, the capital search becomes more focused.
Instead of forcing a transaction into a predetermined lending box, the objective becomes identifying capital sources whose lending criteria fit the transaction.
Better Data Can Produce a Better Financing Process
Technology alone won't fix a poorly structured loan request.
The quality of the submission still matters.
A well-prepared commercial financing package should typically communicate:
·Property information
·Requested loan amount
·Purchase price or estimated value
·Current rent roll
·Historical operating statements
·Borrower financial strength
·Ownership structure
·Existing debt
·Capital improvement plans
·Sources and uses
·Transaction objectives
The easier it is for a lender to understand the transaction, the easier it becomes to determine whether the opportunity fits its credit box.
That is why preparation remains one of the most important parts of commercial real estate financing.
What This Means for Commercial Real Estate Investors
Investors have more ways to access commercial real estate capital than many realize.
The market extends well beyond the bank branch down the street.
Technology is making that broader capital market easier to navigate.
But the objective shouldn't be to send a deal indiscriminately to as many lenders as possible.
The objective is to combine technology, lender access and capital markets expertise to identify financing structures appropriate for the transaction.
That's the emerging commercial mortgage brokerage model:
One transaction. A broad lender marketplace. A more strategic capital search.
Looking for Commercial Real Estate Financing?
If you're buying, refinancing or recapitalizing commercial real estate, the financing conversation should begin with your transaction and your objectives—not with a predetermined lender.
Through the Bill Rapp – CommLoan Empower Program, I help commercial real estate investors and business owners evaluate their financing needs and navigate a broad marketplace of potential capital sources.
Whether you're financing multifamily, industrial, retail, office, hospitality, land or an owner-occupied commercial property, the goal is straightforward:
Understand the deal. Structure the request. Explore the market. Identify potential financing solutions.
Visit billrapp.commloan.com to explore your commercial real estate financing options.
Top of Form
Bottom of Form
Bill Rapp, CCIM
Director | CommLoan
📞 281-222-0433
📧 [email protected]
🌐 https://billrapp.commloan.com/
🌐 https://HoustonCommercialMortgage.com/
Commercial Real Estate Financing Nationwide
https://billrapp.commloan.com/
https://author.billrapponline.com/
https://www.amazon.com/dp/B0F32Z5BH2
https://veed.cello.so/FOmzTty6oi9
https://buymeacoffee.com/vikingente3
https://creplaybookseries.billrapponline.com
https://creplaybook.billrapponline.com/
©Bill Rapp, CCIM - Director - CommLoan
10 Tips for First-Time Homebuyers
Buying your first home can be both exciting and nerve-wracking at the same time. With so many things to consider and....
How To Choose the Right Lender for You
Lorem Ipsum is simply dummy text of the printing and typesetting industry. Lorem Ipsum has been the industry's standard dummy
Refinancing youe loan and when to do it
Lorem Ipsum is simply dummy text of the printing and typesetting industry. Lorem Ipsum has been the industry's standard dummy
🧮 Renovation ROI Calculator
🛠️ Renovation ROI Calculator 💰
Copyright ©2021 | Mortgage Viking Team
Licensed to Do Business | NMLS # 228246
This is not an offer to enter into an agreement. Not all customers will qualify. Information, rates and programs are subject to change without notice. All products are subject to credit and property approval. Other restrictions and limitations may apply. Copyright © 2021 | Medallion Funds
Corporate | NMLS ID NMLS # 1825831
Corporate Address : 2651 N. Green Valley Pkwy STE. 101 Henderson, NV 89014
Corporate NMLS NMLS # 1825831 | Company Website: https://medallionfunds.com/bill-rapp/
Copyright ©2021 | Mortgage Viking Team Licensed to Do Business | NMLS # 228246
This is not an offer to enter into an agreement. Not all customers will qualify. Information, rates and programs are subject to change without notice. All products are subject to credit and property approval. Other restrictions and limitations may apply
Corporate | NMLS ID NMLS # 1825831
Corporate Address : 2651 N. Green Valley Pkwy STE. 101 Henderson, NV 89014 https://medallionfunds.com/bill-rapp/