Tips on How to Improve Your Credit Score
Hey folks, it's time to get real about your credit score. If you're anything like me, you probably don't pay much attention to it until it's time to apply for a loan or credit card. But did you know that your credit score can make or break your ability to obtain a mortgage loan?
.
When you apply for a mortgage loan, lenders take a close look at your credit score and credit history. They want to know if you're a responsible borrower who will pay back the loan on time and in full. A good credit score can help you qualify for a mortgage loan with a lower interest rate and better terms, while a poor credit score can make it more difficult to get approved and result in higher interest rates and less favorable terms.
.
In short, your credit score is one of the most important factors that lenders consider when deciding whether to approve you for a mortgage loan. By taking steps to improve your credit score, you can increase your chances of getting approved for a loan with better terms and save yourself thousands of dollars in the process.
1. Check your credit report regularly
This is a no-brainer, but it's worth repeating. Make sure to check your credit report for any errors or fraudulent activity. You can get a free credit report from each of the three major credit bureaus every year, so take advantage of it.
2. Pay your bills on time
This one seems obvious, but it's worth emphasizing. Late payments can have a big impact on your credit score, so set up automatic payments or reminders to make sure you're always on time.
3. Lower your credit utilization ratio
Your credit utilization ratio is the amount of credit you're using compared to your credit limit. Aim to keep your utilization ratio under 30% to improve your score.
1. Check your credit report regularly
This is a no-brainer, but it's worth repeating. Make sure to check your credit report for any errors or fraudulent activity. You can get a free credit report from each of the three major credit bureaus every year, so take advantage of it.
2. Pay your bills
on time
This one seems obvious, but it's worth emphasizing. Late payments can have a big impact on your credit score, so set up automatic payments or reminders to make sure you're always on time.
3. Lower your credit utilization ratio
Your credit utilization ratio is the amount of credit you're using compared to your credit limit. Aim to keep your utilization ratio under 30% to improve your score.
4. Increase your credit limit
If you're struggling to keep your credit utilization ratio low, consider asking for a credit limit increase. Just make sure not to use the extra credit as an excuse to spend more.
5. Diversify your credit
Having a mix of credit types (like a credit card, auto loan, and mortgage) can improve your credit score. But don't open new accounts just to add diversity - only take on credit that you actually need and can handle responsibly.
4. Increase your
credit limit
If you're struggling to keep your credit utilization ratio low, consider asking for a credit limit increase. Just make sure not to use the extra credit as an excuse to spend more.
5. Diversify your credit
Having a mix of credit types (like a credit card, auto loan, and mortgage) can improve your credit score. But don't open new accounts just to add diversity - only take on credit that you actually need and can handle responsibly.
Blogs
The Top 5 Mortgage Mistakes to Avoid
Buying your first home can be both exciting and nerve-wracking at the same time. With so many things to consider and....
Mortgage Do and
Do not list
Mortgages can be tricky, and it's easy to make mistakes that can end up costing you dearly. That's why we've put together this list....
Tips On How To Improve Your Credit Score
Let's talk about some ways you can improve your credit score! Your credit score is actually a big deal, and it can affect...
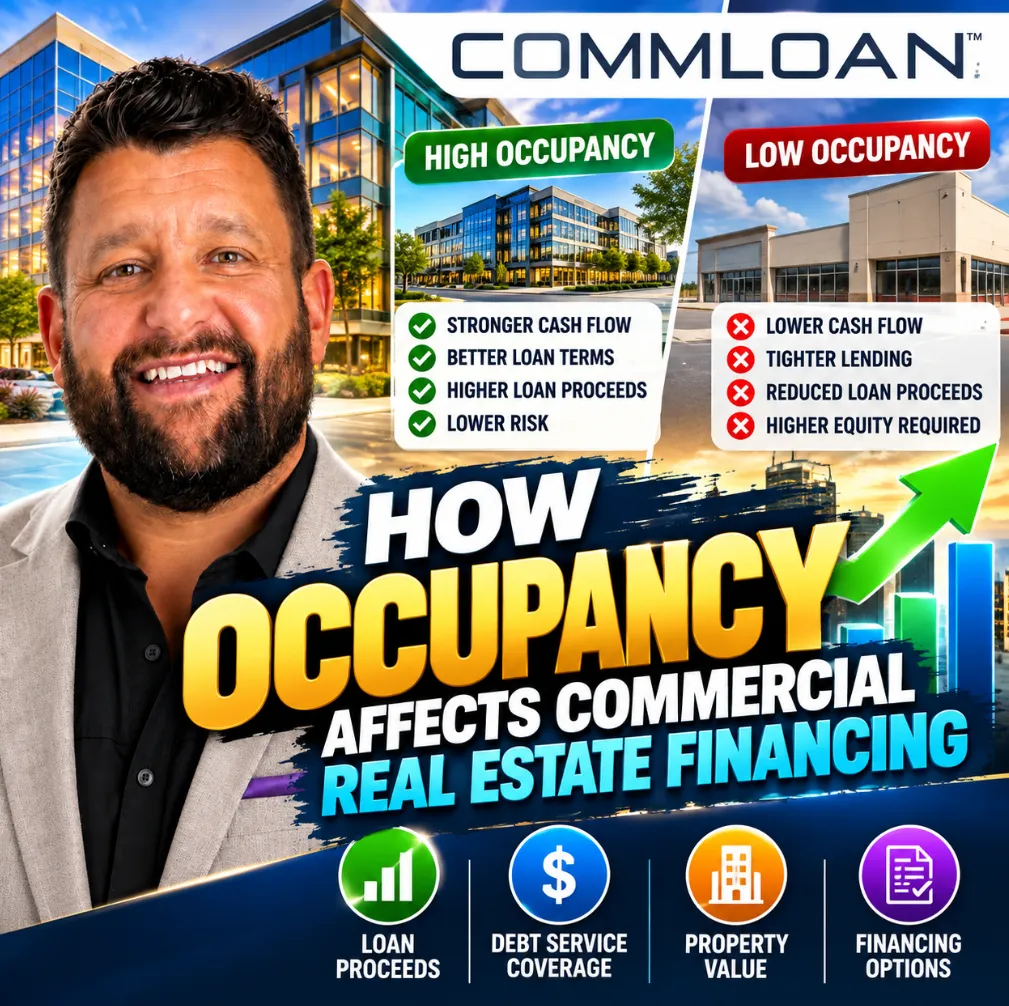
🏢 How Occupancy Affects Commercial Real Estate Financing: Why Vacancy Can Cost Investors Thousands 💰
🏢 How Occupancy Affects Commercial Real Estate Financing: Why Vacancy Can Cost Investors Thousands 💰
📉 Commercial Property Occupancy Rates: How Vacancies Impact Loan Approval, Interest Rates & Financing Terms 🏦
______________________________________________________________________________
How Occupancy Affects Commercial Real Estate Financing: Why Vacancy Matters to Lenders
When evaluating a commercial real estate investment, many buyers focus on purchase price, location, capitalization rates, and potential appreciation.
But there's another factor that can significantly influence whether a property qualifies for financing—and how much a lender is willing to advance.
Occupancy.
A commercial property might have an attractive valuation, strong market fundamentals, and significant upside potential. However, if the building has substantial vacancy, obtaining traditional commercial real estate financing can become considerably more challenging.
Understanding how occupancy affects commercial real estate financing can help investors structure acquisitions, anticipate lender requirements, and avoid surprises during underwriting.
Let's examine why occupancy matters, how lenders evaluate it, and what investors can do when financing properties with vacancies.
Why Occupancy Matters to Commercial Mortgage Lenders
Commercial real estate lenders generally evaluate a property's ability to generate sufficient income to support its mortgage payments.
For income-producing investment properties, rental revenue is a primary source of repayment.
When occupancy declines, rental collections may decrease while many operating expenses remain relatively fixed.
This creates additional risk for lenders.
For example, consider two comparable office buildings:
Property characteristic | Building A | Building B |
Total rentable area | 50,000 SF | 50,000 SF |
Physical occupancy | 95% | 65% |
Leased area | 47,500 SF | 32,500 SF |
Annual rental rate | $25/SF | $25/SF |
Potential gross rent | $1,250,000 | $1,250,000 |
In-place annual rent* | $1,187,500 | $812,500 |
*Illustrative figures assuming occupied space pays the same rent, with no concessions, collection losses, or additional income. These figures are not net operating income.
Both buildings have the same total square footage and rental rates.
However, Building A generates approximately $375,000 more in annual rental revenue.
That difference can materially affect debt service coverage, property valuation, and loan proceeds.
Key takeaway: Commercial mortgage lenders don't simply finance a property's theoretical income potential. They evaluate its existing cash flow, stability, and reasonable future performance.
Understanding Physical Occupancy vs. Economic Occupancy
Not all occupancy measurements tell the same story.
Commercial mortgage lenders frequently distinguish between physical occupancy and economic occupancy.
Physical occupancy
Physical occupancy measures how much rentable space is occupied.
\[ \text{Physical Occupancy}=\frac{\text{Occupied SF}}{\text{Total Rentable SF}}\times100 \]
If a 100,000-square-foot shopping center has 85,000 square feet occupied, its physical occupancy is 85%.
Economic occupancy
Economic occupancy measures actual rental revenue relative to the property's potential rental revenue.
A building could be 95% physically occupied but experience lower economic occupancy because of:
·Delinquent tenants
·Free-rent concessions
·Below-market leases
·Uncollected rental payments
·Other revenue losses
For underwriting purposes, economic performance can be just as important as physical occupancy.
A property with tenants occupying nearly every suite may still have financing challenges if those tenants are not paying rent consistently.
How Occupancy Impacts Debt Service Coverage Ratio (DSCR)
One of the most important measurements in commercial mortgage underwriting is the Debt Service Coverage Ratio, or DSCR.
DSCR measures how much net operating income a property generates relative to its annual debt service.
\[ DSCR=\frac{NOI}{Annual\ Debt\ Service} \]
Consider the following example.
Illustrative DSCR comparison
Higher occupancy
1.40x
$700,000 NOI ÷ $500,000 debt service
Lower occupancy
1.10x
$550,000 NOI ÷ $500,000 debt service
The lower-occupancy property produces less cash flow to cover the same mortgage payment. A lender requiring a 1.25x DSCR would find the second scenario insufficient at that debt service level.
Many commercial lenders target DSCR requirements around 1.20x–1.35x or higher, depending on the property type, loan program, and perceived risk.
When vacancy reduces NOI, borrowers may face smaller loan amounts, additional equity requirements, or a need for alternative financing.
How Occupancy Affects Commercial Loan-to-Value Ratios
Loan-to-value ratio, or LTV, compares the loan amount to the property's appraised value.
\[ LTV=\frac{Loan\ Amount}{Property\ Value} \]
A lender might advertise financing up to 75% LTV.
However, that does not mean every property qualifies for a loan equal to 75% of its value.
Commercial mortgage lenders frequently evaluate multiple constraints, including:
·LTV
·DSCR
·Debt yield
·Occupancy and leasing stability
·Borrower liquidity and experience
·Tenant creditworthiness
·Property condition and market fundamentals
The maximum loan amount is often determined by whichever underwriting constraint is most restrictive.
For example, a property appraised at $5 million might appear eligible for a $3.75 million loan at 75% LTV.
But if the property's existing income supports only $3 million under the lender's DSCR requirement, the actual financing amount may be limited to $3 million.
The lesson: Maximum advertised LTV does not guarantee maximum loan proceeds.
How Occupancy Affects Property Valuation
Vacancy can influence commercial property valuations because income-producing assets are frequently valued using the income capitalization approach.
\[ Property\ Value=\frac{NOI}{Cap\ Rate} \]
Consider a hypothetical multifamily investment with a 6.5% capitalization rate.
Illustrative value impact from lower NOI
Assumes an unchanged 6.5% capitalization rate; actual cap rates may also change with risk.
$0$3M$6M$9M$12M$650K NOI$520K NOI
A decline in NOI from $650,000 to $520,000 reduces the indicated value from $10 million to $8 million, assuming the same cap rate.
This creates a potential double impact:
1.Reduced income can lower the property's appraised value.
2.Reduced income can also limit the amount of debt the property can support.
Consequently, vacancy may affect both the valuation and the available financing.
Does Low Occupancy Mean You Cannot Obtain Commercial Financing?
Not necessarily.
Low occupancy can make traditional financing more difficult, but it does not automatically make a property unfinanceable.
Different lenders have different investment strategies, risk tolerances, and underwriting requirements.
Stabilized commercial loans
Traditional banks, credit unions, life insurance companies, agency lenders, and certain other institutions frequently favor properties with demonstrated operating stability.
A stabilized property typically has consistent occupancy, predictable collections, and sufficient cash flow to support the proposed loan.
The exact occupancy standard varies by lender and property type.
Commercial bridge loans
Bridge financing may be appropriate for properties undergoing lease-up, renovation, repositioning, or other transitional business plans.
These loans may allow investors to acquire or refinance a property before it reaches stabilized occupancy.
However, bridge loans frequently involve higher financing costs, shorter terms, interest reserves, and greater execution risk than conventional permanent loans.
Value-add commercial real estate financing
Some lenders specialize in properties where investors plan to increase occupancy, improve operations, renovate vacant suites, or replace underperforming tenants.
These transactions typically require a credible business plan, realistic lease-up assumptions, adequate capital reserves, and a viable exit strategy.
How Occupancy Affects Different Commercial Property Types
Occupancy does not carry exactly the same implications across every commercial asset class.
Property type | Important lender considerations |
Multifamily | Unit occupancy, rent collections, concessions, turnover and operating expenses |
Retail | Tenant mix, anchor tenants, lease rollover, sales performance and co-tenancy provisions |
Office | Lease terms, tenant credit, downtime, tenant improvements and leasing commissions |
Industrial | Tenant concentration, lease duration, functional utility and re-leasing prospects |
Hotels | Occupancy rate, ADR, RevPAR, operating margins and seasonality |
Self-storage | Physical and economic occupancy, rental rates, concessions and competitive supply |
For example, a 90% occupied multifamily property may present a very different risk profile from a 90% leased office property where the largest tenant's lease expires in six months.
Similarly, hotel occupancy is only one component of hotel underwriting. Average daily rate, revenue per available room, operating expenses, brand affiliation, and historical performance can be equally important.
Why Tenant Quality Matters Alongside Occupancy
High occupancy does not always equal low risk.
Imagine two retail centers.
The first is 100% occupied but relies heavily on one tenant with deteriorating financial performance.
The second is 90% occupied but has a diversified tenant roster, strong payment history, and staggered lease expirations.
Depending on the circumstances, a lender might consider the second property more stable.
Lenders may review tenant financial strength, lease guarantees, rent payment history, tenant concentration, remaining lease terms, and rollover exposure.
The objective is to determine not only whether the property is occupied today, but also how dependable its future income may be.
Five Ways Investors Can Improve Financing Opportunities When Occupancy Is Low
1. Develop a realistic lease-up strategy. Provide evidence supporting achievable rental rates, tenant demand, anticipated absorption, and leasing costs.
2. Maintain adequate liquidity. Demonstrate sufficient reserves to cover operating shortfalls, tenant improvements, leasing commissions, and unexpected expenses.
3. Strengthen the property's financial documentation. Prepare an accurate rent roll, trailing 12-month operating statement, lease abstracts, and documentation of actual collections.
4. Consider transitional financing. A bridge or value-add loan may provide time to stabilize the asset before refinancing into longer-term permanent financing.
5. Work with a commercial mortgage advisor early. Comparing financing structures before submitting an offer can help identify potential equity requirements, lender restrictions, and exit risks.
What Documentation Will Lenders Request?
For properties experiencing vacancy or inconsistent collections, lenders may request additional supporting information.
Common underwriting documents include the current rent roll, trailing 12-month income and expense statement, historical operating statements, copies of major leases, tenant payment history, lease expiration schedule, property tax information, insurance expenses, capital improvement budget, and borrower financial statements.
For transitional properties, lenders may also require a lease-up forecast, detailed renovation budget, market rent analysis, and proposed stabilization timeline.
Accurate documentation can help lenders distinguish between a property with temporary vacancies and one with persistent structural problems.
How the CommLoan Empower Program Helps Investors Compare Financing Options
Commercial real estate financing is not one-size-fits-all.
Two lenders reviewing the same property can arrive at very different conclusions regarding acceptable occupancy, loan proceeds, pricing, amortization, recourse, and prepayment provisions.
Through the CommLoan Empower Program, I help commercial real estate investors evaluate financing alternatives based on the property's actual financial performance and investment strategy.
With access to the CommLoan CUPID™ platform and a network of 700+ lenders, we can evaluate potential lending options across different property types and financing structures.
The goal is not simply to find the lowest advertised interest rate.
It is to identify a financing structure that aligns with the property's cash flow, the investor's business plan, and the intended exit strategy.
Frequently Asked Questions
What occupancy rate do commercial lenders require?
There is no universal requirement. Some stabilized lending programs may prefer occupancy around 85%–90% or higher, while other lenders and transitional programs may accept substantially lower occupancy. Requirements depend on property type, loan structure, cash flow, and lender guidelines.
Can I finance a commercial property that is only 60% occupied?
Potentially. A property with 60% occupancy may qualify for certain bridge, value-add, or other specialized financing programs. Loan terms will depend on existing income, property value, sponsor strength, capital reserves, and the stabilization plan.
Does higher occupancy guarantee a better interest rate?
No. Higher occupancy may improve perceived stability, but interest rates also depend on market conditions, leverage, debt coverage, loan structure, property type, and borrower qualifications.
Does a vacant commercial property qualify for financing?
Yes, in some circumstances. Financing may be available through bridge lenders, construction or redevelopment lenders, owner-occupied programs, or other specialized capital sources. However, a fully vacant investment property generally presents different underwriting challenges than a stabilized asset.
Can I refinance after increasing occupancy?
Potentially. Increasing occupancy and NOI can improve refinancing eligibility and support higher loan proceeds. Actual results depend on lender seasoning requirements, appraisal, debt service coverage, market conditions, and existing loan payoff obligations.
Final Thoughts: Occupancy Is More Than a Leasing Statistic
Occupancy directly influences how commercial lenders evaluate cash flow, risk, property value, and available loan proceeds.
A property with strong occupancy and dependable collections may qualify for more attractive financing alternatives.
A property with substantial vacancy may require additional equity, transitional financing, or a more detailed stabilization strategy.
Neither situation automatically determines whether an investment is worthwhile.
What matters is understanding how the property's current performance fits the financing structure and the investor's objectives.
Before you purchase or refinance a commercial property, evaluate the financing implications of its actual occupancy—not just its potential.
Ready to Evaluate Your Commercial Property Financing Options?
I'm Bill Rapp, CCIM, with the CommLoan Empower Program.
Whether you're acquiring a stabilized commercial property, refinancing an existing investment, or financing a value-add opportunity, I can help you evaluate potential lending options.
Top of Form
Bottom of Form
Bill Rapp, CCIM
Director | CommLoan
📞 281-222-0433
📧 [email protected]
🌐 https://billrapp.commloan.com/
🌐 https://HoustonCommercialMortgage.com/
Commercial Real Estate Financing Nationwide
https://billrapp.commloan.com/
https://author.billrapponline.com/
https://www.amazon.com/dp/B0F32Z5BH2
https://veed.cello.so/FOmzTty6oi9
https://buymeacoffee.com/vikingente3
https://creplaybookseries.billrapponline.com
https://creplaybook.billrapponline.com/
©Bill Rapp, CCIM - Director - CommLoan
10 Tips for First-Time Homebuyers
Buying your first home can be both exciting and nerve-wracking at the same time. With so many things to consider and....
How To Choose the Right Lender for You
Lorem Ipsum is simply dummy text of the printing and typesetting industry. Lorem Ipsum has been the industry's standard dummy
Refinancing youe loan and when to do it
Lorem Ipsum is simply dummy text of the printing and typesetting industry. Lorem Ipsum has been the industry's standard dummy
🧮 Renovation ROI Calculator
🛠️ Renovation ROI Calculator 💰
Copyright ©2021 | Mortgage Viking Team
Licensed to Do Business | NMLS # 228246
This is not an offer to enter into an agreement. Not all customers will qualify. Information, rates and programs are subject to change without notice. All products are subject to credit and property approval. Other restrictions and limitations may apply. Copyright © 2021 | Medallion Funds
Corporate | NMLS ID NMLS # 1825831
Corporate Address : 2651 N. Green Valley Pkwy STE. 101 Henderson, NV 89014
Corporate NMLS NMLS # 1825831 | Company Website: https://medallionfunds.com/bill-rapp/
Copyright ©2021 | Mortgage Viking Team Licensed to Do Business | NMLS # 228246
This is not an offer to enter into an agreement. Not all customers will qualify. Information, rates and programs are subject to change without notice. All products are subject to credit and property approval. Other restrictions and limitations may apply
Corporate | NMLS ID NMLS # 1825831
Corporate Address : 2651 N. Green Valley Pkwy STE. 101 Henderson, NV 89014 https://medallionfunds.com/bill-rapp/