Low Rates.
Our rates are low, our application is quick and easy! We can get you clear to close in as little as 10 days!
Trusted By Agents With
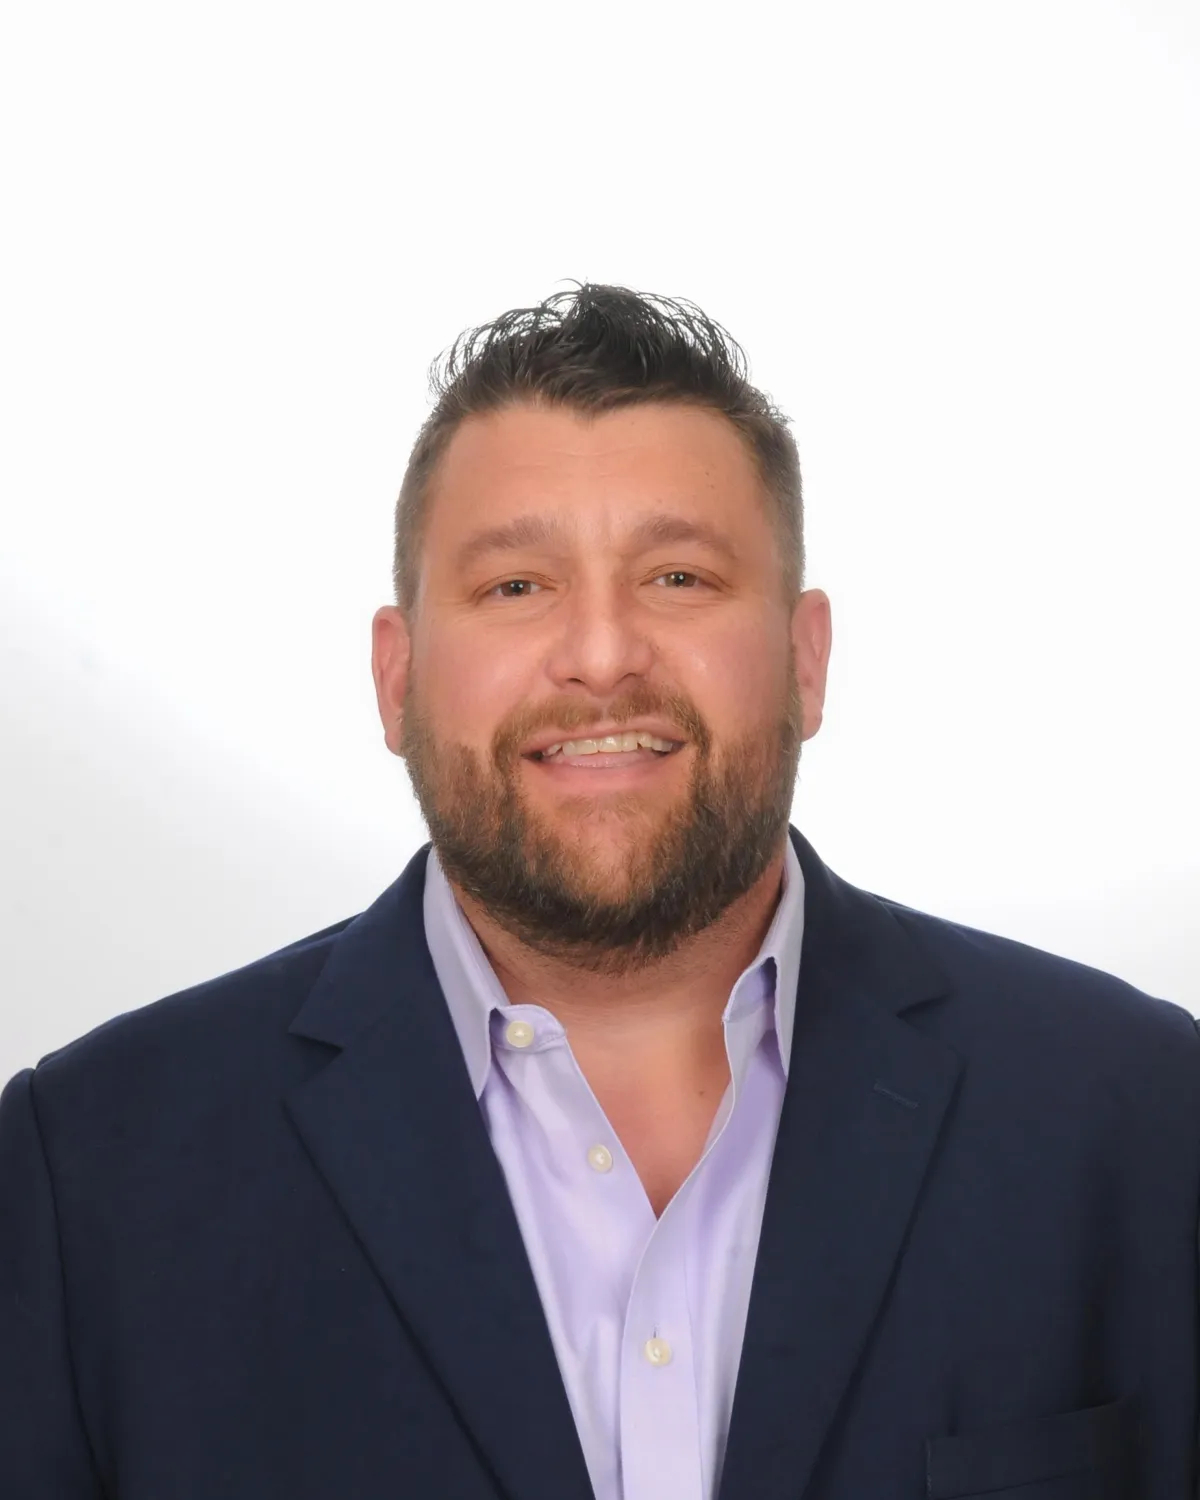
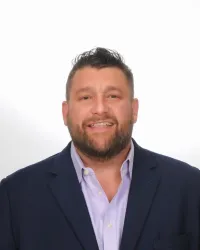
Meet Bill Rapp
NMLS ID # NMLS # 228246
Bill Rapp, CCIM is a Houston-based Capital Advisor at Medallion Funds, specializing in commercial real estate finance and strategic lending solutions. With over two decades of experience across brokerage and capital markets, Bill has worked with leading firms including eXp Commercial, NEXA Mortgage, Viking Enterprise LLC, and Sun Realty Houston.
A graduate of Texas A&M University with a BBA in Finance, Bill brings a disciplined, underwriting-first approach to every deal. His expertise spans commercial and residential financing, including asset-based lending, FHA financing, reverse mortgages, REO properties, and investment strategies for both single-family and commercial assets.
Known for his focus on structure over rate, Bill helps investors, business owners, and developers navigate complex transactions with clarity, precision, and a long-term wealth-building mindset.
The Client Experience
Great experience purchasing our first home! Bill was easy to reach and always able to answer any questions or concerns.

Loan Programs Available
Blogs
The Top 5 Mortgage Mistakes to Avoid
Buying your first home can be both exciting and nerve-wracking at the same time. With so many things to consider and....
Mortgage Do and
Do not list
Mortgages can be tricky, and it's easy to make mistakes that can end up costing you dearly. That's why we've put together this list....
Tips On How To Improve Your Credit Score
Let's talk about some ways you can improve your credit score! Your credit score is actually a big deal, and it can affect...
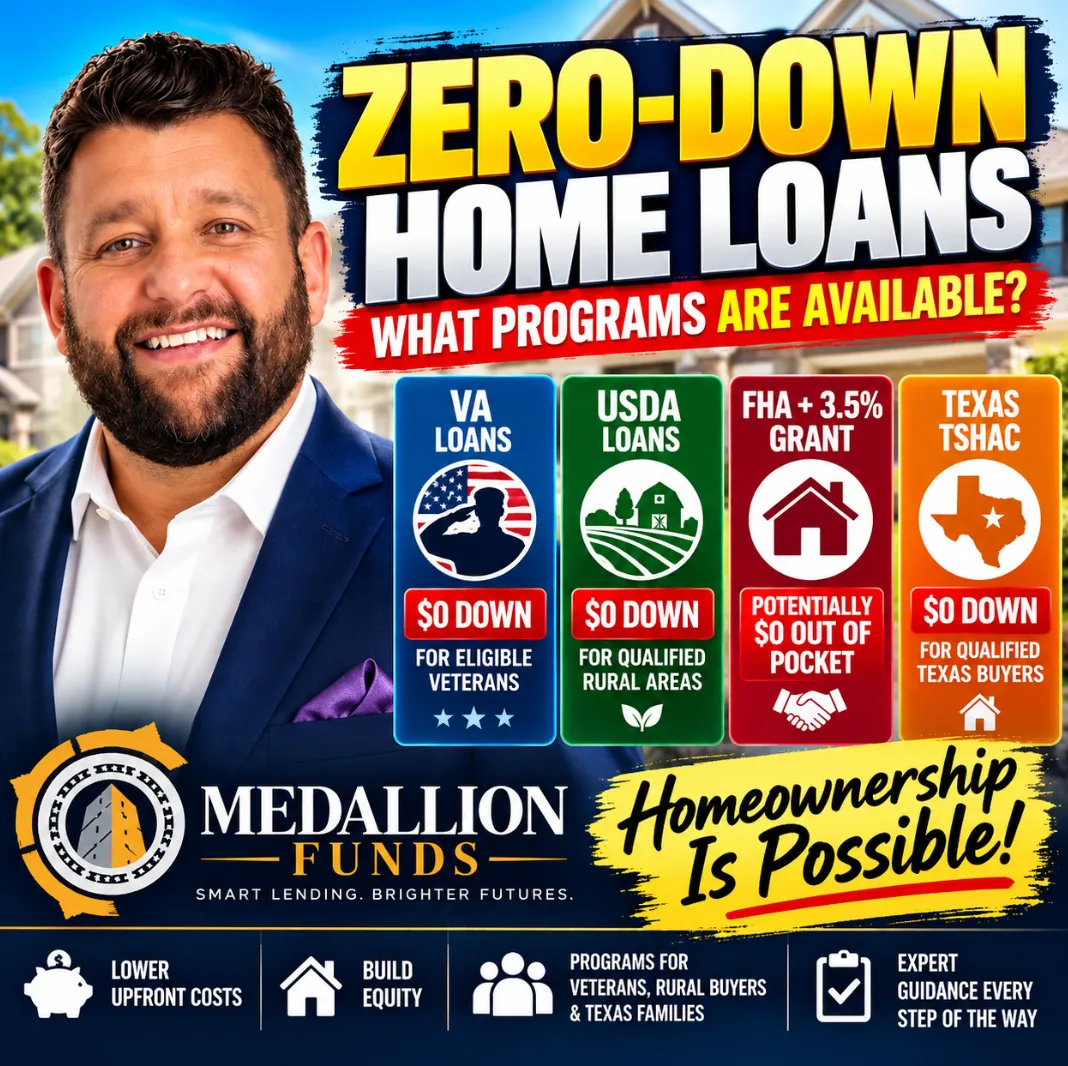
🏡 Zero-Down Home Loans in 2026: VA, USDA, FHA Grants & Texas TSHAC Programs Explained! 💰
🏡 Zero-Down Home Loans in 2026: VA, USDA, FHA Grants & Texas TSHAC Programs Explained! 💰
💵 Buy a Home With Little or No Money Down! 4 Mortgage Programs Every Texas Homebuyer Should Know 🏠
____________________________________________________________________________
🏡 Zero-Down Home Loans in 2026: VA, USDA, FHA Grants & Texas TSHAC Programs Explained!
By Bill Rapp, CCIM | Director of Capital Advisory | Medallion Funds LLC | NMLS #228246
Can you really buy a house with zero money down?
For many prospective homebuyers in Katy, Fulshear, Houston, and across Texas, the biggest obstacle to homeownership isn't necessarily the monthly mortgage payment. It's saving enough money for a down payment and closing costs.
Here's something many buyers don't realize: You may qualify for a mortgage that requires no down payment—or receive assistance that covers some or all of your required down payment.
Several financing options can help make homeownership more accessible, including:
·VA home loans for eligible military borrowers.
·USDA home loans for qualifying rural and suburban properties.
·FHA mortgages paired with eligible down payment assistance or grants.
·Texas State Affordable Housing Corporation (TSAHC) homebuyer assistance programs.
However, not all zero-down mortgage options work the same way, and zero down does not automatically mean zero closing costs or zero cash needed at closing.
Let's explore how each program works, who may qualify, and what you should consider before purchasing your next home.
1. VA Home Loans: Zero Down for Eligible Veterans and Military Families
The VA home loan program is one of the most valuable mortgage benefits available to eligible military borrowers.
Backed by the U.S. Department of Veterans Affairs, VA mortgages allow qualified borrowers to finance an eligible primary residence with no required down payment, provided the loan meets VA and lender requirements.
Key Benefits of VA Loans
·Zero down payment may be available.
·No monthly private mortgage insurance (PMI).
·Competitive mortgage interest rates may be available.
·Flexible underwriting considerations.
·Options to purchase, build, or refinance an eligible home.
·Certain borrowers are exempt from the VA funding fee.
Who Qualifies?
Eligibility may include qualifying veterans, active-duty service members, certain National Guard and Reserve members, and eligible surviving spouses.
A Certificate of Eligibility helps establish VA entitlement, but lenders must also evaluate income, credit, residual income, and other qualification factors.
Example: Purchasing a $350,000 Home
A qualified VA buyer purchasing a $350,000 home may be able to finance the entire purchase price without making a down payment.
Compare that with a conventional mortgage requiring 5% down:
·Purchase price: $350,000
·Conventional 5% down payment: $17,500
·VA required down payment: Potentially $0
The buyer may preserve $17,500 in savings that otherwise would have gone toward the down payment.
Important: Closing costs, prepaid expenses, and a VA funding fee may still apply. The funding fee may be financed when permitted, and eligible borrowers may qualify for an exemption.
2. USDA Home Loans: Zero Down in Eligible Rural and Suburban Areas
Think USDA mortgages are only available to farmers?
That's a common misconception.
The USDA Single Family Housing Guaranteed Loan Program helps eligible low- and moderate-income households purchase qualifying primary residences in designated rural areas.
Some suburban and outlying communities may qualify, depending on the property's exact location.
Benefits of USDA Financing
·No required down payment for qualified borrowers.
·Fixed-rate mortgage options.
·Financing for eligible primary residences.
·Income-based eligibility.
·Potentially competitive financing terms.
What Are the Requirements?
USDA eligibility generally depends on:
1.Property location: The home must be in a USDA-eligible area.
2.Household income: Income generally cannot exceed 115% of the applicable area median household income for the guaranteed loan program, subject to USDA calculations and adjustments.
3.Primary residence: The home must be occupied as the buyer's principal residence.
4.Credit and repayment ability: Borrowers must meet applicable underwriting requirements.
USDA Loans Near Houston
Buyers searching in outlying portions of Greater Houston, including areas around Fulshear, Brookshire, and surrounding communities, should investigate USDA eligibility.
However, eligibility must be confirmed for the specific property address. A city's name or ZIP code alone does not establish eligibility.
USDA guaranteed loans also generally carry upfront and annual guarantee fees.
3. FHA Loans With 3.5% Down Payment Assistance: Can You Buy With No Down Payment?
FHA loans are especially popular among first-time homebuyers because they permit down payments as low as 3.5% for qualified borrowers.
But here's where the opportunity becomes interesting.
Some homebuyers may qualify for an eligible down payment assistance program that covers the FHA minimum required investment.
How FHA Down Payment Assistance Works
Imagine purchasing a $300,000 home.
With a standard 3.5% FHA down payment:
·Purchase price: $300,000
·FHA minimum down payment: $10,500
·Eligible assistance: $10,500
·Potential down payment from personal savings: $0
This example assumes a qualifying assistance program provides the full amount and that its funds are permitted under FHA rules.
Is the 3.5% Assistance Always a Grant?
No.
This is one of the most important distinctions buyers should understand.
Down payment assistance may come in several forms:
·True grants: Generally do not require repayment when program conditions are satisfied.
·Forgivable second mortgages: May be forgiven after meeting occupancy and other requirements.
·Deferred-payment second mortgages: Repayment may be delayed until sale, refinance, or another triggering event.
·Repayable second mortgages: Require repayment under the program's terms.
Some assistance programs are advertised as FHA grant programs, but the actual funding structure must be reviewed carefully.
FHA rules also restrict who may provide funds toward the borrower's minimum required investment. Not every seller credit, lender credit, or advertised assistance product can substitute for the required down payment.
FHA Mortgage Insurance
FHA loans generally include both upfront and annual mortgage insurance premiums.
That means a borrower who qualifies for zero personal down payment through assistance may still have a higher monthly payment than expected.
The goal should be to evaluate the complete mortgage—not simply the cash needed to close.
4. Texas TSAHC Homebuyer Programs: Down Payment Assistance for Eligible Buyers
Texas has homebuyer assistance programs that can help qualified buyers overcome the upfront cost of purchasing a home.
One important resource is the Texas State Affordable Housing Corporation (TSAHC).
TSAHC offers mortgage programs that may include down payment assistance for eligible Texas homebuyers.
Two widely recognized programs are:
Homes for Texas Heroes
This program is designed for eligible professionals in designated occupations, potentially including teachers, firefighters, EMS personnel, police officers, corrections officers, and certain veterans or military-related categories, subject to current program definitions.
Home Sweet Texas Home Loan Program
This program serves qualifying low- and moderate-income homebuyers, including eligible first-time and repeat buyers.
What Assistance Is Available?
Depending on the current program, participating lender, loan product, and borrower eligibility, TSAHC assistance may be available in grant or second-lien structures.
The assistance amount and whether repayment is required depend on the selected option.
Do You Have to Be a First-Time Homebuyer?
Not necessarily.
Some TSAHC options are available to qualified repeat buyers. However, additional benefits, including certain mortgage credit certificate opportunities, may have separate first-time buyer requirements or exceptions.
What About Credit Scores and Income Limits?
Program qualification can depend on:
·Minimum qualifying credit score.
·Household or borrower income limits, as applicable.
·Property location.
·Loan type.
·Homebuyer education requirements.
·Eligible property and occupancy status.
Assistance offerings, percentages, pricing, and lender participation can change. Eligibility and program availability should be verified before making an offer.
5. Comparing Zero-Down Mortgage Programs
Program | Minimum Down Payment | Primary Eligibility |
VA | Potentially 0% | Eligible military borrowers |
USDA | 0% | Eligible household and property location |
FHA + assistance | Potentially $0 personal down payment | FHA-qualified buyer with eligible assistance |
TSAHC + mortgage | Depends on loan and assistance | Qualified Texas homebuyer |
Important distinction: VA and USDA are mortgage programs that can inherently provide 100% purchase financing. FHA with assistance and TSAHC programs generally use separate assistance to help cover a down payment.
6. Does Zero Down Mean Zero Cash to Close?
Not necessarily.
Even when your down payment is completely covered, you may still need funds for:
·Lender and third-party closing costs.
·Title and settlement services.
·Appraisal and inspection expenses.
·Homeowners insurance.
·Prepaid property taxes.
·Initial escrow account deposits.
·Earnest money and option fees before closing.
In some transactions, seller concessions, permitted lender credits, or additional assistance may help reduce these expenses.
However, seller concessions are subject to program rules and cannot automatically replace the buyer's required minimum investment.
A mortgage with no down payment and a transaction with no cash required at closing are two different things.
7. Which Zero-Down Mortgage Is Best for You?
The right mortgage depends on your financial profile, property, and long-term goals.
If you're an eligible veteran, a VA mortgage may offer significant benefits.
If you're buying in a USDA-eligible area and meet household income requirements, USDA financing deserves consideration.
If you're a first-time buyer with limited savings, FHA paired with qualifying assistance may provide another path.
And if you're purchasing a home in Texas, reviewing TSAHC assistance could reveal options you haven't considered.
But don't compare programs based on down payment alone.
Compare the interest rate, APR, mortgage insurance, assistance repayment obligations, monthly payment, and total financing costs.
A program that saves $10,000 upfront might not always be the least expensive option over five or ten years.
8. How to Get Started With a Zero-Down Home Loan
Before shopping for homes, I recommend five practical steps.
Step 1: Review your credit. Understand your credit profile and address any issues that could affect approval.
Step 2: Calculate your affordable payment. Include principal, interest, property taxes, homeowners insurance, mortgage insurance, and applicable HOA dues.
Step 3: Verify program eligibility. Determine whether VA, USDA, FHA assistance, or Texas TSAHC options fit your circumstances.
Step 4: Compare total financing costs. Request mortgage scenarios that disclose rates, APR, closing costs, cash to close, and assistance conditions.
Step 5: Get pre-approved. A documented pre-approval can help you shop confidently and understand the financing requirements before submitting an offer.
9. Why Work With Medallion Funds?
At Medallion Funds, I help homebuyers understand their financing options and compare mortgage structures that align with their goals.
My background in mortgage lending and real estate provides a broader perspective on how financing decisions affect affordability, purchasing power, and long-term financial flexibility.
Whether you're a veteran buying your first home, a family considering a USDA-eligible property, or a Texas buyer exploring down payment assistance, my objective is to help you understand your available options before committing.
Final Thoughts: Your Path to Homeownership May Require Less Cash Than You Think
If you've been delaying your home purchase because you believe you need 10% or 20% down, it may be time to revisit your assumptions.
VA loans, USDA financing, FHA mortgages paired with eligible assistance, and Texas TSAHC programs can potentially make homeownership more accessible.
The key is determining which options are available to you—and what each one will cost over time.
🏡 Let's Explore Your Mortgage Options
Bill Rapp
Partner & Director of Capital Advisory | Medallion Funds
Commercial Lending Nationwide
Residential Lending in AL, CA, CO, NV & TXBottom of Form
https://www.billrapponline.com/
https://findamortgagebroker.com/Profile/WilliamRappJr28883
https://billrapp.commloan.com/
https://billrapponline.com/financingfuturescre-houston-katy
https://houstoncommercialmortgage.com/
https://author.billrapponline.com
https://doctorvideo.billrapponline.com/
https://veteransvideo.billrapponline.com/
https://mortgageviking.billrapponline.com/
https://fha203h.billrapponline.com/
https://renovationvideo.billrapponline.com
https://medallionfunds.com/bill-rapp/
https://www.amazon.com/dp/B0F32Z5BH2
https://veed.cello.so/FOmzTty6oi9
https://buymeacoffee.com/vikingente3
https://creplaybookseries.billrapponline.com
https://creplaybook.billrapponline.com/
© Bill Rapp, Medallion Funds LLC, Director of Capital Advisory
10 Tips for First-Time Homebuyers
Buying your first home can be both exciting and nerve-wracking at the same time. With so many things to consider and....
How To Choose the Right Lender for You
Lorem Ipsum is simply dummy text of the printing and typesetting industry. Lorem Ipsum has been the industry's standard dummy
Refinancing youe loan and when to do it
Lorem Ipsum is simply dummy text of the printing and typesetting industry. Lorem Ipsum has been the industry's standard dummy
Copyright ©2021 | Mortgage Viking Team
Licensed to Do Business | NMLS # 228246
This is not an offer to enter into an agreement. Not all customers will qualify. Information, rates and programs are subject to change without notice. All products are subject to credit and property approval. Other restrictions and limitations may apply. Copyright © 2021 | Medallion Funds
Corporate | NMLS ID NMLS # 1825831
Corporate Address : 2651 N. Green Valley Pkwy STE. 101 Henderson, NV 89014
Corporate NMLS NMLS # 1825831 | Company Website: https://medallionfunds.com/bill-rapp/
Copyright ©2021 | Mortgage Viking Team Licensed to Do Business | NMLS # 228246
This is not an offer to enter into an agreement. Not all customers will qualify. Information, rates and programs are subject to change without notice. All products are subject to credit and property approval. Other restrictions and limitations may apply
Corporate | NMLS ID NMLS # 1825831
Corporate Address : 2651 N. Green Valley Pkwy STE. 101 Henderson, NV 89014 https://medallionfunds.com/bill-rapp/
Facebook
Instagram
X
LinkedIn
Youtube
TikTok