Low Rates.
Our rates are low, our application is quick and easy! We can get you clear to close in as little as 10 days!
Trusted By Agents With
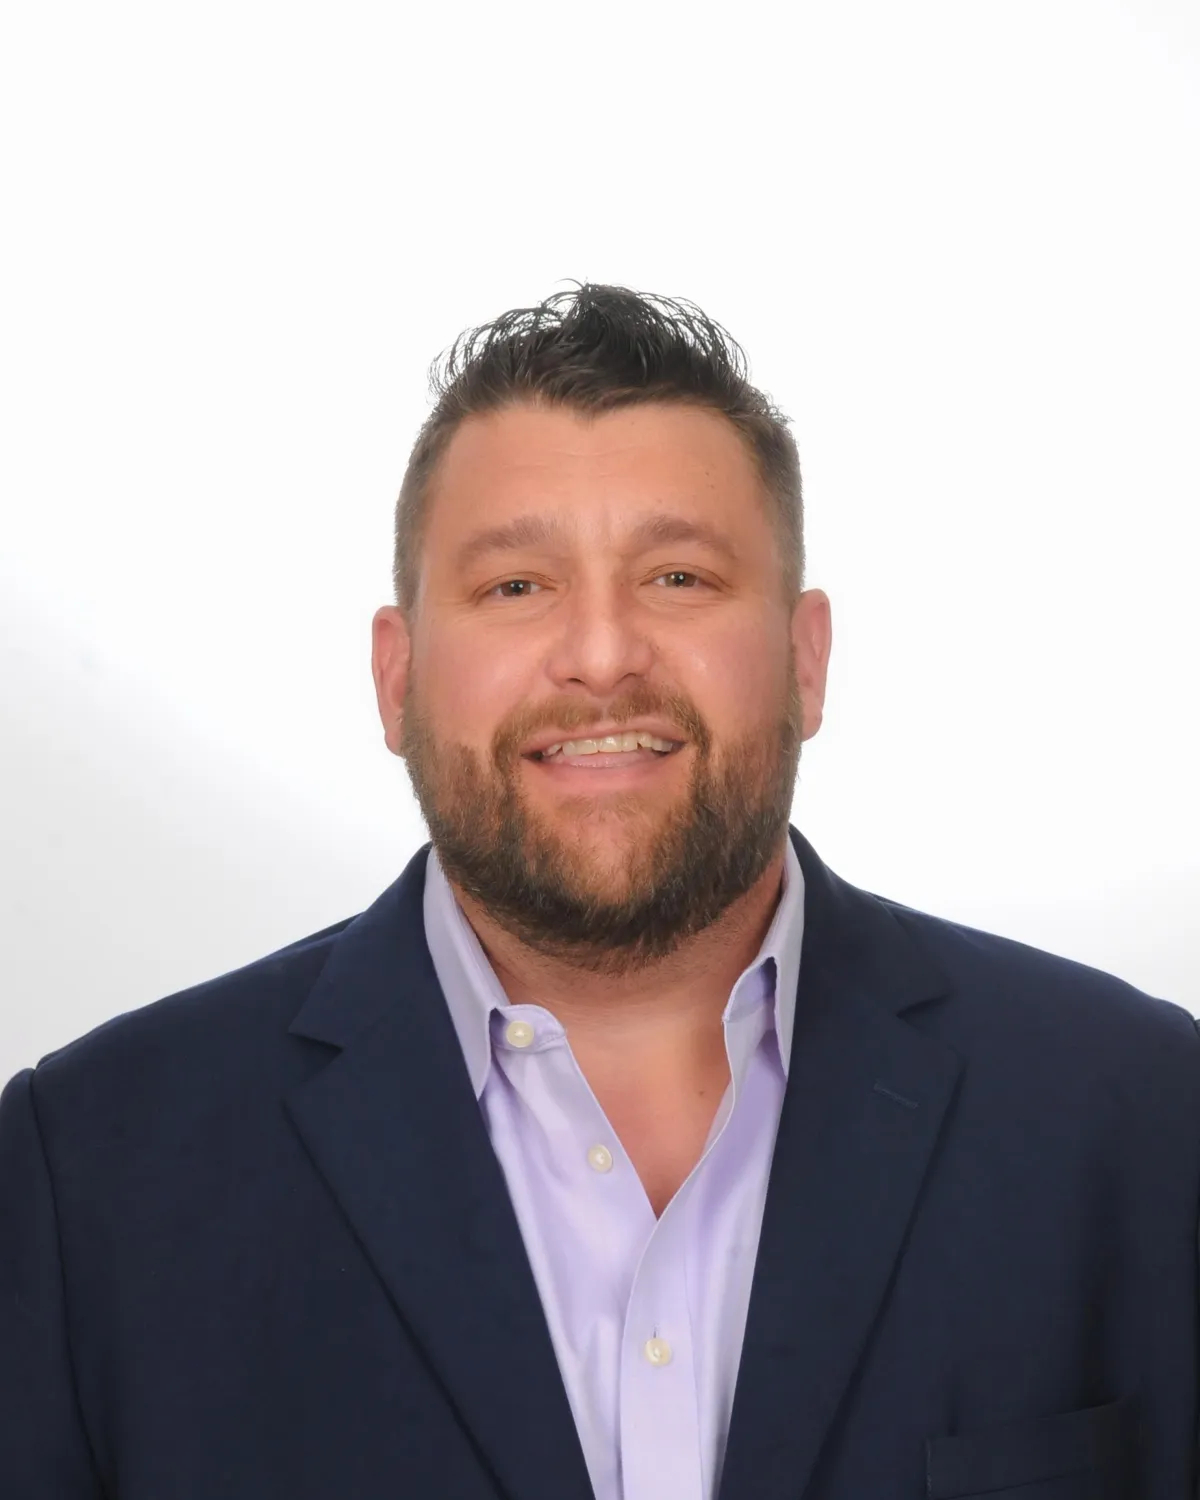
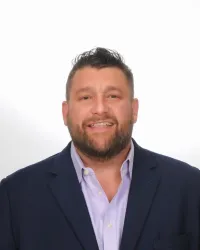
Meet Bill Rapp
NMLS ID # NMLS # 228246
Bill Rapp, CCIM is a Houston-based Capital Advisor at Medallion Funds, specializing in commercial real estate finance and strategic lending solutions. With over two decades of experience across brokerage and capital markets, Bill has worked with leading firms including eXp Commercial, NEXA Mortgage, Viking Enterprise LLC, and Sun Realty Houston.
A graduate of Texas A&M University with a BBA in Finance, Bill brings a disciplined, underwriting-first approach to every deal. His expertise spans commercial and residential financing, including asset-based lending, FHA financing, reverse mortgages, REO properties, and investment strategies for both single-family and commercial assets.
Known for his focus on structure over rate, Bill helps investors, business owners, and developers navigate complex transactions with clarity, precision, and a long-term wealth-building mindset.
The Client Experience
Great experience purchasing our first home! Bill was easy to reach and always able to answer any questions or concerns.

Loan Programs Available


Blogs
The Top 5 Mortgage Mistakes to Avoid
Buying your first home can be both exciting and nerve-wracking at the same time. With so many things to consider and....
Mortgage Do and
Do not list
Mortgages can be tricky, and it's easy to make mistakes that can end up costing you dearly. That's why we've put together this list....
Tips On How To Improve Your Credit Score
Let's talk about some ways you can improve your credit score! Your credit score is actually a big deal, and it can affect...
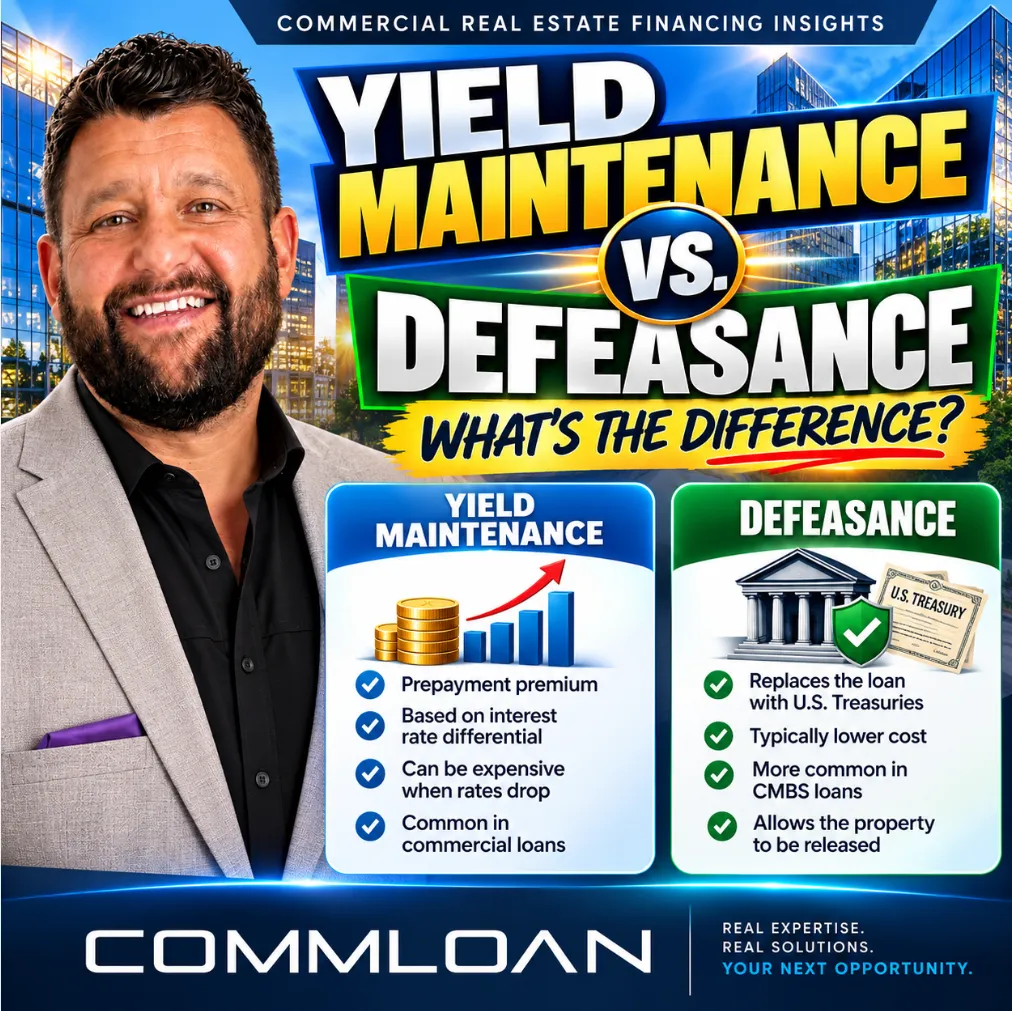
🏢 Yield Maintenance vs. Defeasance: What Commercial Real Estate Borrowers Need to Know 💰
🏢 Yield Maintenance vs. Defeasance: What Commercial Real Estate Borrowers Need to Know 💰
💵 Yield Maintenance vs. Defeasance Explained: Which Commercial Loan Prepayment Structure Costs More? 🏦
________________________________________________________________________________
Yield Maintenance vs. Defeasance: What’s the Difference?
When commercial real estate investors compare financing options, most naturally focus on the interest rate, loan proceeds, amortization, term, and recourse.
But there is another provision that can have a major impact on the economics of a commercial real estate loan:
What happens if you want to pay it off early?
Two prepayment structures investors frequently encounter—particularly with institutional and CMBS financing—are yield maintenance and defeasance.
Both are designed, in different ways, to protect the economics associated with a lender or investor receiving the originally expected stream of payments. But they work very differently.
Understanding those differences before signing your loan documents can be critical if your investment strategy includes selling, refinancing, recapitalizing, or exchanging the property before the loan matures.
What Is Yield Maintenance?
Yield maintenance is a form of prepayment premium designed to compensate the lender or investors for some or all of the economic loss associated with receiving their principal earlier than expected.
The exact calculation is controlled by the loan documents.
Conceptually, the calculation often compares the remaining contractual loan payments with a specified benchmark yield—frequently tied to U.S. Treasury securities or another benchmark specified in the documents.
If prevailing benchmark rates have fallen substantially since your loan was originated, the resulting yield-maintenance premium can be significant.
Simplified Example
Imagine an investor has a commercial mortgage with several years remaining before maturity.
The investor receives an attractive offer for the property and wants to sell.
If the loan documents require yield maintenance, paying off the mortgage may trigger a prepayment premium in addition to the outstanding principal, accrued interest, and other applicable charges.
That premium could materially affect the investor's net sale proceeds.
This is why the lowest interest rate isn't necessarily the lowest-cost loan.
The exit provisions matter too.
What Is Defeasance?
Defeasance works differently.
Instead of simply paying the loan off and calculating a contractual prepayment premium, the borrower generally substitutes a portfolio of qualifying securities for the real estate collateral.
The securities are structured to generate cash flows sufficient to satisfy the remaining scheduled debt-service obligations under the loan, subject to the specific requirements in the loan documents.
Once all defeasance requirements are satisfied, the real estate collateral can generally be released from the mortgage lien.
This allows the borrower to sell or otherwise transact with the property while the required securities support the remaining loan obligations.
Defeasance is particularly associated with CMBS loans.
Yield Maintenance vs. Defeasance
Although both structures address early loan exits, the mechanics are fundamentally different.
Yield Maintenance
The borrower generally pays the outstanding loan balance plus a contractually calculated prepayment premium. The premium is intended to address the lender's or investor's lost yield resulting from the early payoff.
Defeasance
Instead of simply paying the loan off, qualifying securities replace the property's role as collateral and provide the cash flows necessary to meet the scheduled debt obligations.
In practical terms:
Yield maintenance is primarily a prepayment-premium mechanism.
Defeasance is primarily a collateral-substitution mechanism.
That distinction matters.
Why Interest Rates Matter
The interest-rate environment can have a substantial impact on the economics of both structures.
With yield maintenance, falling benchmark rates can increase the economic value of the remaining above-market loan payments and therefore potentially increase the prepayment premium, depending on the contractual formula.
Defeasance costs can also change based on interest rates because the cost of acquiring the required securities depends on the yields available on those securities.
This means investors should not assume that their future exit cost will remain constant.
Defeasance Can Involve Additional Transaction Costs
Defeasance is not simply a matter of buying Treasury securities.
A defeasance transaction can involve multiple parties and expenses, potentially including:
·Legal counsel
·Securities professionals
·Accountants
·Servicers
·Defeasance consultants
·Rating-agency or other third-party requirements where applicable
The specific process and costs depend heavily on the loan documents and transaction.
For that reason, borrowers considering a sale or refinance should investigate defeasance requirements well before the anticipated closing date.
Which Is Better: Yield Maintenance or Defeasance?
There isn't a universal winner.
The better structure depends on the loan terms and the borrower's investment strategy.
A borrower expecting to hold an asset for the full loan term may place less emphasis on prepayment flexibility.
An investor pursuing a shorter value-add strategy may view restrictive prepayment provisions very differently.
Consider questions such as:
How long do I realistically expect to own this property?
Could I sell if values rise faster than expected?
Could I refinance if interest rates fall?
Could I execute a 1031 exchange before maturity?
What happens if my business or investment strategy changes?
These questions should be considered before closing the loan, not just when you're ready to sell.
Don't Compare Commercial Loans on Rate Alone
Suppose you're evaluating two commercial loan offers.
Loan A: Lower interest rate but restrictive prepayment provisions.
Loan B: Slightly higher rate but substantially more exit flexibility.
Which is better?
You can't answer that question from the interest rate alone.
A sophisticated commercial loan comparison should consider:
Rate + Proceeds + Term + Amortization + Recourse + Prepayment + Exit Strategy
The right financing structure should support the business plan for the property.
Ask About the Prepayment Structure Before You Close
Before accepting a commercial real estate loan, ask:
1.What prepayment provisions apply?
2.Is there yield maintenance, defeasance, a step-down penalty, a lockout, or another structure?
3.How is the prepayment amount calculated?
4.Is there a minimum prepayment premium?
5.Is there an open period near maturity?
6.What are the requirements and transaction costs associated with defeasance?
7.Can the loan be assumed by a future buyer?
8.How do these provisions fit my expected hold period?
The answers can materially affect your investment strategy.
The Bottom Line
Yield maintenance and defeasance are not the same thing.
Yield maintenance generally allows early payoff subject to a contractual premium designed to protect the economics of the lender or investors.
Defeasance generally substitutes qualifying securities for the property's collateral and cash-flow obligations so that the real estate can be released.
Both can create substantial costs and complexity when an investor wants to exit a loan early.
That's why commercial real estate borrowers should evaluate the exit structure of a loan with the same seriousness as the interest rate.
At the Bill Rapp – CommLoan Empower Program, I help commercial real estate investors and business owners compare financing alternatives based on more than rate alone. Loan proceeds, DSCR, LTV, amortization, recourse, prepayment provisions, and the borrower's exit strategy all matter.
The objective isn't simply to find a loan.
It's to find financing that fits the investment strategy.
Top of Form
Bottom of Form
Bill Rapp, CCIM
Director | CommLoan
📞 281-222-0433
📧 [email protected]
🌐 https://billrapp.commloan.com/
🌐 https://HoustonCommercialMortgage.com/
Commercial Real Estate Financing Nationwide
https://billrapp.commloan.com/
https://author.billrapponline.com/
https://www.amazon.com/dp/B0F32Z5BH2
https://veed.cello.so/FOmzTty6oi9
https://buymeacoffee.com/vikingente3
https://creplaybookseries.billrapponline.com
https://creplaybook.billrapponline.com/
©Bill Rapp, CCIM - Director - CommLoan
10 Tips for First-Time Homebuyers
Buying your first home can be both exciting and nerve-wracking at the same time. With so many things to consider and....
How To Choose the Right Lender for You
Lorem Ipsum is simply dummy text of the printing and typesetting industry. Lorem Ipsum has been the industry's standard dummy
Refinancing youe loan and when to do it
Lorem Ipsum is simply dummy text of the printing and typesetting industry. Lorem Ipsum has been the industry's standard dummy
Copyright ©2021 | Mortgage Viking Team
Licensed to Do Business | NMLS # 228246
This is not an offer to enter into an agreement. Not all customers will qualify. Information, rates and programs are subject to change without notice. All products are subject to credit and property approval. Other restrictions and limitations may apply. Copyright © 2021 | Medallion Funds
Corporate | NMLS ID NMLS # 1825831
Corporate Address : 2651 N. Green Valley Pkwy STE. 101 Henderson, NV 89014
Corporate NMLS NMLS # 1825831 | Company Website: https://medallionfunds.com/bill-rapp/
Copyright ©2021 | Mortgage Viking Team Licensed to Do Business | NMLS # 228246
This is not an offer to enter into an agreement. Not all customers will qualify. Information, rates and programs are subject to change without notice. All products are subject to credit and property approval. Other restrictions and limitations may apply
Corporate | NMLS ID NMLS # 1825831
Corporate Address : 2651 N. Green Valley Pkwy STE. 101 Henderson, NV 89014 https://medallionfunds.com/bill-rapp/
Facebook
Instagram
X
LinkedIn
Youtube
TikTok