Low Rates.
Our rates are low, our application is quick and easy! We can get you clear to close in as little as 10 days!
Trusted By Agents With
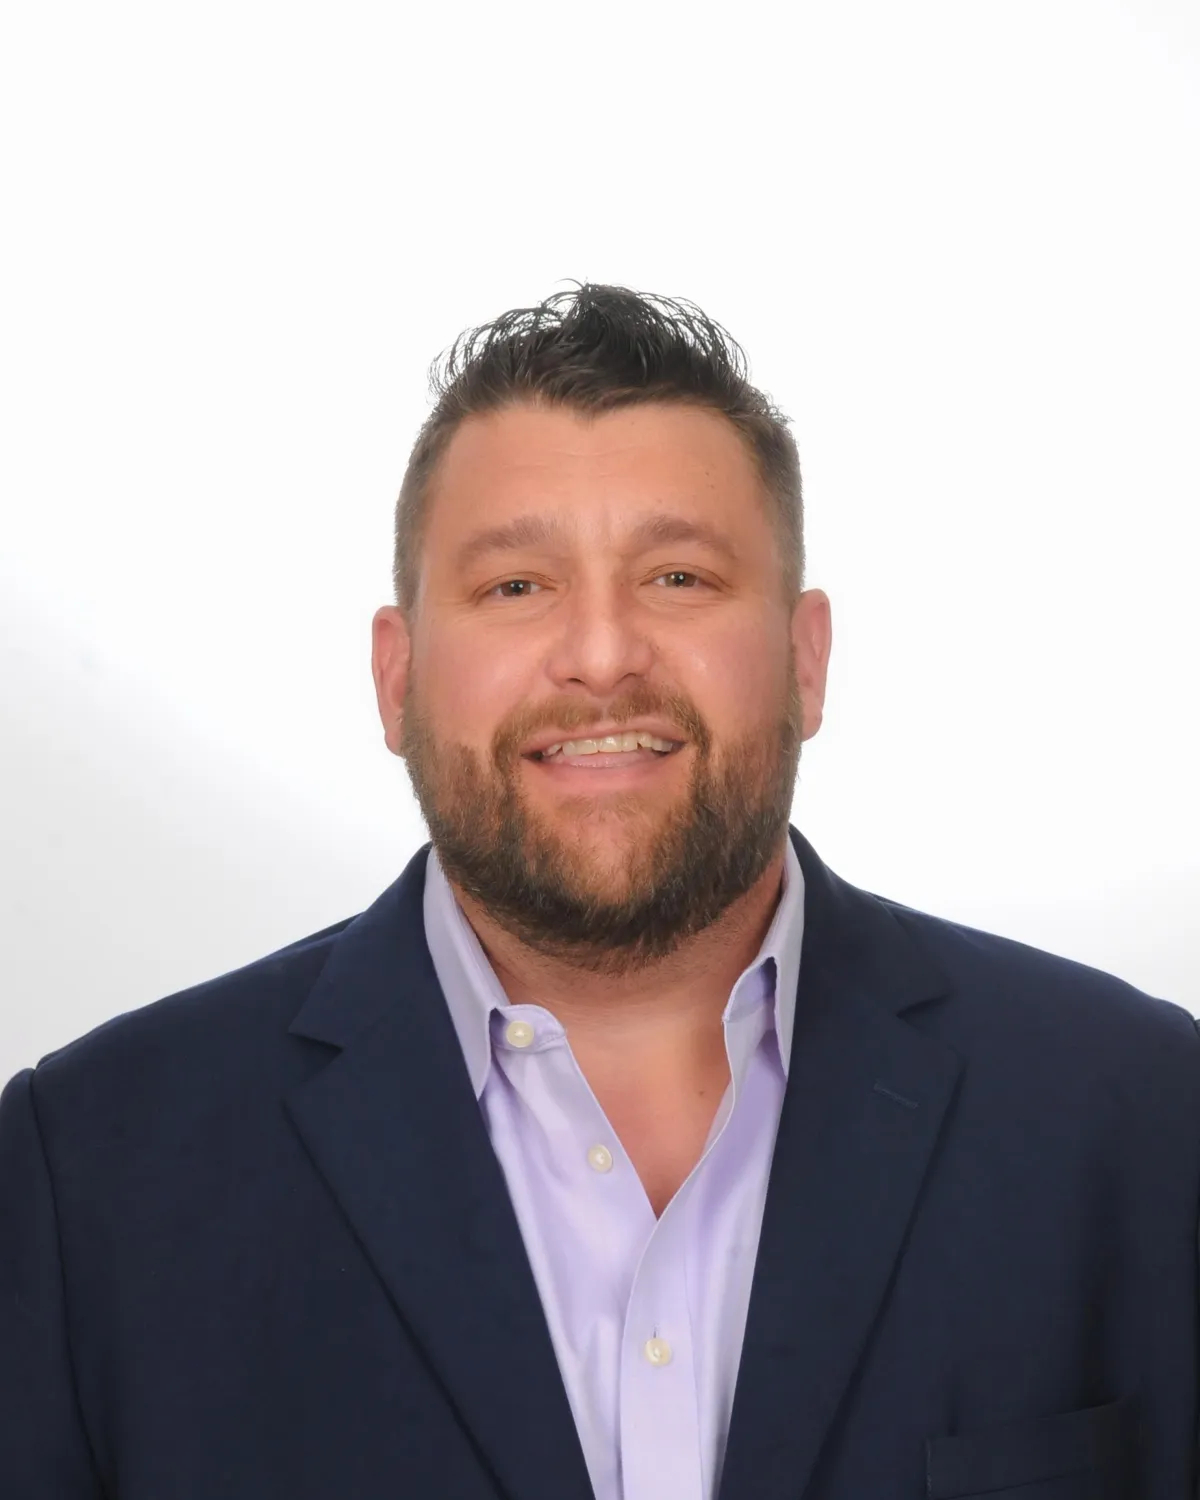
Meet Bill Rapp
NMLS ID # NMLS # 228246
Bill Rapp, CCIM is a Houston-based Capital Advisor at Medallion Funds, specializing in commercial real estate finance and strategic lending solutions. With over two decades of experience across brokerage and capital markets, Bill has worked with leading firms including eXp Commercial, NEXA Mortgage, Viking Enterprise LLC, and Sun Realty Houston.
A graduate of Texas A&M University with a BBA in Finance, Bill brings a disciplined, underwriting-first approach to every deal. His expertise spans commercial and residential financing, including asset-based lending, FHA financing, reverse mortgages, REO properties, and investment strategies for both single-family and commercial assets.
Known for his focus on structure over rate, Bill helps investors, business owners, and developers navigate complex transactions with clarity, precision, and a long-term wealth-building mindset.
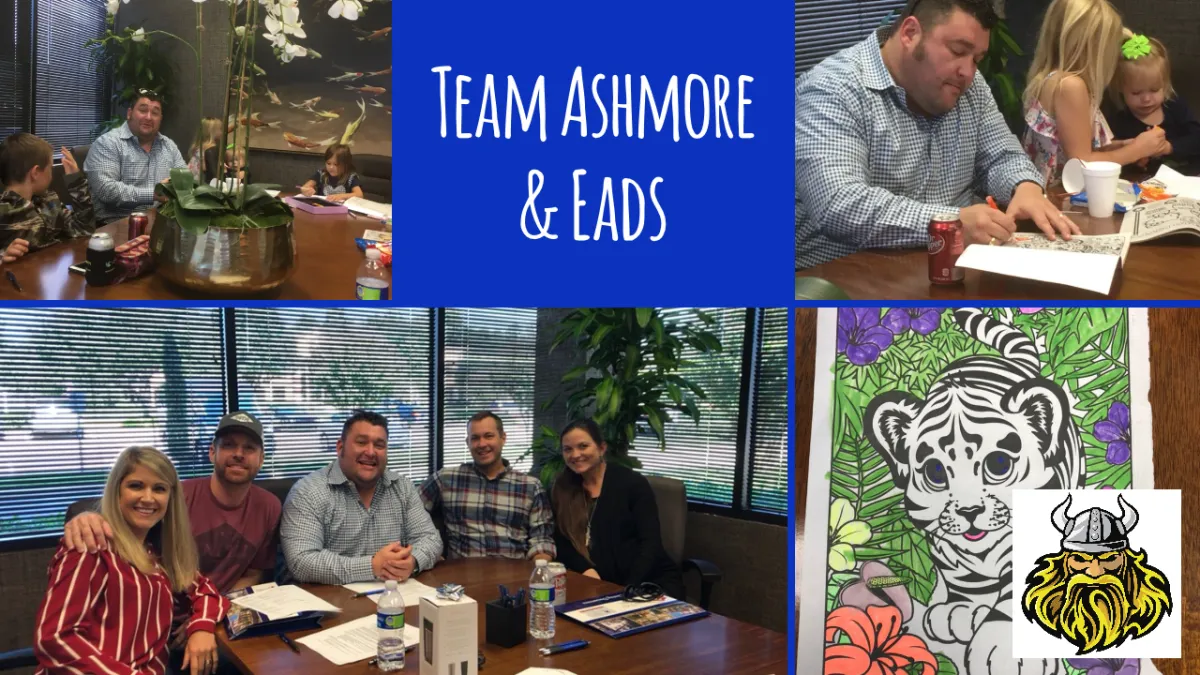
The Client Experience
Great experience purchasing our first home! Bill was easy to reach and always able to answer any questions or concerns.
Loan Programs Available


Blogs
The Top 5 Mortgage Mistakes to Avoid
Buying your first home can be both exciting and nerve-wracking at the same time. With so many things to consider and....
Mortgage Do and
Do not list
Mortgages can be tricky, and it's easy to make mistakes that can end up costing you dearly. That's why we've put together this list....
Tips On How To Improve Your Credit Score
Let's talk about some ways you can improve your credit score! Your credit score is actually a big deal, and it can affect...
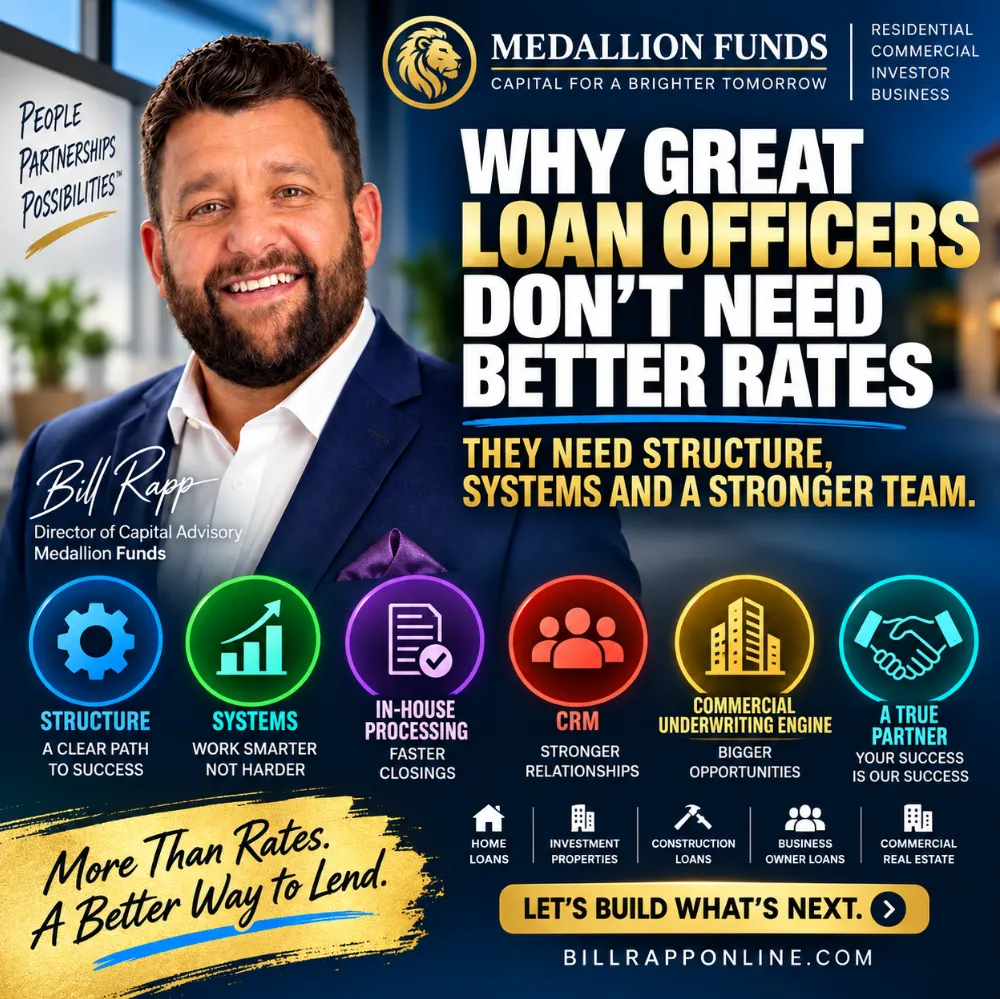
🚀 Why Great Loan Officers Don’t Need Better Rates — They Need Better Systems, Structure & Support 🚀
🚀 Why Great Loan Officers Don’t Need Better Rates — They Need Better Systems, Structure & Support 🚀
💼 Mortgage Loan Officer Success: Why Technology, Processing & Commercial Lending Matter More Than Rates 💼
Why Great Loan Officers Don’t Need Better Rates — They Need Structure, Systems and Support
Every mortgage company talks about rates.
Better pricing. Better compensation. Better products. Better lender relationships.
Those things matter.
But for an experienced mortgage loan officer trying to build a sustainable, scalable business, another slightly better rate sheet is rarely the thing holding them back.
The bigger issue is often infrastructure.
Great loan officers need a platform that helps them originate more intelligently, manage their pipeline efficiently, expand the types of financing they can offer and move qualified borrowers toward closing without unnecessary friction.
That means having the right combination of:
·Structure
·Technology
·CRM
·Processing support
·Commercial underwriting capabilities
·Diverse loan products
·Lender relationships
·Business-development systems
·Training
·A team focused on helping the loan officer grow
That is the difference between simply having somewhere to hang your mortgage license and having a platform capable of helping you build a real business.
Great Loan Officers Already Know How to Sell
Experienced loan officers usually do not need someone teaching them how to pick up the telephone.
They understand prospecting.
They understand referrals.
They understand borrowers.
They understand how important relationships are with Realtors, builders, investors, CPAs, financial advisors and business owners.
The problem comes when their platform cannot keep up with the business they are capable of generating.
A loan officer can create a fantastic opportunity and still lose the transaction because the company lacks the right loan product, lender relationship, operational system or underwriting expertise.
That is why the next generation of successful mortgage professionals will increasingly focus on platform capabilities, not simply compensation and rates.
1. Structure Creates Scalability
A good loan officer can close transactions through sheer effort.
A great mortgage business requires repeatable processes.
There should be a clear path from:
Lead → Qualification → Application → Documentation → Underwriting → Processing → Closing → Referral
Without structure, every loan becomes its own emergency.
Emails get missed.
Documents disappear.
Follow-ups happen inconsistently.
Borrowers do not know what comes next.
Referral partners receive limited communication.
And the loan officer spends valuable production time performing administrative tasks.
The objective is not to create bureaucracy.
The objective is to create a system that allows the loan officer to spend more time producing revenue and developing relationships.
2. A Strong CRM Is a Revenue Tool
A CRM should be much more than a digital address book.
Used correctly, a mortgage CRM becomes the operating system behind the loan officer's relationship business.
It can help organize:
·New mortgage leads
·Realtor relationships
·Past clients
·Builders
·Investors
·Financial advisors
·CPAs
·Commercial borrowers
·Follow-up campaigns
·Loan anniversaries
·Refinance opportunities
·Database marketing
Consider how much potential business exists inside the average experienced loan officer's database.
Past borrowers eventually move.
Investors purchase additional properties.
Homeowners refinance.
Realtors send new clients.
Business owners purchase buildings.
Doctors open practices.
Builders begin new projects.
The loan officer who consistently stays connected has a significant advantage over the loan officer whose database lives inside a cell phone.
3. In-House Processing Lets Producers Produce
One of the most expensive things a successful loan officer can do is spend hours performing work that does not require a successful loan officer.
Document chasing.
Status updates.
Organizing files.
Following up on conditions.
Coordinating transaction details.
Those functions matter tremendously, but the highest and best use of a strong originator is generally generating relationships, structuring transactions and creating new business.
That is why processing infrastructure matters.
A strong processing operation can help create better communication, cleaner files and a more predictable mortgage experience for the borrower and referral partner.
The goal is simple:
Let producers produce.
4. Commercial Lending Creates an Entirely New Conversation
Residential mortgage professionals spend years developing relationships with people who often have financing needs far beyond their homes.
Consider the clients already inside a typical loan officer's network.
A physician purchasing a home may eventually purchase a medical office.
A real estate investor buying rental houses may eventually acquire a 20-unit apartment property.
A business owner applying for a jumbo mortgage may want to purchase the building where the company operates.
A Realtor may have a client buying an investment property.
A builder may need financing for another project.
Without commercial lending capabilities, the residential loan officer may have to simply refer that business somewhere else.
Commercial lending gives the loan officer an opportunity to deepen the relationship.
5. A Commercial Underwriting Engine Changes the Conversation
Commercial real estate lending is fundamentally different from residential mortgage lending.
Commercial lenders may analyze:
·Net operating income
·Debt-service coverage ratio
·Loan-to-value
·Loan-to-cost
·Debt yield
·Property type
·Sponsor liquidity
·Sponsor experience
·Occupancy
·Tenant quality
·Lease structure
·Global cash flow
·Exit strategy
Trying to understand dozens or hundreds of different commercial lender credit boxes manually is difficult.
That is where technology becomes valuable.
A Commercial Underwriting Engine can help evaluate a transaction and identify financing structures that may fit the borrower's objectives.
Instead of randomly calling banks and hoping someone likes the deal, the objective is to diagnose the transaction first.
What is the borrower trying to accomplish?
What are the underwriting constraints?
What type of lender is most likely to finance it?
What structure gives the borrower the best probability of execution?
That is capital advisory rather than simply quoting an interest rate.
6. The Best Rate Is Not Always the Best Loan
Loan officers naturally compete on rates because borrowers ask about rates.
But sophisticated borrowers eventually learn that financing is about much more than the coupon.
Consider two lenders.
One offers a slightly lower rate but requires:
·More equity
·A shorter amortization period
·Larger reserves
·More restrictive underwriting
·A large prepayment penalty
Another lender offers a slightly higher rate but provides:
·Higher leverage
·Better amortization
·More flexible underwriting
·Faster execution
·A structure better aligned with the borrower's strategy
Which one is actually the better loan?
It depends.
That is precisely why experienced loan officers create value.
Their role is not merely finding an interest rate.
Their role is helping clients identify the right financing structure.
7. Product Depth Helps Protect Relationships
Every time a loan officer tells a qualified client, "We don't offer that," another company gets the opportunity to establish the relationship.
A broader financing platform can potentially help loan officers serve more client scenarios, including areas such as:
·Conventional mortgages
·FHA financing
·VA loans
·USDA loans
·Jumbo mortgages
·Non-QM loans
·Bank-statement programs
·DSCR investment loans
·Doctor and dentist mortgages
·Construction financing
·Renovation loans
·Bridge financing
·Commercial real estate loans
·Multifamily financing
·Owner-occupied commercial financing
·SBA financing
Not every transaction will fit every program or lender.
That is exactly the point.
Loan officers need options.
8. Technology Should Make the Loan Officer More Productive
Mortgage technology should reduce friction.
It should help the loan officer:
·Follow up faster
·Organize opportunities
·Analyze transactions
·Communicate consistently
·Market effectively
·Track borrowers
·Track referral partners
·Manage pipelines
·Identify future opportunities
Technology alone will not make someone a great originator.
But great technology in the hands of a great originator can create substantial leverage.
9. Great Loan Officers Need a Business Platform
There is a meaningful distinction between joining a mortgage company and building a mortgage business.
A mortgage company gives you somewhere to originate loans.
A mortgage business platform should help you develop:
More relationships.
More products.
More opportunities.
More systems.
More repeat business.
That is the philosophy behind the platform we are building around Medallion Funds.
The objective is not simply to tell loan officers that we have competitive rates.
Every mortgage company says that.
The bigger question is:
What happens after you generate the opportunity?
Do you have the tools to analyze it?
Do you have the products to solve it?
Do you have commercial lending capabilities?
Do you have systems to manage the relationship?
Do you have processing support?
Do you have technology that helps you scale?
Do you have a team that understands that your success drives the company's success?
Those are the questions experienced originators should be asking.
Build a Business, Not Just a Pipeline
Great loan officers do not necessarily need another mortgage company promising a marginally better rate.
They need infrastructure.
They need systems.
They need technology.
They need product depth.
They need operational support.
They need the ability to pursue opportunities beyond traditional residential mortgages.
And they need a platform designed around helping producers produce.
At Medallion Funds, that is the larger vision:
More than rates. A better way to lend.
If you are an experienced loan officer interested in expanding your residential and commercial financing capabilities, let's have a conversation.
Bill Rapp
Partner & Director of Capital Advisory | Medallion Funds
Commercial Lending Nationwide
Residential Lending in AL, CA, CO, NV & TXBottom of Form
https://www.billrapponline.com/
https://findamortgagebroker.com/Profile/WilliamRappJr28883
https://billrapp.commloan.com/
https://billrapponline.com/financingfuturescre-houston-katy
https://houstoncommercialmortgage.com/
https://author.billrapponline.com
https://doctorvideo.billrapponline.com/
https://veteransvideo.billrapponline.com/
https://mortgageviking.billrapponline.com/
https://fha203h.billrapponline.com/
https://renovationvideo.billrapponline.com
https://medallionfunds.com/bill-rapp/
https://www.amazon.com/dp/B0F32Z5BH2
https://veed.cello.so/FOmzTty6oi9
https://buymeacoffee.com/vikingente3
https://creplaybookseries.billrapponline.com
https://creplaybook.billrapponline.com/
© Bill Rapp, Medallion Funds LLC, Director of Capital Advisory
10 Tips for First-Time Homebuyers
Buying your first home can be both exciting and nerve-wracking at the same time. With so many things to consider and....
How To Choose the Right Lender for You
Lorem Ipsum is simply dummy text of the printing and typesetting industry. Lorem Ipsum has been the industry's standard dummy
Refinancing youe loan and when to do it
Lorem Ipsum is simply dummy text of the printing and typesetting industry. Lorem Ipsum has been the industry's standard dummy
Copyright ©2021 | Mortgage Viking Team
Licensed to Do Business | NMLS # 228246
This is not an offer to enter into an agreement. Not all customers will qualify. Information, rates and programs are subject to change without notice. All products are subject to credit and property approval. Other restrictions and limitations may apply. Copyright © 2021 | Medallion Funds
Corporate | NMLS ID NMLS # 1825831
Corporate Address : 2651 N. Green Valley Pkwy STE. 101 Henderson, NV 89014
Corporate NMLS NMLS # 1825831 | Company Website: https://medallionfunds.com/bill-rapp/
Copyright ©2021 | Mortgage Viking Team Licensed to Do Business | NMLS # 228246
This is not an offer to enter into an agreement. Not all customers will qualify. Information, rates and programs are subject to change without notice. All products are subject to credit and property approval. Other restrictions and limitations may apply
Corporate | NMLS ID NMLS # 1825831
Corporate Address : 2651 N. Green Valley Pkwy STE. 101 Henderson, NV 89014 https://medallionfunds.com/bill-rapp/
Facebook
Instagram
X
LinkedIn
Youtube
TikTok