Low Rates.
Our rates are low, our application is quick and easy! We can get you clear to close in as little as 10 days!
Trusted By Agents With
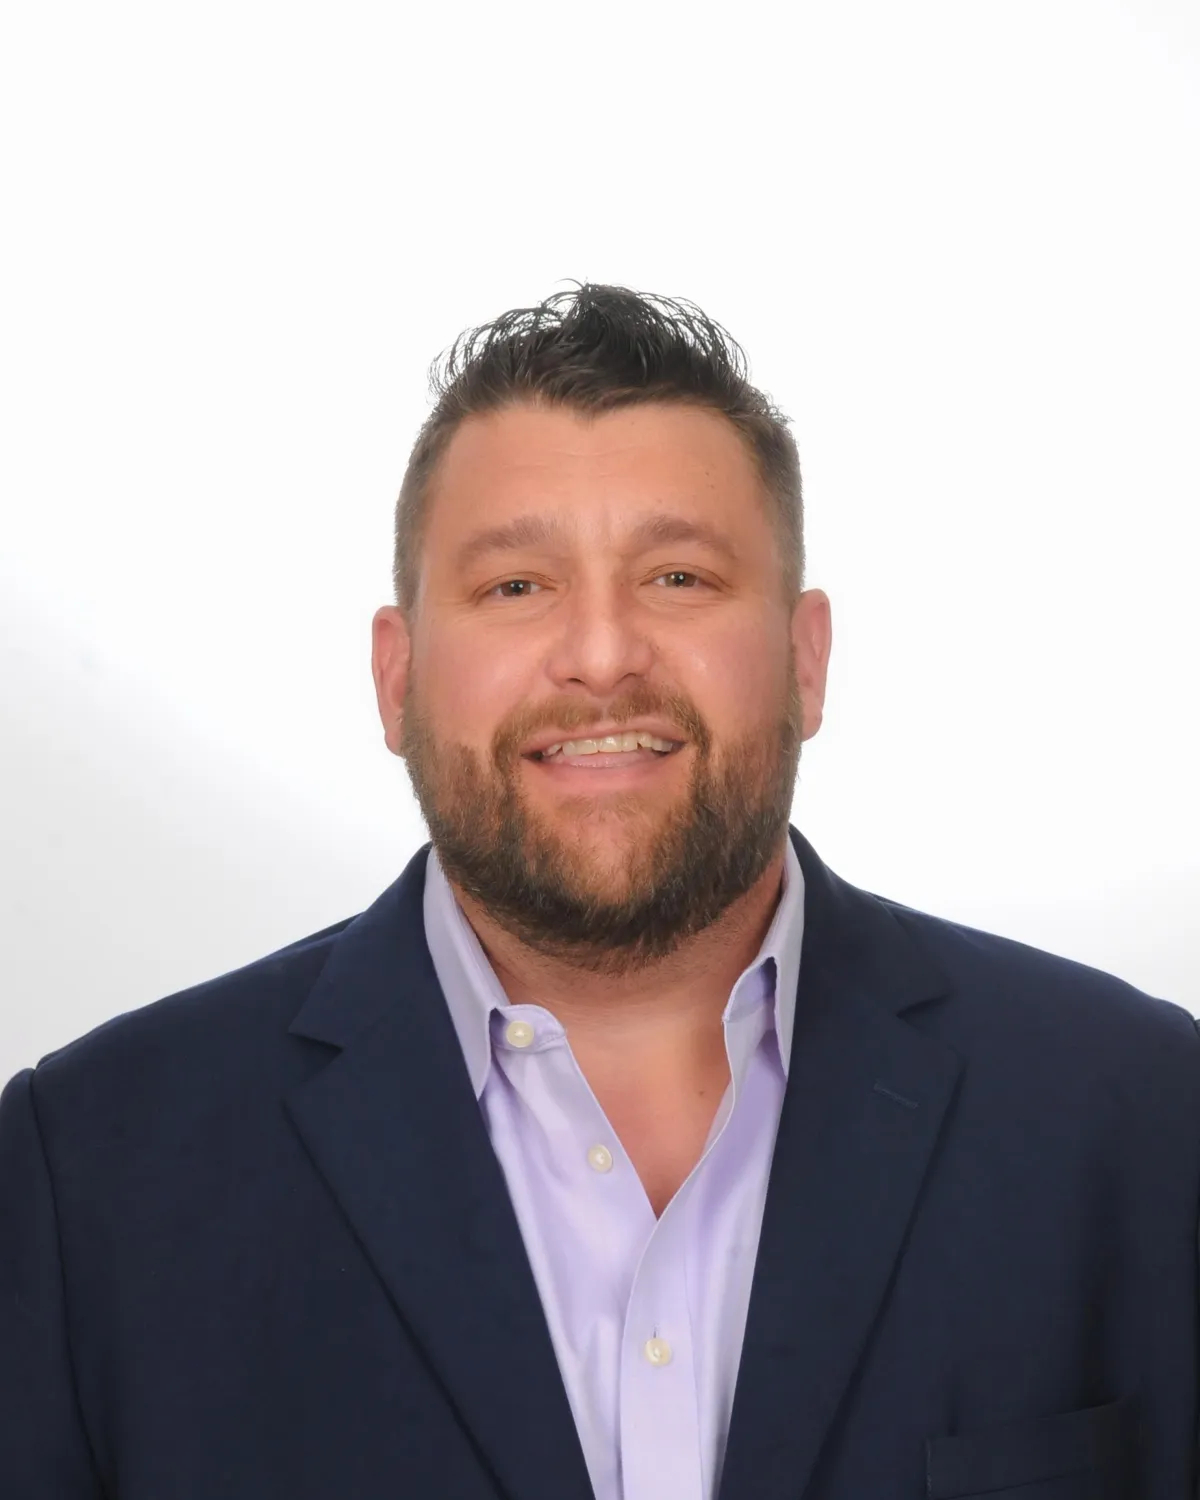
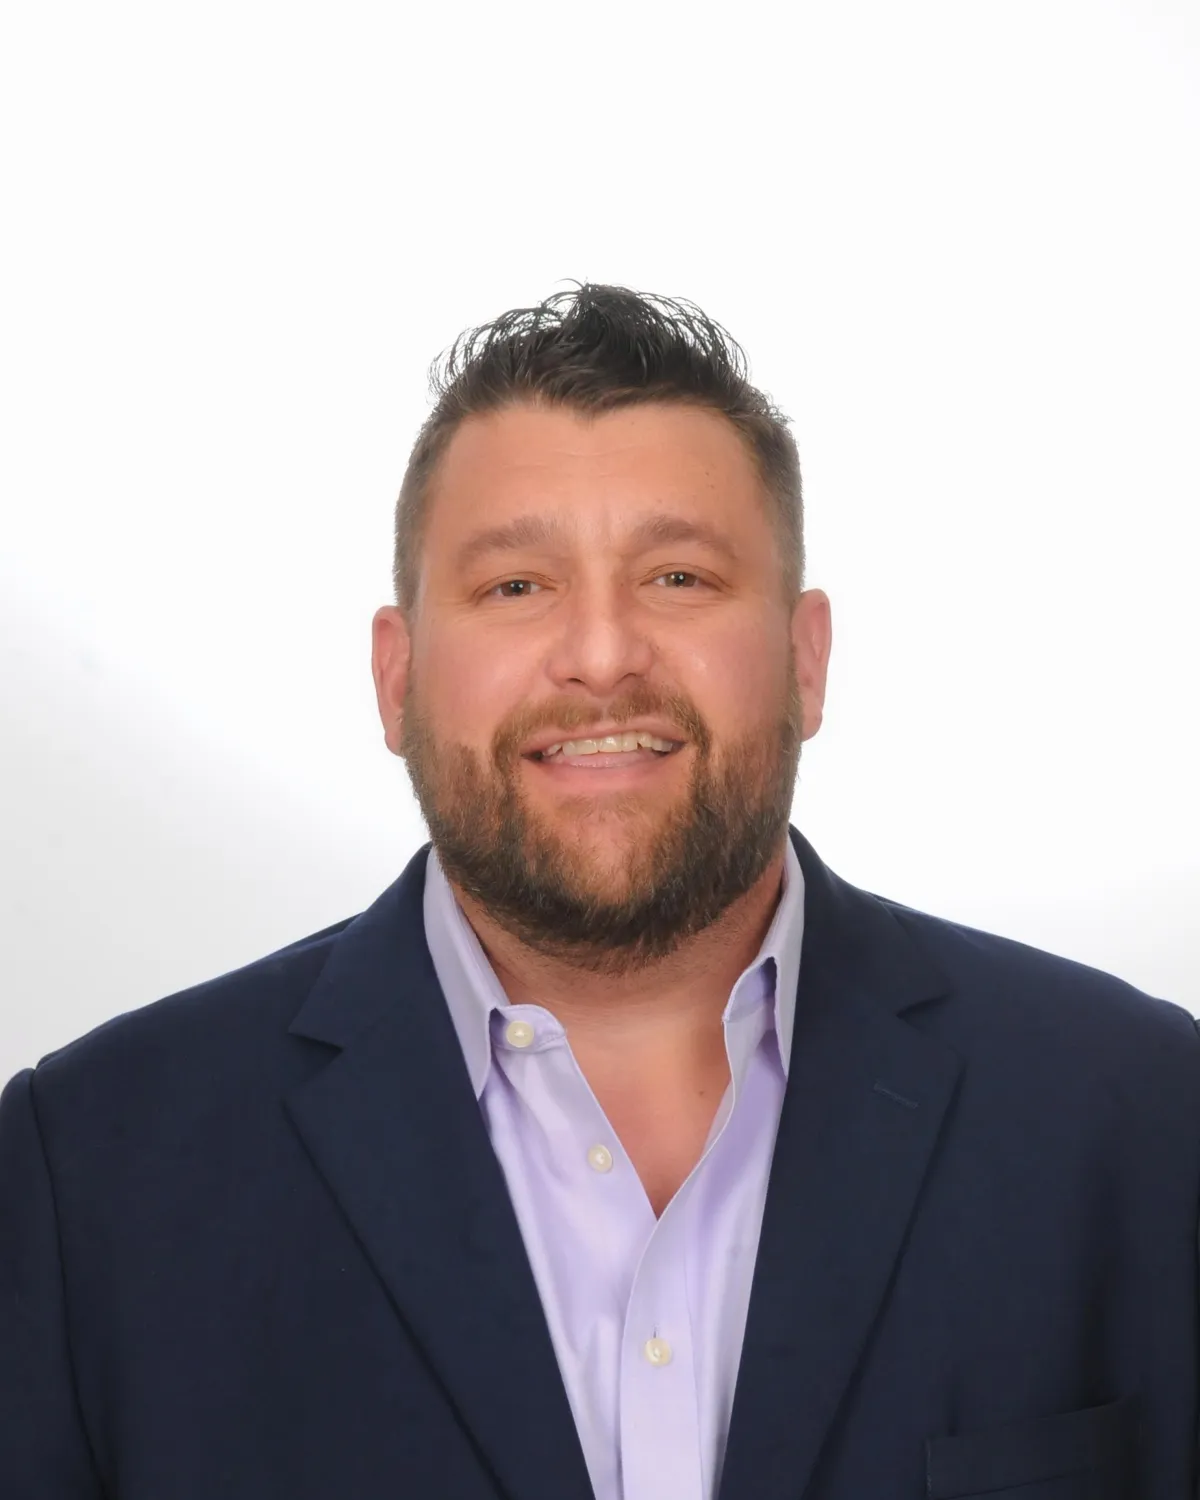
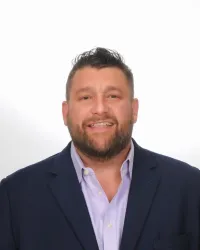
Meet Bill Rapp
NMLS ID # NMLS # 228246
Bill Rapp, CCIM is a Houston-based Capital Advisor at Medallion Funds, specializing in commercial real estate finance and strategic lending solutions. With over two decades of experience across brokerage and capital markets, Bill has worked with leading firms including eXp Commercial, NEXA Mortgage, Viking Enterprise LLC, and Sun Realty Houston.
A graduate of Texas A&M University with a BBA in Finance, Bill brings a disciplined, underwriting-first approach to every deal. His expertise spans commercial and residential financing, including asset-based lending, FHA financing, reverse mortgages, REO properties, and investment strategies for both single-family and commercial assets.
Known for his focus on structure over rate, Bill helps investors, business owners, and developers navigate complex transactions with clarity, precision, and a long-term wealth-building mindset.
The Client Experience
Great experience purchasing our first home! Bill was easy to reach and always able to answer any questions or concerns.

Loan Programs Available
Blogs
The Top 5 Mortgage Mistakes to Avoid
Buying your first home can be both exciting and nerve-wracking at the same time. With so many things to consider and....
Mortgage Do and
Do not list
Mortgages can be tricky, and it's easy to make mistakes that can end up costing you dearly. That's why we've put together this list....
Tips On How To Improve Your Credit Score
Let's talk about some ways you can improve your credit score! Your credit score is actually a big deal, and it can affect...
🏢 Self-Storage Financing Explained: How Lenders Underwrite Storage Properties & Choose Loan Options 💰
🏢 Self-Storage Financing Explained: How Lenders Underwrite Storage Properties & Choose Loan Options 💰
🔑 Self-Storage Loans: What Investors Must Know About DSCR, Occupancy, Cash Flow & Financing Options 📈
____________________________________________________________________________
Self-Storage Financing: How Lenders Underwrite Storage Properties and What Loan Options Are Available
Self-storage facilities have become an established commercial real estate investment category, attracting individual investors, experienced operators, and institutional capital.
But securing self-storage financing is not quite the same as obtaining a traditional commercial real estate loan for an office building, retail center, or multifamily property.
Self-storage lenders evaluate the property's cash flow, physical and economic occupancy, rental rates, operating expenses, competitive positioning, and the borrower's operating experience. Understanding these underwriting factors can make a significant difference when acquiring, refinancing, expanding, or developing a storage facility.
Whether you're purchasing your first storage facility or expanding an existing portfolio, here's what you need to know about self-storage loans, underwriting requirements, and commercial financing options.
Why Self-Storage Financing Is Different
Self-storage is a specialized commercial property type with characteristics that influence lender underwriting.
Unlike conventional commercial buildings with multiyear tenant leases, most storage facilities rent units under relatively short-term, often month-to-month agreements.
That creates both opportunities and risks.
Operators can adjust rental rates as market conditions change, but tenants can also vacate with relatively little notice.
Lenders consequently focus on several factors:
·Historical and stabilized net operating income (NOI)
·Physical occupancy versus economic occupancy
·Rental rates and competitive supply
·Debt service coverage ratio (DSCR)
·Loan-to-value ratio (LTV)
·Property management and operating experience
·Facility age, condition, and amenities
·Market demand and demographic trends
The central question is straightforward: Can this storage facility generate enough sustainable cash flow to support its proposed debt?
1. How Lenders Evaluate Self-Storage Occupancy
Occupancy is one of the most important underwriting considerations.
However, lenders distinguish between two different occupancy measurements.
Physical Occupancy
Physical occupancy measures the percentage of rentable space currently occupied.
For example, suppose a storage facility contains 500 units, of which 425 are occupied.
Physical occupancy would be:
425 ÷ 500 = 85%
Some lenders prefer square-footage occupancy rather than unit-count occupancy, particularly when facilities have different unit sizes.
Economic Occupancy
Economic occupancy measures actual rental revenue relative to the facility's potential rental revenue, generally after accounting for discounts, concessions, and collection losses.
Consider a facility with:
·Gross potential rental revenue: $600,000 annually
·Actual collected rental revenue: $480,000 annually
Economic occupancy would be:
$480,000 ÷ $600,000 = 80%
A facility can report strong physical occupancy while producing weaker economic occupancy because of discounts, delinquent accounts, or rental rates below market.
Why this matters: Lenders want evidence that occupied units are producing collectible revenue, not merely that units are rented.
2. Net Operating Income Drives Self-Storage Loan Sizing
For most income-producing self-storage properties, net operating income is a critical component of underwriting.
NOI generally equals operating revenue minus ordinary property operating expenses, before debt service, income taxes, depreciation, and capital expenditures.
Typical self-storage revenue sources include:
·Storage unit rental income
·Climate-controlled unit premiums
·Parking and vehicle storage
·Tenant protection program income, where applicable
·Administrative fees
·Merchandise and ancillary revenue
Operating expenses may include property taxes, insurance, utilities, payroll, maintenance, marketing, management, security, and repairs.
Example: Calculating Self-Storage NOI
Financial Item | Annual Amount |
Gross potential revenue | $750,000 |
Vacancy, concessions, and collection losses | ($112,500) |
Effective gross income | $637,500 |
Operating expenses | ($255,000) |
Net operating income | $382,500 |
In this example, the facility generates $382,500 in annual NOI.
A lender may adjust this figure for normalized property taxes, insurance, management fees, recurring expenses, and nonrecurring items.
Importantly, lenders may underwrite a lower NOI than the seller advertises.
Investor takeaway: Always analyze the lender's likely underwritten NOI rather than relying exclusively on the seller's pro forma.
3. Understanding DSCR for Self-Storage Loans
The debt service coverage ratio (DSCR) measures a property's ability to pay its mortgage obligations from operating income.
The formula is:
DSCR = Net Operating Income ÷ Annual Debt Service
Suppose a storage facility generates $382,500 in annual NOI and has projected annual mortgage payments of $300,000.
DSCR = $382,500 ÷ $300,000 = 1.275x
That means the property generates approximately $1.28 in NOI for every $1.00 of scheduled annual debt service.
Many commercial lenders evaluate minimum DSCR thresholds around 1.20x–1.35x, although requirements vary substantially by lender, program, leverage, and property risk.
Why DSCR Matters
A stronger DSCR can indicate greater capacity to withstand vacancies, expense increases, or weaker rental collections.
Conversely, a property with thin debt coverage may require:
·A larger down payment
·A smaller loan
·A lower purchase price
·Additional reserves
·Different loan structures
Lenders may also stress-test cash flow using higher interest rates or more conservative income and expense assumptions.
4. Loan-to-Value Ratios and Down Payment Requirements
Loan-to-value ratio measures the proposed loan relative to the property's appraised value.
LTV = Loan Amount ÷ Appraised Value
For illustration, consider a storage facility with an appraised value of $4 million.
LTV | Loan Amount | Equity Required |
60% | $2,400,000 | $1,600,000 |
65% | $2,600,000 | $1,400,000 |
70% | $2,800,000 | $1,200,000 |
75% | $3,000,000 | $1,000,000 |
These are mathematical examples, not guaranteed lending offers.
The actual loan amount may be limited by DSCR, debt yield, borrower qualifications, lender policy, or the lower of purchase price and appraised value.
Some lenders may offer higher leverage for qualifying transactions, while others apply conservative limits to smaller, rural, transitional, or inexperienced-operator deals.
Borrowers should also budget for closing costs, lender fees, reserves, and immediate capital improvements.
5. Debt Yield: Another Important Underwriting Metric
Some self-storage lenders, particularly debt funds and institutional capital providers, evaluate debt yield.
Debt yield measures property NOI relative to the outstanding loan amount.
Debt Yield = NOI ÷ Loan Amount
Suppose a facility generates $382,500 in NOI and the borrower requests $3 million.
Debt yield = $382,500 ÷ $3,000,000 = 12.75%
Unlike DSCR, debt yield does not depend directly on the interest rate or amortization schedule.
Lenders use it as another way to evaluate income relative to their exposure.
Debt yield requirements differ significantly among financing programs, so borrowers should avoid assuming that one benchmark applies to every lender.
6. What Loan Options Are Available for Self-Storage Properties?
There is no single financing solution for every storage investment.
Different commercial lenders specialize in different transaction sizes, property conditions, borrower profiles, and business plans.
Conventional Bank and Credit Union Loans
Traditional banks and credit unions may finance stabilized storage facilities with demonstrated cash flow.
Potential advantages include competitive pricing and established banking relationships.
However, lenders may require substantial documentation, recourse guarantees, deposit relationships, or more conservative leverage.
SBA 7(a) and SBA 504 Loans
Certain self-storage projects may qualify for SBA financing when the applicant is an eligible operating business and satisfies applicable program rules.
This distinction is especially important because passive investment real estate is generally ineligible for SBA financing.
The SBA 7(a) program may accommodate eligible business acquisitions, real estate, equipment, and certain working-capital needs.
The SBA 504 program generally focuses on eligible long-term fixed assets, such as owner-occupied real estate and qualifying improvements.
Eligibility depends on the operating structure, actual business activity, occupancy and use requirements, and current SBA rules. A self-storage facility is not automatically eligible simply because it operates as a business.
CMBS Loans
Commercial mortgage-backed securities (CMBS) financing may be appropriate for larger, stabilized self-storage properties.
Potential characteristics include longer-term fixed-rate structures and nonrecourse financing, subject to customary carve-outs.
Borrowers should carefully review defeasance, yield maintenance, cash management, servicing provisions, and prepayment restrictions.
Debt Fund and Bridge Loans
Bridge financing can be useful for transitional properties that do not yet meet permanent-loan requirements.
Examples include:
·Recently acquired facilities requiring improvements
·Properties undergoing management changes
·Facilities with below-market occupancy
·Expansion projects
·Lease-up or value-add business plans
Bridge loans often involve higher borrowing costs, shorter maturities, and greater refinancing or exit risk.
Self-Storage Construction Loans
Construction lenders focus on both the proposed project and its ability to achieve stabilized occupancy.
They typically evaluate development costs, site conditions, permits, construction schedules, sponsorship, feasibility studies, competing supply, and lease-up projections.
Borrowers should expect to provide a detailed development budget and a credible path to permanent financing.
Life Insurance Company and Other Institutional Loans
Certain stabilized, larger-scale self-storage properties may attract life insurance company lenders or other institutional financing sources.
These programs often emphasize asset quality, market fundamentals, experienced sponsorship, and durable cash flow.
7. What Makes a Self-Storage Property More Financeable?
Lenders look beyond current income.
They also assess the facility's competitive position and the sustainability of future performance.
Location and Market Demand
Important considerations may include population growth, household density, renter activity, housing turnover, household income, visibility, access, and local competition.
Competitive Supply
A facility operating at 90% occupancy today may still face future challenges if multiple competing developments are scheduled to open nearby.
Lenders may examine planned construction, competing facilities, advertised rents, and local absorption.
Climate-Controlled Versus Non-Climate-Controlled Units
Climate-controlled units can command different rents and attract different customer segments, but they also create additional utility, maintenance, and equipment replacement costs.
Property Management
Experienced operators often have stronger systems for revenue management, collections, marketing, security, and expense control.
Some lenders place substantial weight on sponsorship and management experience.
Capital Expenditures
Deferred maintenance, roof repairs, security upgrades, paving, HVAC replacements, and other improvements can affect the property's financing requirements and available cash flow.
8. Documents Needed for Self-Storage Financing
Borrowers can often improve the financing process by assembling a complete loan package before approaching lenders.
Typical documents include:
1.Current rent roll or unit-level occupancy report
2.Trailing 12-month operating statement (T-12)
3.Two to three years of historical financial statements, when available
4.Monthly physical and economic occupancy history
5.Current rental rate schedule and concession information
6.Property details, unit mix, site plan, and photographs
7.Purchase agreement or refinance details
8.Capital improvement budget and business plan
9.Borrower financial statements and liquidity verification
10.Ownership structure and relevant operating experience
Construction and transitional transactions may require additional feasibility, engineering, environmental, and development documentation.
A complete package helps lenders evaluate the transaction efficiently and identify financing constraints early.
9. Real-World Example: Financing a $4 Million Self-Storage Acquisition
Let's examine a hypothetical acquisition.
Property Overview
·Purchase price: $4,000,000
·Units: 500
·Physical occupancy: 85%
·Annual NOI: $382,500
·Requested financing: $2,800,000
·Proposed LTV: 70%
·Borrower equity toward purchase: $1,200,000
Assume the proposed financing produces $300,000 in annual debt service.
DSCR: $382,500 ÷ $300,000 = 1.275x
Debt yield: $382,500 ÷ $2,800,000 = 13.66%
On the surface, the property may be a reasonable candidate for conventional commercial financing.
However, suppose the lender discovers that insurance, property taxes, and management expenses will increase by $50,000 annually after acquisition.
Underwritten NOI would decline to $332,500.
The revised DSCR would be:
$332,500 ÷ $300,000 = 1.11x
That could materially change the lender's willingness to approve the requested loan amount.
The borrower might need additional equity, a lower purchase price, or a different financing structure.
This example demonstrates why self-storage financing is driven by underwritten cash flow, not simply purchase price or advertised occupancy.
10. Why Compare Multiple Self-Storage Lenders?
Different lenders have different appetites for storage properties.
One lender may favor stabilized suburban facilities, while another specializes in smaller assets, value-add acquisitions, construction, or experienced portfolio operators.
That is where a commercial financing marketplace can be valuable.
Through the CommLoan Empower Program, I help borrowers evaluate commercial financing opportunities using CommLoan's CUPID™ platform and access to a network of more than 700 lenders.
Instead of assuming one local bank is the only financing source, investors can explore programs aligned with the property's income, location, occupancy, and investment strategy.
Of course, lender participation, eligibility, terms, and approval depend on the transaction and underwriting.
Final Thoughts: Structure the Financing Around the Investment
Self-storage can be an attractive commercial real estate investment, but successful financing requires careful underwriting.
Before making an offer or refinancing an existing facility, understand the property's NOI, economic occupancy, DSCR, debt yield, competitive supply, and capital requirements.
Most importantly, compare loan structures based on the full economics of the investment—not simply the quoted interest rate.
Looking to acquire, refinance, expand, or develop a self-storage property?
I'm Bill Rapp, CCIM, with the CommLoan Empower Program. I help commercial real estate investors evaluate financing alternatives and identify lenders that fit their investment objectives.
Top of Form
Bottom of Form
Bill Rapp, CCIM
Director | CommLoan
📞 281-222-0433
📧 [email protected]
🌐 https://billrapp.commloan.com/
🌐 https://HoustonCommercialMortgage.com/
Commercial Real Estate Financing Nationwide
https://billrapp.commloan.com/
https://author.billrapponline.com/
https://www.amazon.com/dp/B0F32Z5BH2
https://veed.cello.so/FOmzTty6oi9
https://buymeacoffee.com/vikingente3
https://creplaybookseries.billrapponline.com
https://creplaybook.billrapponline.com/
©Bill Rapp, CCIM - Director - CommLoan
10 Tips for First-Time Homebuyers
Buying your first home can be both exciting and nerve-wracking at the same time. With so many things to consider and....
How To Choose the Right Lender for You
Lorem Ipsum is simply dummy text of the printing and typesetting industry. Lorem Ipsum has been the industry's standard dummy
Refinancing youe loan and when to do it
Lorem Ipsum is simply dummy text of the printing and typesetting industry. Lorem Ipsum has been the industry's standard dummy
Copyright ©2021 | Mortgage Viking Team
Licensed to Do Business | NMLS # 228246
This is not an offer to enter into an agreement. Not all customers will qualify. Information, rates and programs are subject to change without notice. All products are subject to credit and property approval. Other restrictions and limitations may apply. Copyright © 2021 | Medallion Funds
Corporate | NMLS ID NMLS # 1825831
Corporate Address : 2651 N. Green Valley Pkwy STE. 101 Henderson, NV 89014
Corporate NMLS NMLS # 1825831 | Company Website: https://medallionfunds.com/bill-rapp/
Copyright ©2021 | Mortgage Viking Team Licensed to Do Business | NMLS # 228246
This is not an offer to enter into an agreement. Not all customers will qualify. Information, rates and programs are subject to change without notice. All products are subject to credit and property approval. Other restrictions and limitations may apply
Corporate | NMLS ID NMLS # 1825831
Corporate Address : 2651 N. Green Valley Pkwy STE. 101 Henderson, NV 89014 https://medallionfunds.com/bill-rapp/
Facebook
Instagram
X
LinkedIn
Youtube
TikTok