Low Rates.
Our rates are low, our application is quick and easy! We can get you clear to close in as little as 10 days!
Trusted By Agents With
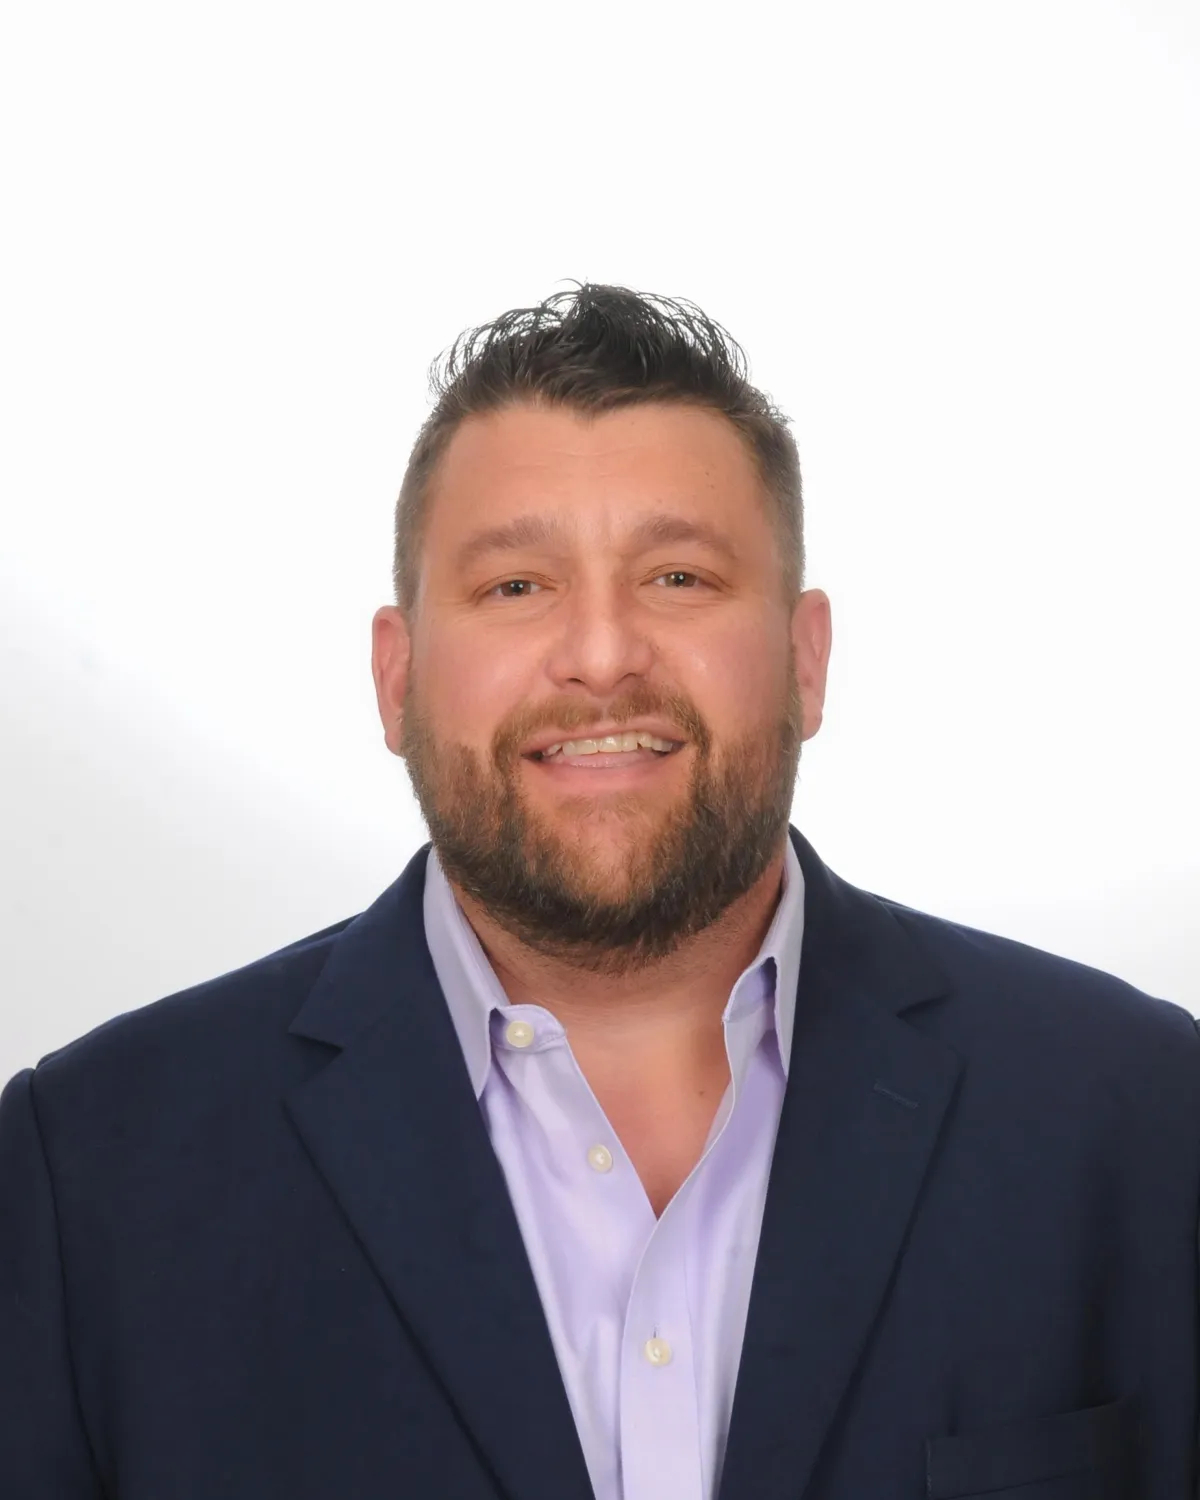
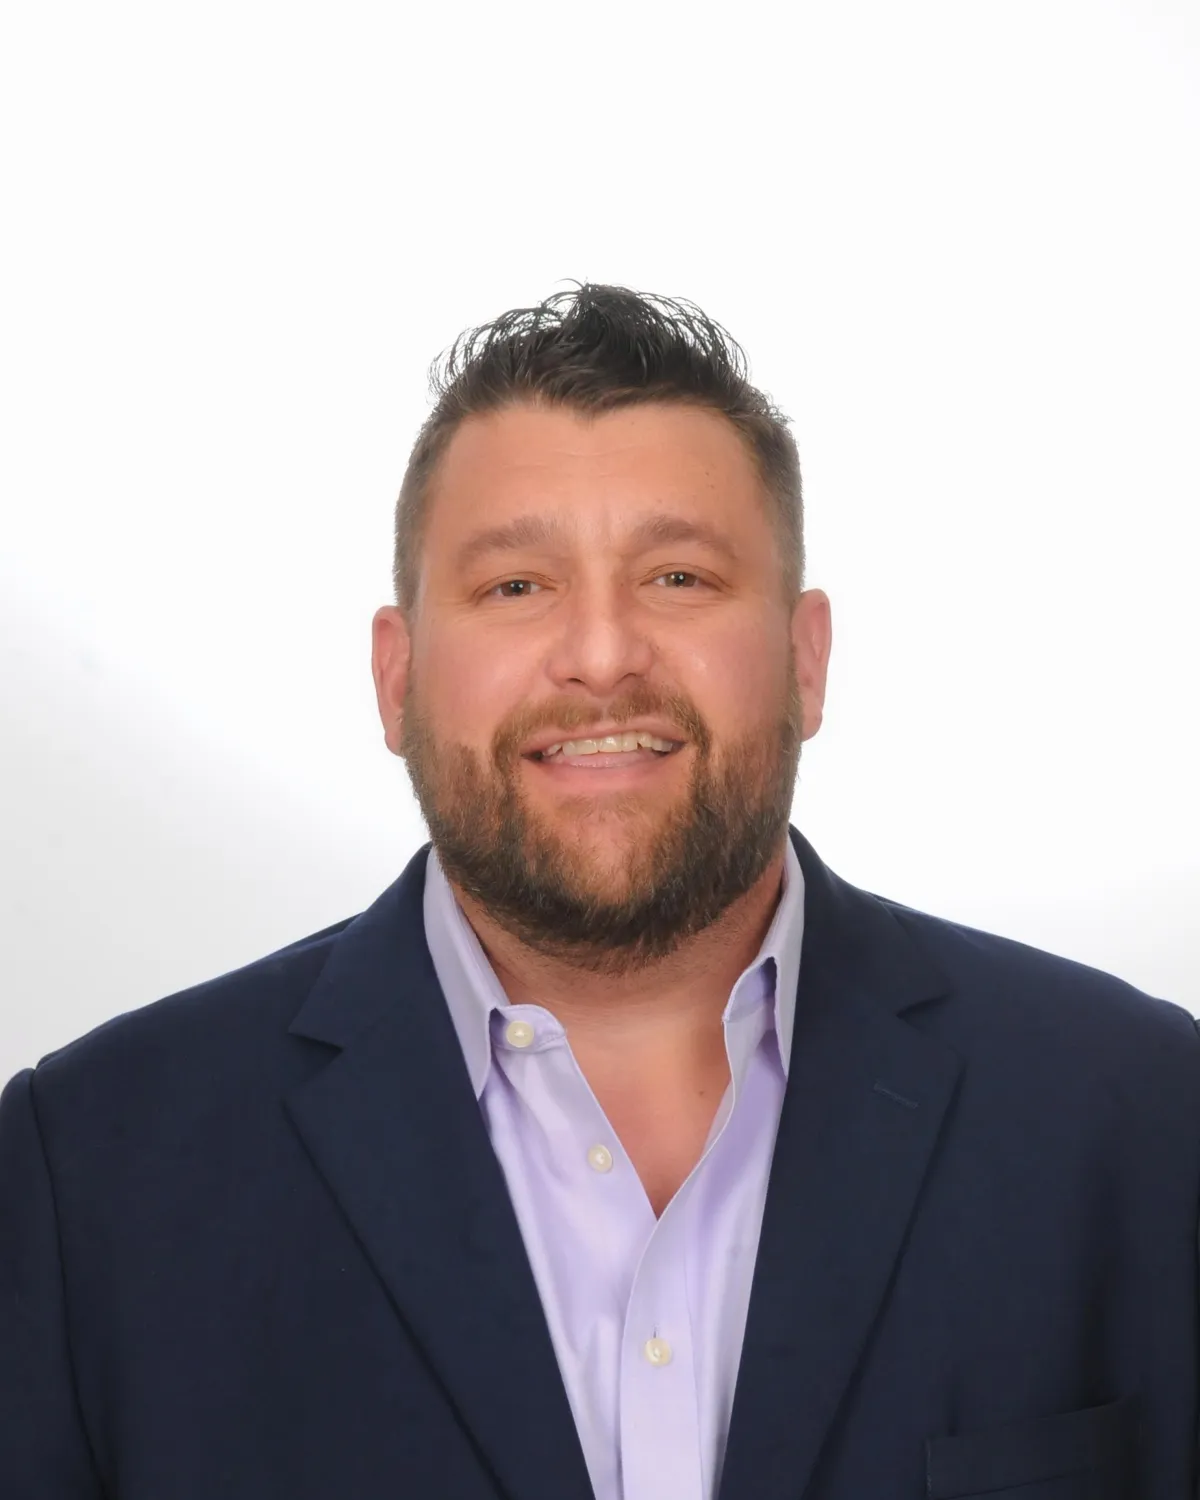
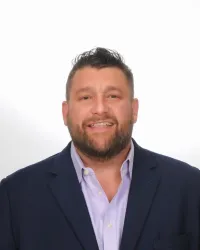
Meet Bill Rapp
NMLS ID # NMLS # 228246
Bill Rapp, CCIM is a Houston-based Capital Advisor at Medallion Funds, specializing in commercial real estate finance and strategic lending solutions. With over two decades of experience across brokerage and capital markets, Bill has worked with leading firms including eXp Commercial, NEXA Mortgage, Viking Enterprise LLC, and Sun Realty Houston.
A graduate of Texas A&M University with a BBA in Finance, Bill brings a disciplined, underwriting-first approach to every deal. His expertise spans commercial and residential financing, including asset-based lending, FHA financing, reverse mortgages, REO properties, and investment strategies for both single-family and commercial assets.
Known for his focus on structure over rate, Bill helps investors, business owners, and developers navigate complex transactions with clarity, precision, and a long-term wealth-building mindset.
The Client Experience
Great experience purchasing our first home! Bill was easy to reach and always able to answer any questions or concerns.

Loan Programs Available


Blogs
The Top 5 Mortgage Mistakes to Avoid
Buying your first home can be both exciting and nerve-wracking at the same time. With so many things to consider and....
Mortgage Do and
Do not list
Mortgages can be tricky, and it's easy to make mistakes that can end up costing you dearly. That's why we've put together this list....
Tips On How To Improve Your Credit Score
Let's talk about some ways you can improve your credit score! Your credit score is actually a big deal, and it can affect...
🏬 Retail Property Loans: Investor Financing Guide 💰
🏬 Retail Property Loans: Investor Financing Guide 💰
💵 Retail Real Estate Financing: Loan Options 🏢
________________________________________________________________________________
Retail Property Loans: What Investors Need to Know
Retail real estate can offer investors attractive income opportunities, long-term tenant relationships, and portfolio diversification. However, financing a retail property requires more than finding a lender willing to offer a commercial mortgage.
Whether you're purchasing a neighborhood shopping center, acquiring a single-tenant net-leased property, refinancing a retail strip center, or financing an owner-occupied storefront, understanding retail property loans can help you make more informed investment decisions.
Commercial lenders evaluate retail properties differently based on tenant quality, lease structures, cash flow, occupancy, location, and property condition.
In this guide, we'll explore retail real estate financing options, underwriting requirements, loan-to-value ratios, debt service coverage, and strategies for securing competitive financing.
What Is a Retail Property Loan?
A retail property loan is a commercial real estate mortgage used to purchase, refinance, renovate, or develop property intended for retail business operations.
Common retail property types include:
Single-tenant retail buildings: Freestanding properties occupied by one business, such as a pharmacy, restaurant, or national retailer.
Neighborhood shopping centers: Multi-tenant retail centers serving surrounding residential communities.
Strip centers: Smaller retail buildings featuring multiple storefronts.
Grocery-anchored centers: Shopping centers anchored by supermarkets or other high-traffic retailers.
Retail pad sites: Freestanding properties within larger retail developments.
Owner-occupied retail properties: Buildings purchased by business owners to operate their own businesses.
Each category carries different risks and underwriting considerations.
For example, a shopping center with ten diversified tenants may present a different risk profile than a single-tenant building dependent on one operator.
Understanding those differences is essential when selecting a financing strategy.
1. Retail Property Financing Options
Commercial real estate investors have several potential financing solutions.
Conventional Bank Loans
Traditional banks remain an important source of retail property financing.
These loans may offer competitive interest rates and flexible structures for established borrowers purchasing stabilized properties.
Typical characteristics include:
Loan-to-value ratios often around 65%–75%.
Amortization periods commonly between 20 and 25 years.
Loan terms frequently ranging from 3 to 10 years.
Personal guarantees often required.
Strong emphasis on borrower financial strength and property cash flow.
Some lenders may offer different terms depending on sponsorship, tenant quality, deposit relationships, and market conditions.
Best suited for: Stabilized shopping centers, established retail investors, and owner-users with strong financial profiles.
Commercial Mortgage-Backed Securities (CMBS) Loans
CMBS financing may be appropriate for larger stabilized retail investments.
These loans are typically structured around property-level cash flow and institutional underwriting standards.
Potential advantages include longer fixed-rate terms, nonrecourse structures subject to customary carve-outs, and financing for larger investment properties.
However, investors should understand that CMBS loans may include substantial prepayment restrictions, defeasance or yield maintenance, cash management requirements, and more rigid servicing procedures.
Best suited for: Larger stabilized retail properties with predictable income and experienced sponsorship.
Debt Service Coverage Ratio (DSCR) Loans
DSCR-focused commercial mortgage programs emphasize whether a property's income supports its debt obligations.
The basic formula is:
DSCR = Net Operating Income ÷ Annual Debt Service
For example, if a retail center generates $180,000 in annual net operating income and has $135,000 in annual mortgage payments:
DSCR = $180,000 ÷ $135,000 = 1.33
A 1.33 DSCR means the property generates approximately $1.33 in net operating income for every $1.00 of annual debt service.
Many lenders target DSCR levels around 1.20–1.35 or higher for stabilized retail, although actual requirements depend on the program and property.
Best suited for: Income-producing retail investments where cash flow is a central underwriting consideration.
SBA 7(a) and SBA 504 Loans
Small business owners purchasing retail real estate for their own operations may qualify for SBA-backed financing.
Two major programs are:
SBA 7(a)
Can finance eligible real estate acquisitions and certain related business needs.
May offer terms up to 25 years for qualifying real estate.
Often permits lower equity contributions than conventional commercial mortgages, subject to eligibility and underwriting.
Has a standard maximum loan amount of $5 million.
SBA 504
Designed primarily for eligible fixed-asset financing.
Often uses a structure involving a bank lender, a Certified Development Company, and borrower equity.
A typical structure may involve 50% bank financing, 40% CDC financing, and 10% borrower equity, with higher contributions in certain situations.
The CDC/SBA portion has separate eligibility and project limits.
Importantly, SBA financing generally is not intended for passive investment in rental retail property. The operating business must meet applicable owner-occupancy and eligibility requirements.
Best suited for: Qualified retailers, restaurateurs, service businesses, and other operating companies purchasing their own commercial facilities.
Bridge Loans
Bridge financing can help investors acquire or reposition properties that do not currently meet conventional underwriting standards.
Examples include:
Retail centers with significant vacancy.
Properties requiring major renovations.
Shopping centers undergoing tenant replacement.
Acquisitions requiring accelerated closing.
Assets awaiting stabilization before permanent refinancing.
Bridge loans often carry higher interest rates, shorter terms, and greater refinancing risk than permanent commercial mortgages.
The most important consideration is the exit strategy.
Before accepting bridge financing, investors should determine whether the property can realistically qualify for permanent financing or be sold before the loan matures.
2. How Lenders Underwrite Retail Properties
Retail underwriting involves more than the borrower's credit score.
Lenders analyze the property as an income-producing business asset.
Net Operating Income
Net operating income, or NOI, represents property revenue after ordinary operating expenses but before debt service, income taxes, depreciation, and amortization.
NOI = Effective Gross Income − Operating Expenses
For retail properties, lenders review rental income, reimbursements, vacancies, property taxes, insurance, management fees, repairs, and reserves.
A property with strong rental income can still struggle to qualify if operating expenses are unusually high.
Tenant Credit Quality
Tenant financial strength can materially influence loan terms.
Lenders may distinguish between:
National investment-grade retailers.
Established regional chains.
Local independent businesses.
Franchise operators.
Newly established businesses.
A recognizable brand name does not automatically mean the lease is guaranteed by a financially strong corporate entity.
For example, a restaurant operating under a national franchise brand may be leased to an individual franchisee rather than the franchisor.
Lenders evaluate the actual lease obligor and any guarantor.
Lease Structure
Retail properties frequently use one of several lease structures.
Triple Net (NNN): Tenants reimburse or directly pay certain property expenses, often including taxes, insurance, and common-area maintenance.
Modified Gross: Landlords and tenants divide operating expenses according to the lease.
Gross Lease: The landlord generally pays more operating expenses from the stated rental income.
The exact contractual terms matter more than the lease label.
Investors should evaluate expense reimbursements, caps, exclusions, maintenance responsibilities, and potential collection shortfalls.
Lease Expiration and Rollover
A property's weighted average lease term, or WALT, helps lenders evaluate future rental income stability.
Consider two shopping centers with identical current NOI.
One has tenants committed for another eight years.
The other has half its tenants expiring within eighteen months.
Even with identical current income, the second property may present greater rollover and refinancing risk.
Lenders may require additional reserves or lower leverage when significant lease expirations are approaching.
Location and Retail Demand
Location remains a major component of retail financing.
Lenders consider:
Population and household income.
Traffic counts and accessibility.
Visibility and signage.
Parking availability.
Surrounding residential development.
Competing retail inventory.
Tenant demand and market rents.
Retail centers in established or expanding trade areas may benefit from stronger leasing prospects, but location alone does not guarantee financing approval.
3. How Much Can You Borrow on Retail Real Estate?
Loan proceeds generally depend on several constraints:
1.Loan-to-value ratio.
2.Debt service coverage.
3.Borrower financial strength.
4.Property condition and tenant concentration.
5.Loan program and lender guidelines.
Loan-to-Value Ratio
Loan-to-value measures the loan amount relative to the property's appraised value.
LTV = Loan Amount ÷ Property Value
Suppose an investor purchases a retail strip center for $2 million.
At 70% LTV:
Maximum loan based on value = $1,400,000
The investor would need approximately $600,000 in equity before closing costs, reserves, and other transaction expenses.
However, qualifying for 70% LTV does not guarantee a $1.4 million loan.
The property's cash flow must also support the proposed debt.
DSCR Can Reduce Loan Proceeds
Suppose the lender requires a minimum DSCR of 1.25.
If the property's NOI is $150,000:
Maximum annual debt service = $150,000 ÷ 1.25 = $120,000
The lender must structure the loan so annual principal and interest payments do not exceed that amount, subject to its underwriting methodology.
The resulting loan amount may be lower than the amount suggested by the property's appraised value.
The practical lesson: Your maximum commercial mortgage is often determined by the most restrictive underwriting constraint.
4. Retail Property Financing Example
Let's evaluate a hypothetical neighborhood shopping center.
Property Metric | Amount |
Purchase price | $3,000,000 |
Annual gross rental revenue | $330,000 |
Vacancy and collection allowance | $15,000 |
Operating expenses | $105,000 |
Net operating income | $210,000 |
Proposed loan amount | $2,100,000 |
Loan-to-value ratio | 70% |
Illustrative interest rate | 7.00% |
Amortization | 25 years |
Annual debt service | Approximately $178,100 |
Debt service coverage ratio | Approximately 1.18 |
Illustrative assumptions only; not a current rate quote or financing offer.
At a 1.18 DSCR, this property may fall below a lender's minimum coverage requirement.
If the lender requires a 1.25 DSCR, the maximum annual debt service would be:
$210,000 ÷ 1.25 = $168,000
At the same illustrative interest rate and amortization, the DSCR-constrained loan amount would be approximately $1.98 million.
That is roughly $120,000 less than the initial 70% LTV request.
This example illustrates why investors should evaluate cash flow before relying on a lender's advertised maximum leverage.
5. Common Retail Financing Challenges
High Tenant Concentration
A single tenant accounting for 60% of a shopping center's income creates greater concentration risk than a more diversified rent roll.
Lenders may respond by reducing leverage or requiring stronger reserves.
Short Remaining Lease Terms
A tenant approaching expiration may create uncertainty about future occupancy and rental rates.
Lease renewals or extensions can sometimes improve financing options.
Deferred Maintenance
Roof replacements, parking lot repairs, HVAC systems, and building renovations can affect lender confidence.
A property condition assessment may identify required repairs and capital reserves.
Vacant Retail Space
Vacancy reduces current income and may increase leasing costs.
Investors should account for tenant improvement allowances, leasing commissions, downtime, and free rent when evaluating a lease-up strategy.
Environmental Concerns
Certain retail uses, including dry cleaners, automotive services, and former fuel-related operations, may require additional environmental due diligence.
Lenders commonly require an appropriate environmental assessment before closing.
6. Documents Needed for a Retail Property Loan
Preparing a complete financing package can reduce underwriting delays.
Typical lender requests include:
Current rent roll and tenant lease abstracts.
Copies of executed leases and amendments.
Trailing 12-month operating statements.
Year-to-date profit and loss statements.
Property tax and insurance information.
Purchase contract or current loan statement.
Borrower financial statements and liquidity verification.
Entity formation documents.
Property photographs and capital improvement history.
Business financials for owner-occupied transactions.
Depending on the lender, additional documents may include tenant financial statements, estoppel certificates, environmental reports, property condition assessments, and an appraisal.
A well-organized loan package can make it easier to compare lender proposals and identify potential underwriting concerns early.
7. How to Improve Your Retail Property Loan Terms
Investors can take several practical steps before applying for financing.
Improve occupancy and collections. Stable, documented income can support stronger underwriting.
Extend important tenant leases. Longer commitments from financially sound tenants may reduce rollover risk.
Document expense reimbursements. Accurate NNN reconciliations can help lenders verify sustainable NOI.
Maintain adequate liquidity. Post-closing reserves can improve borrower strength.
Prepare a realistic business plan. For transitional properties, show leasing assumptions, improvement budgets, and a credible refinance or sale strategy.
Compare multiple capital sources. Banks, credit unions, CMBS lenders, debt funds, and other commercial mortgage providers have different credit requirements.
The lowest advertised interest rate is not always the best financing option.
Loan term, amortization, prepayment provisions, guarantees, recourse, reserve requirements, and closing certainty should all factor into the decision.
8. Why Work With a Commercial Mortgage Broker?
Retail real estate financing is not one-size-fits-all.
A neighborhood strip center with local tenants may fit a community bank's lending criteria, while a larger stabilized shopping center may be better suited to institutional financing.
An owner-occupied retail business may qualify for SBA financing, while a vacant property requiring renovation may need a bridge loan.
Working with a commercial mortgage broker can help investors evaluate multiple financing structures rather than relying exclusively on one institution's lending guidelines.
Through the CommLoan Empower Program, I help commercial real estate investors and business owners navigate commercial mortgage financing options, evaluate lender requirements, and prepare transactions for underwriting.
My approach emphasizes matching the property, borrower, investment strategy, and anticipated exit with an appropriate capital source.
Frequently Asked Questions About Retail Property Loans
What is the typical down payment for a retail property loan?
Many conventional investment-property loans require approximately 25%–35% equity, although requirements vary. Qualified SBA owner-occupied transactions may permit lower contributions.
Can I finance a retail property with vacant units?
Yes, but significant vacancy may limit conventional financing options. Bridge financing or other transitional loan programs may be more appropriate.
Are retail property loans available for first-time investors?
Potentially. Lenders may place greater emphasis on borrower liquidity, experience, credit, outside income, property management, and property cash flow.
Can I refinance a retail shopping center?
Yes. Refinancing may be used to replace maturing debt, modify loan terms, or potentially access equity, subject to valuation and underwriting.
Do retail property loans require personal guarantees?
Many bank loans require guarantees. Certain institutional or securitized programs may offer nonrecourse financing subject to customary exceptions.
Can I use an SBA loan to buy a strip center?
Only when the transaction meets SBA eligibility requirements, including applicable operating-business occupancy rules. SBA programs generally cannot be used simply to acquire passive rental investment property.
Final Thoughts: Structure Your Retail Property Financing Before You Buy
Retail real estate can provide meaningful investment opportunities, but financing decisions directly affect cash flow, leverage, risk, and long-term returns.
Before purchasing or refinancing a retail property, evaluate the tenant roster, lease expirations, NOI, DSCR, capital expenditures, and available financing structures.
A successful transaction begins with understanding both the property and the lender's underwriting requirements.
Ready to explore retail property financing?
I'm Bill Rapp, CCIM, and through the CommLoan Empower Program, I work with commercial real estate investors and business owners seeking financing solutions for retail, industrial, office, multifamily, and other commercial properties.
Top of Form
Bottom of Form
Bill Rapp, CCIM
Director | CommLoan
📞 281-222-0433
📧 [email protected]
🌐 https://billrapp.commloan.com/
🌐 https://HoustonCommercialMortgage.com/
Commercial Real Estate Financing Nationwide
https://billrapp.commloan.com/
https://author.billrapponline.com/
https://www.amazon.com/dp/B0F32Z5BH2
https://veed.cello.so/FOmzTty6oi9
https://buymeacoffee.com/vikingente3
https://creplaybookseries.billrapponline.com
https://creplaybook.billrapponline.com/
©Bill Rapp, CCIM - Director - CommLoan
10 Tips for First-Time Homebuyers
Buying your first home can be both exciting and nerve-wracking at the same time. With so many things to consider and....
How To Choose the Right Lender for You
Lorem Ipsum is simply dummy text of the printing and typesetting industry. Lorem Ipsum has been the industry's standard dummy
Refinancing youe loan and when to do it
Lorem Ipsum is simply dummy text of the printing and typesetting industry. Lorem Ipsum has been the industry's standard dummy
Copyright ©2021 | Mortgage Viking Team
Licensed to Do Business | NMLS # 228246
This is not an offer to enter into an agreement. Not all customers will qualify. Information, rates and programs are subject to change without notice. All products are subject to credit and property approval. Other restrictions and limitations may apply. Copyright © 2021 | Medallion Funds
Corporate | NMLS ID NMLS # 1825831
Corporate Address : 2651 N. Green Valley Pkwy STE. 101 Henderson, NV 89014
Corporate NMLS NMLS # 1825831 | Company Website: https://medallionfunds.com/bill-rapp/
Copyright ©2021 | Mortgage Viking Team Licensed to Do Business | NMLS # 228246
This is not an offer to enter into an agreement. Not all customers will qualify. Information, rates and programs are subject to change without notice. All products are subject to credit and property approval. Other restrictions and limitations may apply
Corporate | NMLS ID NMLS # 1825831
Corporate Address : 2651 N. Green Valley Pkwy STE. 101 Henderson, NV 89014 https://medallionfunds.com/bill-rapp/
Facebook
Instagram
X
LinkedIn
Youtube
TikTok