Low Rates.
Our rates are low, our application is quick and easy! We can get you clear to close in as little as 10 days!
Trusted By Agents With
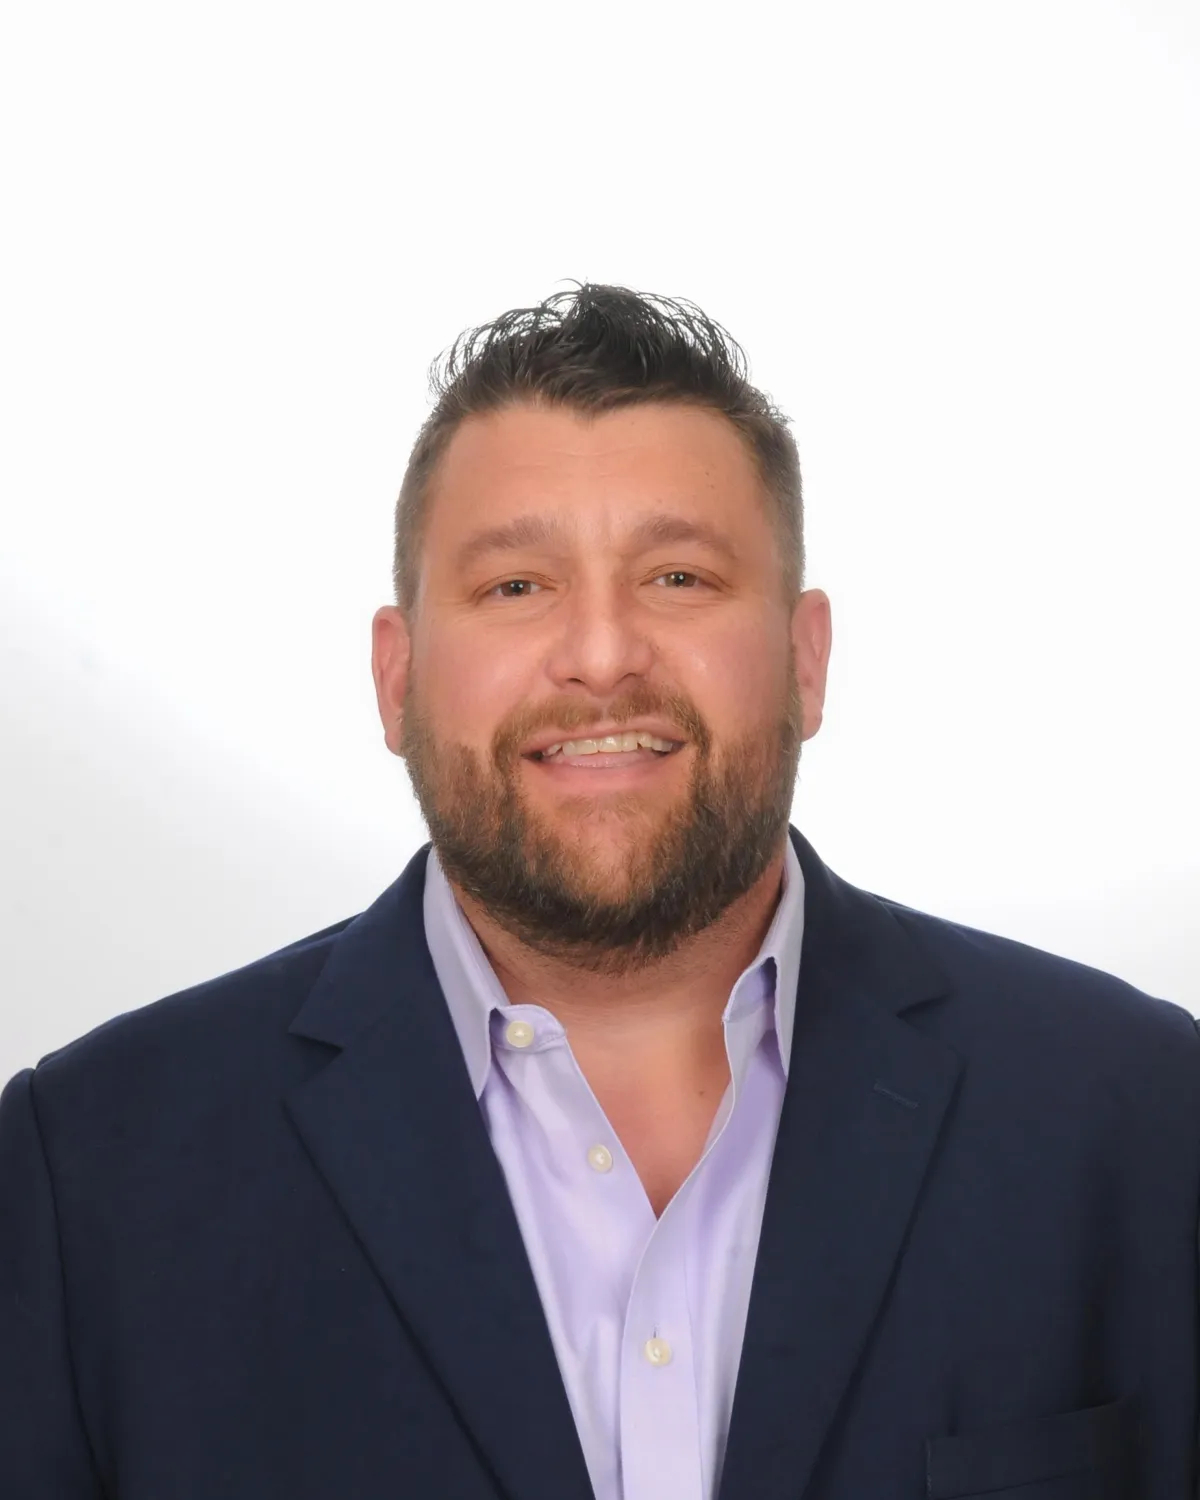
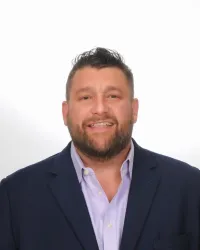
Meet Bill Rapp
NMLS ID # NMLS # 228246
Bill Rapp, CCIM is a Houston-based Capital Advisor at Medallion Funds, specializing in commercial real estate finance and strategic lending solutions. With over two decades of experience across brokerage and capital markets, Bill has worked with leading firms including eXp Commercial, NEXA Mortgage, Viking Enterprise LLC, and Sun Realty Houston.
A graduate of Texas A&M University with a BBA in Finance, Bill brings a disciplined, underwriting-first approach to every deal. His expertise spans commercial and residential financing, including asset-based lending, FHA financing, reverse mortgages, REO properties, and investment strategies for both single-family and commercial assets.
Known for his focus on structure over rate, Bill helps investors, business owners, and developers navigate complex transactions with clarity, precision, and a long-term wealth-building mindset.
The Client Experience
Great experience purchasing our first home! Bill was easy to reach and always able to answer any questions or concerns.

Loan Programs Available
Blogs
The Top 5 Mortgage Mistakes to Avoid
Buying your first home can be both exciting and nerve-wracking at the same time. With so many things to consider and....
Mortgage Do and
Do not list
Mortgages can be tricky, and it's easy to make mistakes that can end up costing you dearly. That's why we've put together this list....
Tips On How To Improve Your Credit Score
Let's talk about some ways you can improve your credit score! Your credit score is actually a big deal, and it can affect...
🏡 Local Mortgage Broker Near Me: How to Find the Best Mortgage Options in Katy & Houston 🔑
🏡 Local Mortgage Broker Near Me: How to Find the Best Mortgage Options in Katy & Houston 🔑
💰 Searching for a Mortgage Broker Near Me? 7 Reasons to Choose a Local Mortgage Expert 🏠
______________________________________________________________________________
🏡 Local Mortgage Broker Near Me: How to Find the Best Mortgage Options in Katy & Houston
Looking for a local mortgage broker near you? Discover how working with an experienced mortgage professional in Katy, Fulshear, or Houston can help you compare loan programs, understand closing costs, and make confident home financing decisions.
Why Choosing the Right Local Mortgage Broker Matters
Buying a home is one of the largest financial decisions most people will ever make. Whether you're purchasing your first home, relocating to Houston, upgrading to a larger property, or refinancing your current mortgage, choosing the right financing professional can make a meaningful difference.
If you've recently searched Google for "local mortgage broker near me," "mortgage broker Katy TX," or "best mortgage broker Houston," you're probably looking for someone who understands your local housing market and can help you navigate the lending process.
I'm Bill Rapp, CCIM, Director of Capital Advisory with Medallion Funds. I've worked in lending since 2002, helping borrowers understand financing structures, evaluate loan options, and make informed financial decisions.
At Medallion Funds, our objective is straightforward: help borrowers identify financing solutions that align with their goals, qualifications, and financial circumstances.
Let's explore what you should know before choosing a mortgage broker.
1. What Does a Local Mortgage Broker Actually Do?
A mortgage broker serves as an intermediary between borrowers and mortgage lenders.
Unlike a traditional bank that generally offers its own lending products, a mortgage broker can work with multiple lending sources to identify financing options.
A mortgage broker may help you:
·Compare mortgage interest rates and annual percentage rates (APRs).
·Explore conventional, FHA, VA, USDA, jumbo, and specialty loan programs.
·Understand down payment and closing cost requirements.
·Evaluate your credit, income, assets, and debt-to-income ratio.
·Coordinate the loan process from application through closing.
·Compare loan estimates, lender fees, and financing structures.
The biggest advantage is choice.
Instead of assuming one lender has the best solution, you can evaluate multiple available financing options based on your circumstances.
However, a broker does not necessarily have access to every lender, and no mortgage professional can guarantee the lowest rate or loan approval.
2. Why Work With a Mortgage Broker in Katy, Fulshear, or Houston?
Real estate is local, and mortgage financing often involves location-specific considerations.
A mortgage broker familiar with the Greater Houston area can help borrowers understand how property taxes, insurance costs, flood exposure, homeowners association fees, and local property characteristics affect affordability.
Understanding Texas Property Taxes
Texas property taxes can represent a significant portion of your monthly housing expense.
Two similarly priced homes in Katy and Fulshear may have different monthly payments because of tax rates, special districts, or exemptions.
Some properties are located in municipal utility districts (MUDs), which may add to the total property tax burden.
A knowledgeable mortgage professional can help you evaluate the complete payment—not just the principal and interest.
Understanding Houston-Area Insurance Costs
Homeowners insurance, windstorm exposure, and flood insurance requirements can affect both your monthly payment and loan qualification.
Flood insurance requirements depend on factors such as the property's flood-zone designation, loan type, and lender requirements. Flood risk can also exist outside high-risk flood zones.
Before purchasing, buyers should obtain realistic insurance estimates.
Understanding New Construction Financing
Katy, Fulshear, Richmond, and surrounding communities offer numerous new construction opportunities.
Builders may advertise preferred-lender incentives, closing cost assistance, or mortgage rate buydowns.
Those incentives can be valuable, but buyers should compare the total financing package against independent mortgage options.
A local mortgage broker can help you evaluate whether the builder's preferred financing is competitive.
3. What Mortgage Loan Programs Are Available?
One reason borrowers search for a mortgage broker near them is to find programs beyond a traditional bank's standard offerings.
At Medallion Funds, we help borrowers explore financing options that may include:
Conventional Mortgage Loans
Conventional mortgages are popular with borrowers who have established credit, stable income, and qualifying assets.
Some conventional programs allow down payments as low as 3% for eligible borrowers.
FHA Home Loans
FHA loans can be attractive to first-time homebuyers and borrowers who need more flexible qualification guidelines.
Eligible borrowers may qualify with a down payment as low as 3.5%, subject to credit and other underwriting requirements.
FHA loans generally require mortgage insurance.
VA Home Loans
Eligible veterans, active-duty service members, and certain surviving spouses may qualify for VA-backed home loans.
Benefits can include no required down payment, subject to eligibility and lender requirements, and no monthly mortgage insurance.
Some borrowers must pay a VA funding fee, while others qualify for exemptions.
USDA Home Loans
USDA loans may provide 100% financing for eligible borrowers purchasing qualifying properties in designated rural areas.
Eligibility depends on property location, household income, and other program requirements.
Some communities outside Houston's urban core may contain eligible properties, but each address must be verified.
Doctor and Dentist Mortgage Programs
Medical professionals may have unique borrowing circumstances, including substantial student loan debt, employment contracts, or limited savings early in their careers.
Doctor and dentist mortgage programs may offer specialized underwriting and down payment structures for qualifying professionals.
Jumbo Mortgage Loans
Borrowers purchasing higher-priced homes may need jumbo financing or another nonconforming loan structure.
These programs can have different credit, reserve, income, and down payment requirements.
Bank Statement and Non-QM Loans
Self-employed borrowers, business owners, and independent contractors may benefit from alternative documentation mortgage programs.
Certain lenders offer bank statement loans or other non-qualified mortgage products that evaluate income differently from conventional lending.
Program availability and qualification requirements vary by lender.
4. Is a Local Mortgage Broker Better Than a Bank?
The answer depends on your needs.
A bank may be a strong choice when its loan programs, pricing, and underwriting guidelines align with your situation.
A mortgage broker can be particularly useful when you want to compare multiple lenders or explore specialty financing.
Mortgage Broker | Traditional Bank |
May offer programs from multiple lenders | Primarily offers its own products |
Can compare different lender guidelines | Uses its available lending guidelines |
May provide specialty mortgage options | Specialty options vary by institution |
Coordinates the mortgage process | Coordinates the mortgage process |
Pricing and fees vary | Pricing and fees vary |
The best decision comes from comparing actual loan estimates, not assuming one channel is always cheaper.
Ask each lender or broker to explain the interest rate, APR, discount points, origination charges, lender credits, and estimated cash to close.
5. How Much Does It Cost to Use a Mortgage Broker?
Mortgage broker compensation can vary.
Depending on the transaction, the broker may be compensated by the lender or by the borrower, subject to applicable mortgage compensation rules.
Borrowers should review all disclosed costs and compare the complete loan structure.
Important costs may include:
·Origination charges and discount points.
·Appraisal and credit report fees.
·Title, settlement, and recording charges.
·Prepaid property taxes and insurance.
·Initial escrow account deposits.
Remember that the lowest advertised interest rate is not automatically the lowest-cost mortgage.
A lower rate may require paying more in upfront discount points.
Comparing APR, upfront costs, and expected time in the home can help identify the more appropriate financing option.
6. Real-World Example: Buying a $400,000 Home in Katy, Texas
Consider a hypothetical first-time homebuyer purchasing a $400,000 home in Katy.
The borrower is comparing two conventional mortgage options with a 5% down payment.
Purchase price: $400,000
Down payment: $20,000
Loan amount: $380,000
Loan term: 30 years
Here are two illustrative financing scenarios:
Loan Feature | Option A | Option B |
Interest rate | 6.50% | 6.25% |
Principal & interest | $2,402 | $2,340 |
Discount points | $0 | $3,800 |
Monthly P&I savings | — | ~$62 |
Option B saves approximately $62 per month in principal and interest.
However, it requires an additional $3,800 in upfront discount points.
Dividing the additional upfront cost by the monthly savings produces a simple break-even period of approximately 61 months.
If the borrower expects to refinance or sell before that point, Option A could be more attractive.
If the borrower plans to keep the mortgage longer, Option B might be worth considering.
This is a simplified comparison, not a loan quote. Actual pricing, APR, mortgage insurance, taxes, insurance, and other costs will vary.
The lesson: Compare the total mortgage strategy, not just the interest rate.
7. Seven Questions to Ask Before Choosing a Local Mortgage Broker
Before selecting a mortgage professional, ask:
1.Are you properly licensed to originate mortgages in my state?
2.Which mortgage lenders and programs can you access?
3.What are my estimated interest rate, APR, and closing costs?
4.Are discount points required to obtain the quoted rate?
5.Which mortgage program best fits my income, credit, and down payment?
6.How will you communicate with me during underwriting and closing?
7.Can you explain my Loan Estimate and total cash to close?
You should also verify an individual mortgage originator's licensing information through NMLS Consumer Access.
8. How to Get Pre-Approved for a Mortgage
Getting pre-approved before shopping for a home can help you understand your purchasing power.
The process typically includes:
Step 1: Review your financial situation. Discuss income, employment, credit, assets, debts, and available down payment funds.
Step 2: Explore mortgage programs. Identify loan options that match your financial profile.
Step 3: Submit documentation. Depending on the program, this may include pay stubs, W-2s, tax returns, bank statements, or business financial records.
Step 4: Review estimated monthly payments. Consider principal, interest, taxes, insurance, mortgage insurance, and HOA dues where applicable.
Step 5: Obtain a pre-approval letter. A pre-approval can strengthen your home search, although it does not guarantee final loan approval.
Step 6: Coordinate with your real estate agent. Shop for homes within a comfortable budget rather than simply purchasing at the maximum approved amount.
9. Why Choose Medallion Funds?
When searching for a mortgage broker in Katy, Fulshear, or Houston, experience and communication matter.
My approach at Medallion Funds emphasizes:
Experience: I've worked in lending since 2002, helping clients evaluate financing decisions.
Education: I believe borrowers should understand their mortgage options before committing to a loan.
Loan Program Selection: We explore conventional, government-backed, jumbo, and specialty financing where available.
Local Market Perspective: I understand the importance of property taxes, insurance, new construction incentives, and housing costs across the Greater Houston market.
Long-Term Relationships: My goal is to help clients make informed decisions that support their financial objectives.
Frequently Asked Questions About Local Mortgage Brokers
How do I find a mortgage broker near me?
Search for licensed mortgage brokers serving your area, review their experience and available loan programs, verify licensing through NMLS Consumer Access, and compare written loan estimates.
Is it cheaper to use a mortgage broker or a bank?
Neither is consistently cheaper. Pricing depends on the lender, loan program, borrower qualifications, market conditions, and fees.
Can a mortgage broker help if I'm self-employed?
Yes. Some mortgage brokers work with lenders offering bank statement and other alternative-documentation programs for qualifying self-employed borrowers.
Can I buy a home with little money down?
Potentially. Conventional, FHA, VA, USDA, and certain assistance programs may provide low-down-payment options for eligible borrowers. Closing costs and other expenses still need to be considered.
Should I get pre-approved before contacting a real estate agent?
Pre-approval is often helpful before making offers because it clarifies your financing options and estimated budget.
Do mortgage brokers work with first-time homebuyers?
Yes. Mortgage brokers can help first-time buyers compare loan programs, estimate cash requirements, and understand the steps from pre-approval through closing.
Ready to Find the Right Mortgage for Your Next Home?
If you're searching for a local mortgage broker near me in Katy, Fulshear, Richmond, West Houston, or the Greater Houston area, I'd welcome the opportunity to discuss your financing goals.
Whether you're buying your first home, purchasing new construction, relocating, or refinancing, the right mortgage starts with understanding your options.
Bill Rapp
Partner & Director of Capital Advisory | Medallion Funds
Commercial Lending Nationwide
Residential Lending in AL, CA, CO, NV & TXBottom of Form
https://www.billrapponline.com/
https://findamortgagebroker.com/Profile/WilliamRappJr28883
https://billrapp.commloan.com/
https://billrapponline.com/financingfuturescre-houston-katy
https://houstoncommercialmortgage.com/
https://author.billrapponline.com
https://doctorvideo.billrapponline.com/
https://veteransvideo.billrapponline.com/
https://mortgageviking.billrapponline.com/
https://fha203h.billrapponline.com/
https://renovationvideo.billrapponline.com
https://medallionfunds.com/bill-rapp/
https://www.amazon.com/dp/B0F32Z5BH2
https://veed.cello.so/FOmzTty6oi9
https://buymeacoffee.com/vikingente3
https://creplaybookseries.billrapponline.com
https://creplaybook.billrapponline.com/
© Bill Rapp, Medallion Funds LLC, Director of Capital Advisory
10 Tips for First-Time Homebuyers
Buying your first home can be both exciting and nerve-wracking at the same time. With so many things to consider and....
How To Choose the Right Lender for You
Lorem Ipsum is simply dummy text of the printing and typesetting industry. Lorem Ipsum has been the industry's standard dummy
Refinancing youe loan and when to do it
Lorem Ipsum is simply dummy text of the printing and typesetting industry. Lorem Ipsum has been the industry's standard dummy
Copyright ©2021 | Mortgage Viking Team
Licensed to Do Business | NMLS # 228246
This is not an offer to enter into an agreement. Not all customers will qualify. Information, rates and programs are subject to change without notice. All products are subject to credit and property approval. Other restrictions and limitations may apply. Copyright © 2021 | Medallion Funds
Corporate | NMLS ID NMLS # 1825831
Corporate Address : 2651 N. Green Valley Pkwy STE. 101 Henderson, NV 89014
Corporate NMLS NMLS # 1825831 | Company Website: https://medallionfunds.com/bill-rapp/
Copyright ©2021 | Mortgage Viking Team Licensed to Do Business | NMLS # 228246
This is not an offer to enter into an agreement. Not all customers will qualify. Information, rates and programs are subject to change without notice. All products are subject to credit and property approval. Other restrictions and limitations may apply
Corporate | NMLS ID NMLS # 1825831
Corporate Address : 2651 N. Green Valley Pkwy STE. 101 Henderson, NV 89014 https://medallionfunds.com/bill-rapp/
Facebook
Instagram
X
LinkedIn
Youtube
TikTok