Low Rates.
Our rates are low, our application is quick and easy! We can get you clear to close in as little as 10 days!
Trusted By Agents With
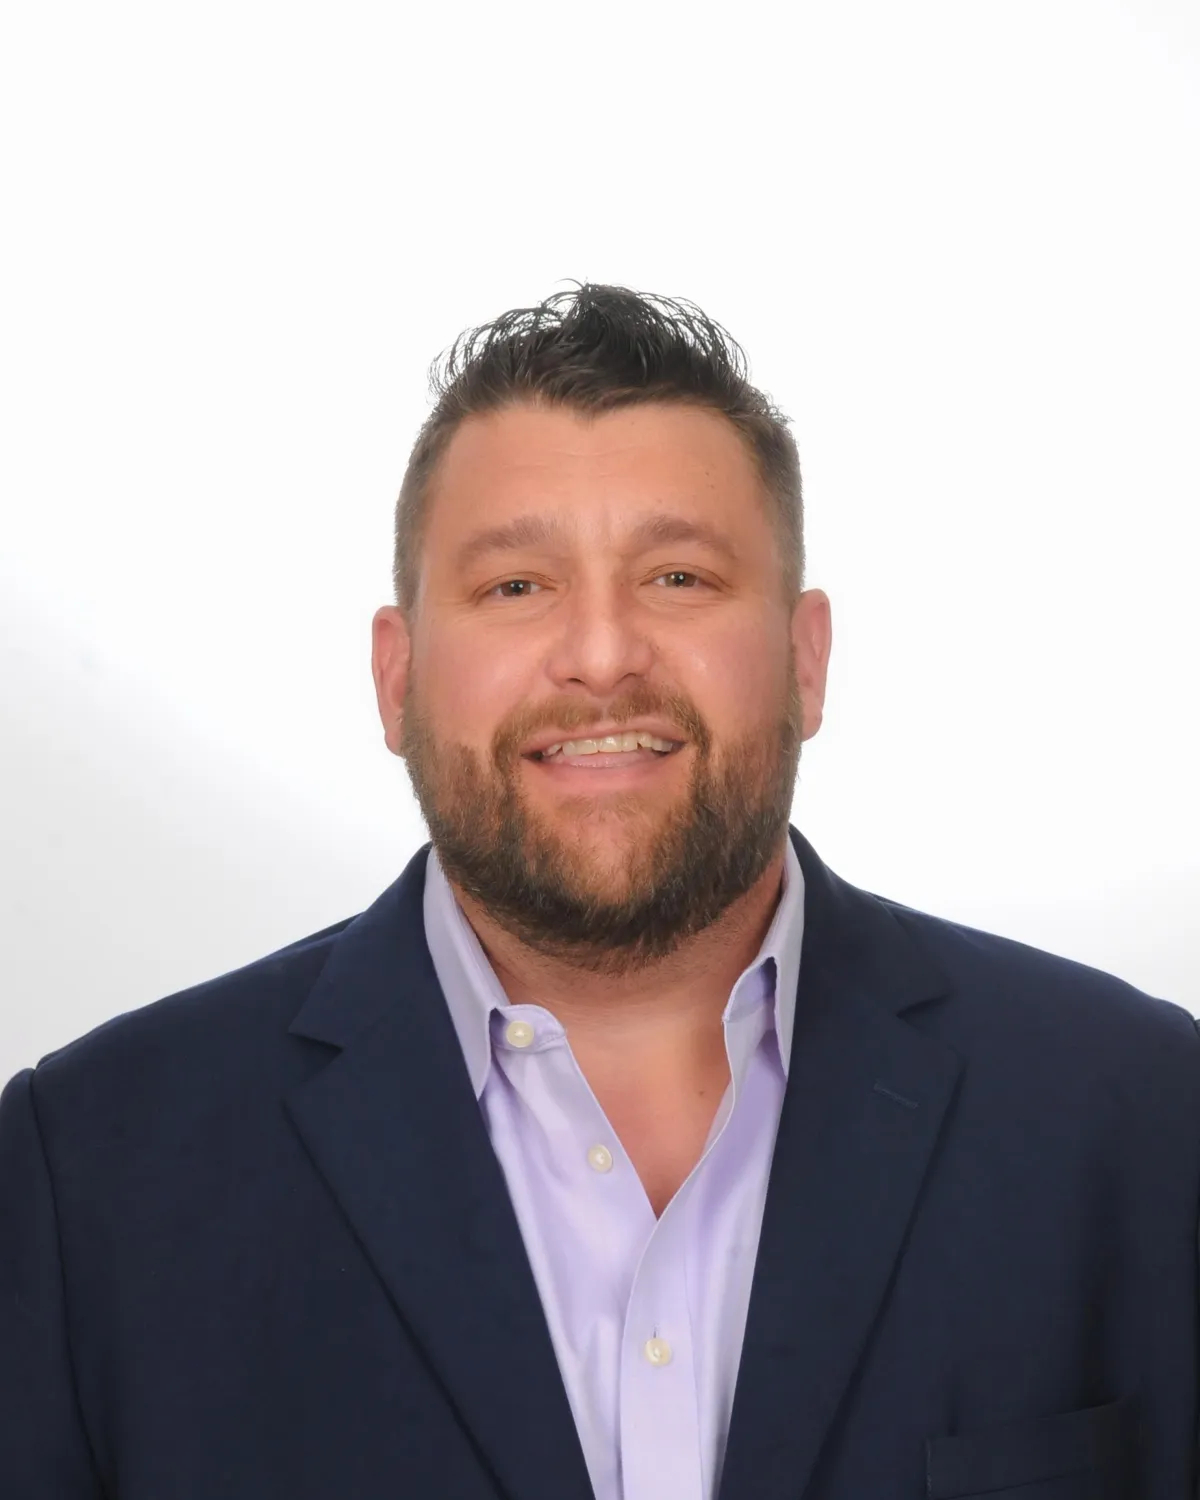
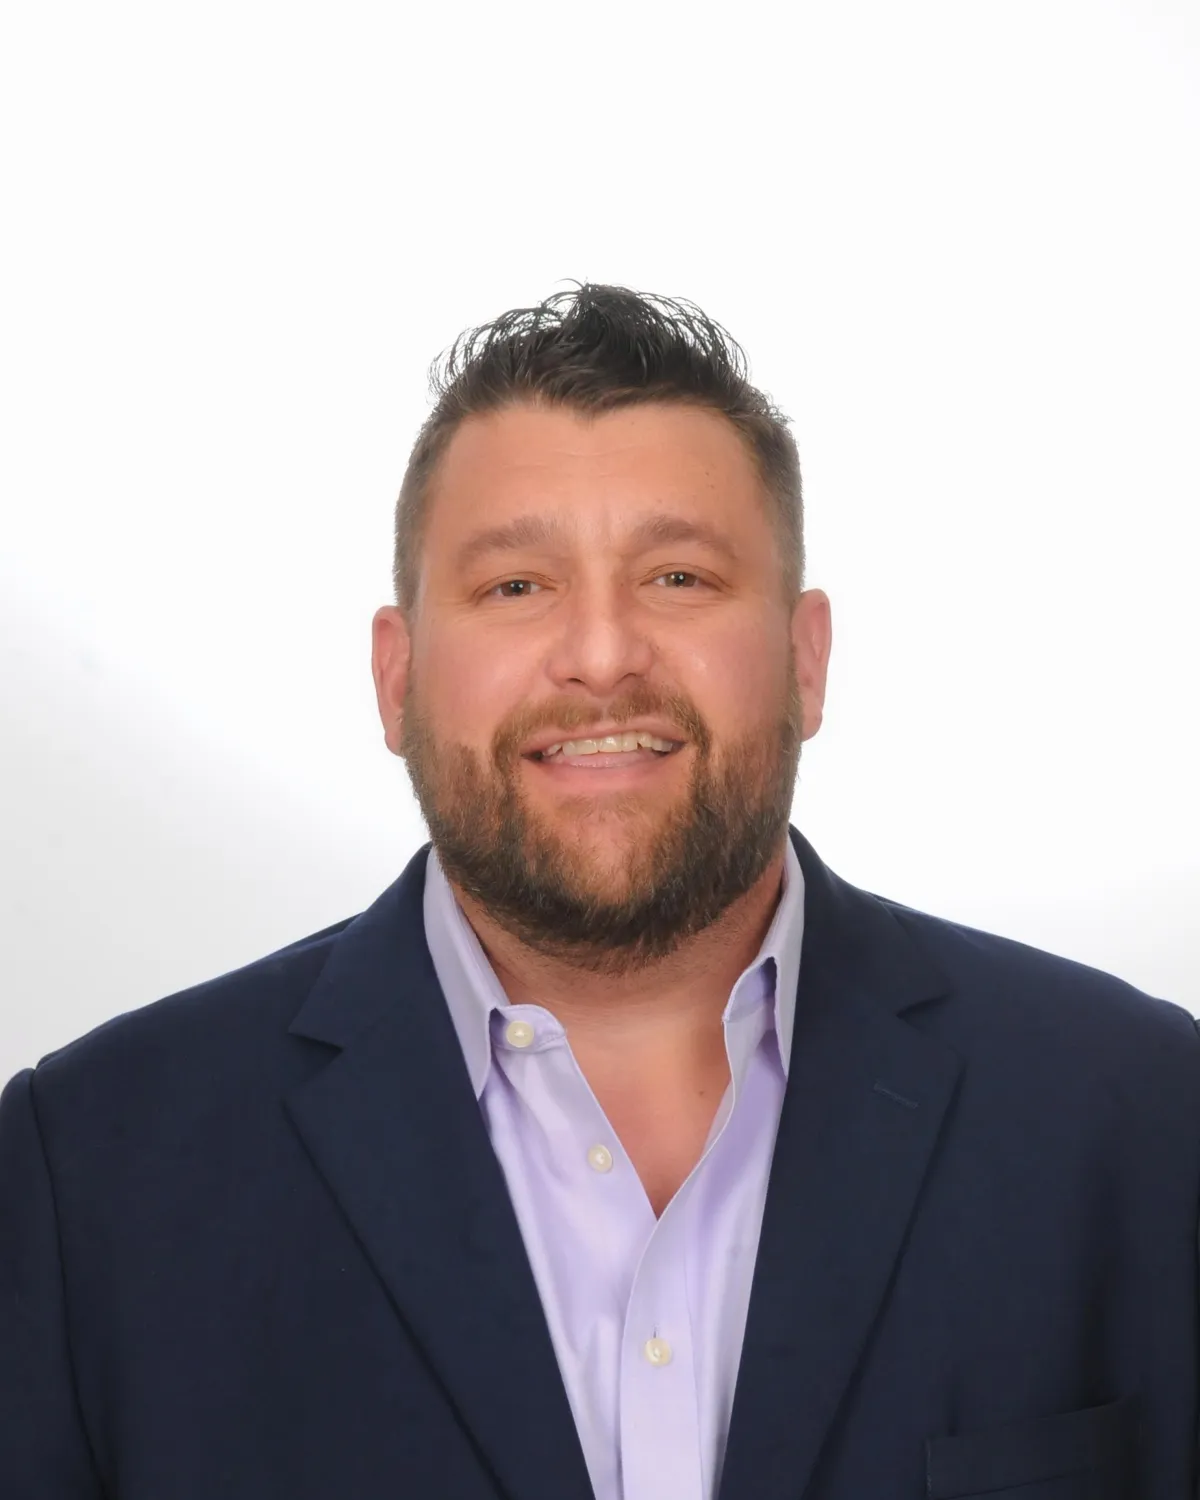
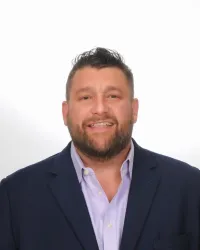
Meet Bill Rapp
NMLS ID # NMLS # 228246
Bill Rapp, CCIM is a Houston-based Capital Advisor at Medallion Funds, specializing in commercial real estate finance and strategic lending solutions. With over two decades of experience across brokerage and capital markets, Bill has worked with leading firms including eXp Commercial, NEXA Mortgage, Viking Enterprise LLC, and Sun Realty Houston.
A graduate of Texas A&M University with a BBA in Finance, Bill brings a disciplined, underwriting-first approach to every deal. His expertise spans commercial and residential financing, including asset-based lending, FHA financing, reverse mortgages, REO properties, and investment strategies for both single-family and commercial assets.
Known for his focus on structure over rate, Bill helps investors, business owners, and developers navigate complex transactions with clarity, precision, and a long-term wealth-building mindset.
The Client Experience
Great experience purchasing our first home! Bill was easy to reach and always able to answer any questions or concerns.

Loan Programs Available


Blogs
The Top 5 Mortgage Mistakes to Avoid
Buying your first home can be both exciting and nerve-wracking at the same time. With so many things to consider and....
Mortgage Do and
Do not list
Mortgages can be tricky, and it's easy to make mistakes that can end up costing you dearly. That's why we've put together this list....
Tips On How To Improve Your Credit Score
Let's talk about some ways you can improve your credit score! Your credit score is actually a big deal, and it can affect...
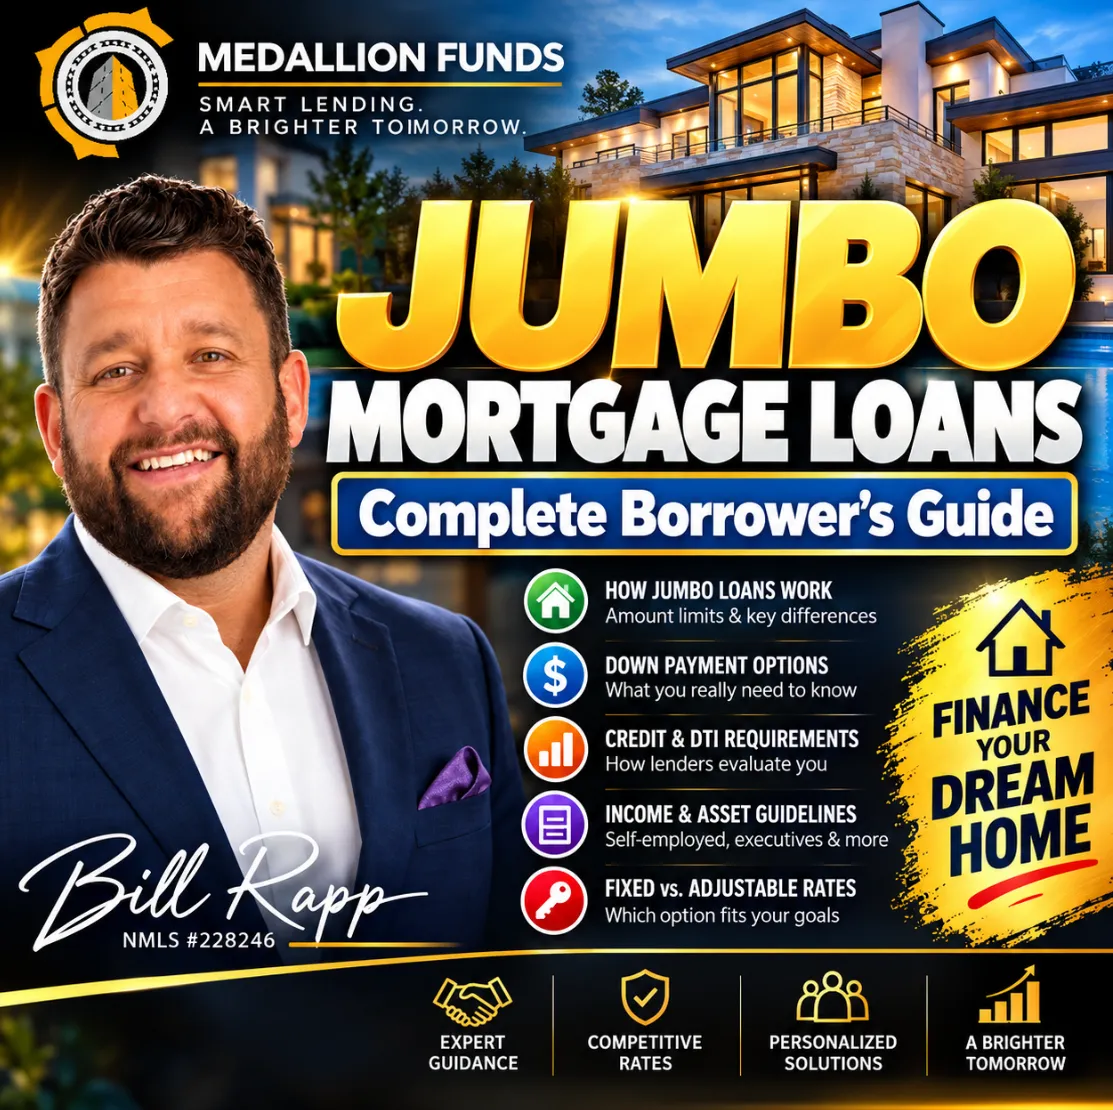
🏡 Jumbo Mortgage Loans: The Complete Borrower’s Guide to Financing a High-Value Home 💰
🏡 Jumbo Mortgage Loans: The Complete Borrower’s Guide to Financing a High-Value Home 💰
🔑 Jumbo Loans Explained: How to Qualify, Compare Options & Finance Your Dream Home 🏠
________________________________________________________________________________
Jumbo Mortgage Loans: Complete Borrower’s Guide
When the price of your dream home exceeds conventional conforming loan limits, a jumbo mortgage loan may provide the financing needed to complete the purchase.
Jumbo loans are designed for borrowers who need larger mortgage amounts than those permitted under conforming loan programs. They are commonly associated with luxury homes and expensive housing markets, but they can also be relevant for professionals, executives, business owners, investors purchasing a primary residence, and other borrowers buying higher-value properties.
Because jumbo mortgages represent larger credit exposures for lenders, qualifying can be different from obtaining a conventional conforming mortgage.
Understanding those differences before shopping for a home can make the financing process considerably easier.
What Is a Jumbo Mortgage Loan?
A jumbo mortgage is a home loan with an amount exceeding the applicable conforming loan limit for the property.
Conforming loans generally follow guidelines established for mortgages eligible for purchase by Fannie Mae or Freddie Mac. A mortgage above the applicable conforming limit is typically considered a non-conforming—or jumbo—loan.
Importantly, the applicable threshold can depend on the property location, number of units, and current year's loan limits.
Instead of assuming that a particular purchase price automatically requires jumbo financing, have your mortgage professional calculate the required loan amount and determine which financing category applies.
How Do Jumbo Loans Work?
The basic structure resembles other mortgages. You purchase or refinance a property, contribute the required equity or down payment, and finance the remainder with a mortgage.
The major difference is underwriting.
Because a jumbo lender may be taking on a substantially larger loan balance, underwriting standards can place additional emphasis on:
·Credit history and credit scores
·Debt-to-income ratio
·Income stability
·Employment or business income
·Liquid assets
·Post-closing reserves
·Down payment and loan-to-value ratio
·Property value and marketability
·Overall borrower financial strength
Jumbo underwriting is not necessarily about checking one additional box. Lenders frequently evaluate the borrower's entire financial profile.
How Much Down Payment Do You Need for a Jumbo Loan?
One of the biggest misconceptions about jumbo mortgages is that every borrower needs an enormous down payment.
There is no universal down-payment requirement for all jumbo loans.
Available loan-to-value ratios depend on factors including the lender, loan amount, occupancy, property type, credit profile and overall financial strength of the borrower.
Some borrowers may qualify for relatively high-LTV jumbo programs, while larger loan balances or more complex scenarios may require additional equity.
This is one reason working with a mortgage broker for jumbo loans can be valuable. Instead of evaluating a single institution's lending guidelines, a broker can explore available programs and determine which structures align with the transaction.
What Credit Score Do You Need for a Jumbo Mortgage?
Jumbo lenders typically place significant emphasis on credit quality, although there is no single credit-score requirement applicable to every program.
The larger the mortgage exposure, the more closely the lender may examine the borrower's overall credit history.
Beyond the score itself, underwriting may review:
·Payment history
·Mortgage history
·Revolving credit utilization
·Installment debt
·Recent credit inquiries
·Derogatory credit events
·Overall debt obligations
A strong score can help, but jumbo qualification usually involves more than the number shown on a credit report.
Debt-to-Income Ratio and Jumbo Loans
Your debt-to-income ratio (DTI) compares qualifying monthly debt obligations with qualifying monthly income.
For example, if a borrower has $15,000 in qualifying monthly income and $5,250 in applicable monthly obligations, the resulting DTI is 35%.
However, jumbo underwriting can become more nuanced for borrowers with bonuses, commissions, restricted stock, partnership income, business income, investment income, rental properties or other nontraditional compensation.
A borrower with substantial income and assets can still encounter underwriting challenges if the income cannot be documented according to a particular lender's guidelines.
This makes early financial review particularly important.
Why Cash Reserves Matter
A lender may want to know not only whether you can make the down payment and pay closing costs, but also how much liquidity remains after closing.
These funds are generally referred to as reserves.
Depending on the loan program, lenders may want borrowers to demonstrate sufficient assets to cover a specified number of months of mortgage-related obligations after closing.
Reserve requirements can become especially important for larger loan amounts, multiple financed properties, or more complex financial profiles.
That means your real cash requirement isn't necessarily just:
Down payment + closing costs.
You should also consider:
Down payment + closing costs + required reserves + remaining personal liquidity.
A well-structured mortgage shouldn't unnecessarily leave a borrower cash-poor immediately after purchasing the property.
Jumbo Loans for Self-Employed Borrowers
Business owners and self-employed professionals can qualify for jumbo mortgages, but income documentation is often one of the most important parts of the transaction.
Traditional underwriting may evaluate personal and business tax returns, K-1s, business financial statements and other documentation.
Depending on the available programs and borrower circumstances, alternative-documentation mortgage options may also exist.
The key is addressing income qualification before entering a purchase contract whenever possible.
If you're self-employed, don't wait until underwriting to discover how the lender will calculate your qualifying income.
Jumbo Mortgages for Doctors and Dentists
Physicians, dentists and other qualifying professionals can present unusual mortgage profiles.
A doctor might have excellent future earning potential while simultaneously carrying significant student debt or having relatively limited accumulated assets early in a career.
Certain professional mortgage programs may address some of these circumstances differently than standard jumbo financing.
Rather than automatically choosing a traditional jumbo mortgage, qualified medical professionals should compare available doctor mortgage and jumbo loan options based on their specific financial situation.
Jumbo Fixed-Rate vs. Adjustable-Rate Mortgages
Jumbo mortgages can potentially be structured as either fixed-rate or adjustable-rate loans, depending on available programs.
A fixed-rate mortgage provides a consistent interest rate for the life of the loan.
An adjustable-rate mortgage (ARM) generally offers an initial rate structure for a defined period before becoming subject to adjustment according to the loan's terms.
Neither structure is automatically right for every borrower.
The appropriate comparison should consider factors such as:
·How long you expect to own the property
·How long you expect to keep the mortgage
·Expected future income
·Liquidity
·Risk tolerance
·Potential refinancing plans
·Differences in current pricing
The lowest introductory rate shouldn't be evaluated in isolation from the rest of the loan structure.
Don't Shop for a Jumbo Mortgage by Interest Rate Alone
Rate matters—but it isn't the entire mortgage.
Two jumbo loans advertising similar rates could have very different economics.
Compare:
Interest rate: What rate applies to the loan?
APR: What does the annual percentage rate indicate about financing costs?
Points: Are you paying additional money upfront to obtain the quoted rate?
Lender fees: What origination or underwriting charges apply?
Loan structure: Is the loan fixed or adjustable?
Prepayment terms: Are there restrictions or costs relevant to your situation?
Cash-to-close: How much liquidity does the transaction consume?
Reserve requirements: How much money must remain after closing?
A mortgage should be evaluated as a complete financial structure rather than a single advertised rate.
Why Jumbo Borrowers Should Get Pre-Approved Early
Pre-approval is particularly important when purchasing a high-value property.
Before making an offer, you ideally want to understand:
1.Your realistic financing range.
2.Your estimated down payment.
3.Expected reserve requirements.
4.How your income will be calculated.
5.Potential documentation issues.
6.Which jumbo programs may fit your circumstances.
Early preparation can reduce surprises once you are under contract.
For self-employed borrowers, executives, physicians, real estate investors and borrowers with complex financial statements, early underwriting review can be especially valuable.
Documents to Prepare for Jumbo Mortgage Pre-Approval
Although requirements vary, borrowers should be prepared to provide documentation supporting income, employment, assets and credit.
Depending on the scenario, this could include recent pay statements, W-2s, tax returns, bank and investment statements, identification, mortgage statements, business documentation and information about other real estate owned.
If your finances are complicated, disclose that complexity upfront.
The objective isn't simply to get a quick pre-approval. It is to build a financing strategy that has been properly evaluated before you commit to a major real estate purchase.
How a Mortgage Broker Can Help With Jumbo Financing
Jumbo mortgage programs can vary significantly among lenders.
One institution might have a strong program for a straightforward W-2 borrower, while another could be more appropriate for a physician, business owner, investor or borrower with substantial assets but complicated taxable income.
At Medallion Funds, our objective is to evaluate the complete financing scenario—not simply quote a rate.
We can help borrowers explore mortgage structures based on factors including loan amount, property type, down payment, credit, income, liquidity and long-term objectives.
Final Thoughts: Build the Jumbo Mortgage Around Your Financial Strategy
A jumbo mortgage is a significant financial obligation. The objective should not be merely to obtain the largest loan available.
The better question is:
What mortgage structure best supports the home purchase while protecting your broader financial position?
Consider your rate, monthly payment, cash-to-close, reserves, liquidity and future plans together.
If you're considering purchasing or refinancing a high-value home, speak with Bill Rapp and Medallion Funds about your jumbo mortgage options.
Bill Rapp
Partner & Director of Capital Advisory | Medallion Funds
Commercial Lending Nationwide
Residential Lending in AL, CA, CO, NV & TXBottom of Form
https://www.billrapponline.com/
https://findamortgagebroker.com/Profile/WilliamRappJr28883
https://billrapp.commloan.com/
https://billrapponline.com/financingfuturescre-houston-katy
https://houstoncommercialmortgage.com/
https://author.billrapponline.com
https://doctorvideo.billrapponline.com/
https://veteransvideo.billrapponline.com/
https://mortgageviking.billrapponline.com/
https://fha203h.billrapponline.com/
https://renovationvideo.billrapponline.com
https://medallionfunds.com/bill-rapp/
https://www.amazon.com/dp/B0F32Z5BH2
https://veed.cello.so/FOmzTty6oi9
https://buymeacoffee.com/vikingente3
https://creplaybookseries.billrapponline.com
https://creplaybook.billrapponline.com/
© Bill Rapp, Medallion Funds LLC, Director of Capital Advisory
10 Tips for First-Time Homebuyers
Buying your first home can be both exciting and nerve-wracking at the same time. With so many things to consider and....
How To Choose the Right Lender for You
Lorem Ipsum is simply dummy text of the printing and typesetting industry. Lorem Ipsum has been the industry's standard dummy
Refinancing youe loan and when to do it
Lorem Ipsum is simply dummy text of the printing and typesetting industry. Lorem Ipsum has been the industry's standard dummy
Copyright ©2021 | Mortgage Viking Team
Licensed to Do Business | NMLS # 228246
This is not an offer to enter into an agreement. Not all customers will qualify. Information, rates and programs are subject to change without notice. All products are subject to credit and property approval. Other restrictions and limitations may apply. Copyright © 2021 | Medallion Funds
Corporate | NMLS ID NMLS # 1825831
Corporate Address : 2651 N. Green Valley Pkwy STE. 101 Henderson, NV 89014
Corporate NMLS NMLS # 1825831 | Company Website: https://medallionfunds.com/bill-rapp/
Copyright ©2021 | Mortgage Viking Team Licensed to Do Business | NMLS # 228246
This is not an offer to enter into an agreement. Not all customers will qualify. Information, rates and programs are subject to change without notice. All products are subject to credit and property approval. Other restrictions and limitations may apply
Corporate | NMLS ID NMLS # 1825831
Corporate Address : 2651 N. Green Valley Pkwy STE. 101 Henderson, NV 89014 https://medallionfunds.com/bill-rapp/
Facebook
Instagram
X
LinkedIn
Youtube
TikTok