Low Rates.
Our rates are low, our application is quick and easy! We can get you clear to close in as little as 10 days!
Trusted By Agents With
Meet Bill Rapp
NMLS ID # NMLS # 228246
Bill Rapp, CCIM is a Houston-based Capital Advisor at Medallion Funds, specializing in commercial real estate finance and strategic lending solutions. With over two decades of experience across brokerage and capital markets, Bill has worked with leading firms including eXp Commercial, NEXA Mortgage, Viking Enterprise LLC, and Sun Realty Houston.
A graduate of Texas A&M University with a BBA in Finance, Bill brings a disciplined, underwriting-first approach to every deal. His expertise spans commercial and residential financing, including asset-based lending, FHA financing, reverse mortgages, REO properties, and investment strategies for both single-family and commercial assets.
Known for his focus on structure over rate, Bill helps investors, business owners, and developers navigate complex transactions with clarity, precision, and a long-term wealth-building mindset.
The Client Experience
Great experience purchasing our first home! Bill was easy to reach and always able to answer any questions or concerns.
Loan Programs Available


Blogs
The Top 5 Mortgage Mistakes to Avoid
Buying your first home can be both exciting and nerve-wracking at the same time. With so many things to consider and....
Mortgage Do and
Do not list
Mortgages can be tricky, and it's easy to make mistakes that can end up costing you dearly. That's why we've put together this list....
Tips On How To Improve Your Credit Score
Let's talk about some ways you can improve your credit score! Your credit score is actually a big deal, and it can affect...
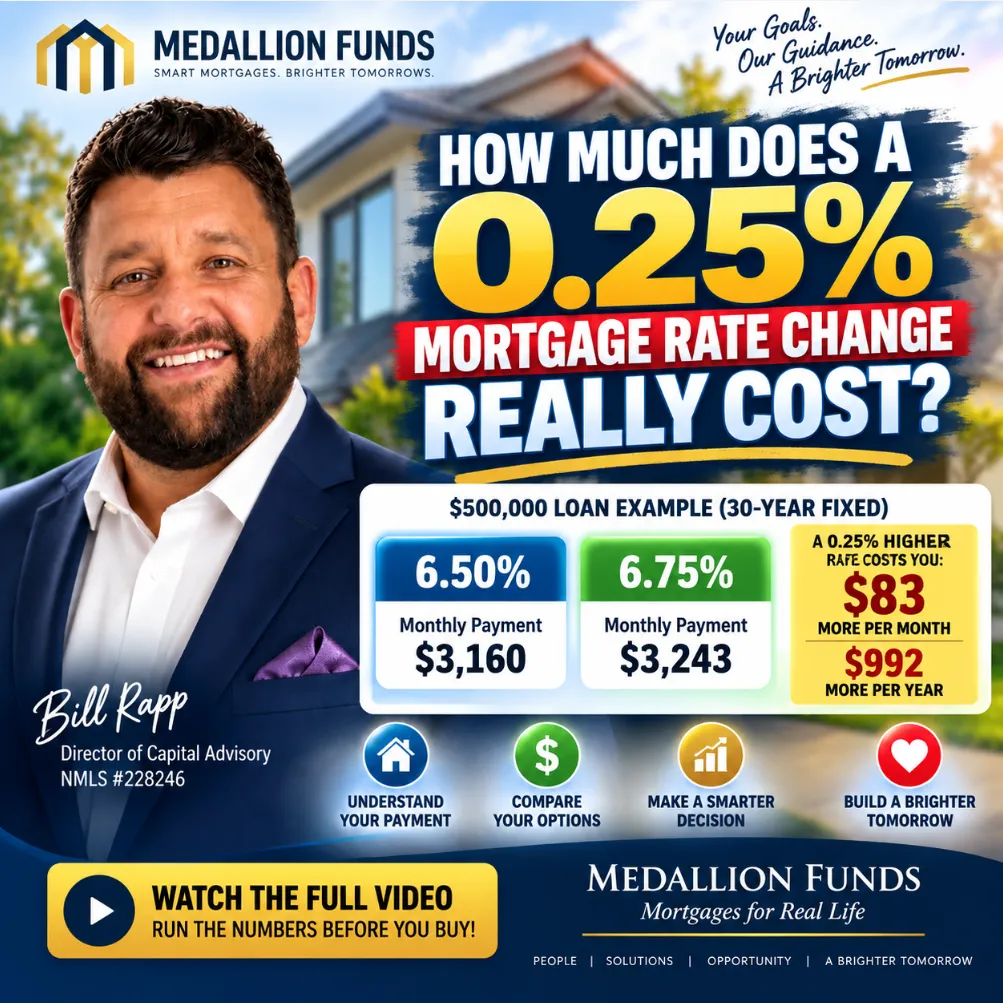
🏠 How Much Does a 0.25% Mortgage Rate Change Really Cost? See the Payment Difference 💰
🏠 How Much Does a 0.25% Mortgage Rate Change Really Cost? See the Payment Difference 💰
📉 Mortgage Rate Calculator: What a 0.25% Rate Change Means for Your Monthly Payment 🏡
________________________________________________________________________________
How Much Does a 0.25% Mortgage Rate Change Really Cost?
When mortgage rates move by just 0.25 percentage points, it can sound insignificant.
A rate change from 6.50% to 6.75% is only one-quarter of one percentage point. But when that rate is applied to hundreds of thousands of dollars over a 30-year mortgage, the difference becomes much easier to see.
For homebuyers, the more useful question isn't simply:
"What is today's mortgage rate?"
It's:
"What does that rate mean for my monthly payment, buying power, and overall financing strategy?"
Let's run the numbers.
Mortgage Payment Example: 6.50% vs. 6.75%
Assume you're financing a home with a 30-year fixed-rate mortgage. Here is the approximate principal-and-interest payment at 6.50% compared with 6.75%:
Loan Amount | Payment at 6.50% | Payment at 6.75% | Monthly Difference |
$300,000 | $1,896 | $1,946 | $50 |
$400,000 | $2,528 | $2,594 | $66 |
$500,000 | $3,160 | $3,243 | $83 |
$750,000 | $4,741 | $4,864 | $124 |
Calculations are approximate principal-and-interest payments for illustrative purposes. They exclude taxes, homeowners insurance, mortgage insurance, HOA fees, and other costs.
On a $500,000 mortgage, a 0.25% increase from 6.50% to 6.75% increases principal and interest by roughly $83 per month, or about $992 per year.
That is why small mortgage rate movements matter—but also why buyers should keep them in perspective.
The $400,000 Mortgage Example
Consider a $400,000, 30-year fixed mortgage.
At 6.50%, principal and interest is approximately:
$2,528 per month
At 6.75%, it increases to approximately:
$2,594 per month
Difference:
About $66 per month
Over 12 months, that's roughly $793.
The rate matters. But an additional $66 per month may not be enough, by itself, to justify putting an otherwise attractive home purchase on hold.
Why a 0.25% Mortgage Rate Change Can Affect Buying Power
Mortgage qualification isn't based only on the price of the house. Lenders evaluate your overall monthly obligations relative to qualifying income, subject to the requirements of the applicable loan program.
A higher mortgage rate generally produces a higher required monthly payment.
That can potentially reduce the loan amount for which a borrower qualifies.
Conversely, lower rates can improve purchasing power because the same loan balance produces a lower principal-and-interest payment.
But there is an important lesson here:
Don't shop by home price alone. Shop by payment and financing structure.
Before making an offer, understand your estimated:
·Principal and interest
·Property taxes
·Homeowners insurance
·Mortgage insurance, when applicable
·HOA assessments
·Closing costs
·Cash required at closing
The rate is one variable in a much larger financing equation.
A Lower Purchase Price Can Sometimes Matter More Than a Small Rate Change
Buyers frequently focus heavily on rates while overlooking their ability to negotiate the transaction itself.
Suppose you're considering a $500,000 property.
Depending on the transaction, negotiating the purchase price, obtaining seller-paid closing costs, or using an eligible seller concession toward a rate buydown could potentially have a larger financial impact than waiting for the market to move 0.25%.
This is why mortgage strategy and purchase negotiations should work together.
Instead of asking only:
"Should I wait for mortgage rates to fall?"
Consider asking:
"What combination of price, rate, seller concessions, loan program, and cash at closing gives me the best structure for my objectives?"
Should You Pay Discount Points to Lower Your Mortgage Rate?
Another consideration is whether paying discount points to obtain a lower interest rate makes economic sense.
The key calculation is your break-even period.
For example, if obtaining a lower rate costs $4,000 and reduces your payment by $80 per month:
$4,000 ÷ $80 = 50 months
Your approximate break-even period would be 50 months, or a little over four years.
If you expect to keep that mortgage significantly longer than the break-even period, paying points may warrant consideration.
If you expect to sell or refinance sooner, the economics could look very different.
The actual rate improvement available for any amount of points varies by lender, loan program, borrower profile, property, and market conditions.
What If Mortgage Rates Drop After You Buy?
Many buyers worry about purchasing immediately before rates decline.
That's understandable, but nobody knows with certainty exactly where mortgage rates will be months from now.
A more practical approach is to determine whether the home and financing work at today's available terms.
If rates subsequently decline enough to justify the costs of refinancing, you can evaluate refinancing at that time. Refinancing isn't automatic, however; qualification, property value, closing costs, loan terms, and the size of the rate reduction all matter.
Don't Let 0.25% Make the Entire Decision
Mortgage rates matter.
But your mortgage rate is only one component of a successful home purchase.
Your purchase price, down payment, loan program, seller concessions, property taxes, insurance, future plans, and cash reserves can be equally important—and sometimes more important.
That's why working with a mortgage broker can be valuable.
At Medallion Funds, we can evaluate different mortgage structures and help you see the actual numbers before you make a decision.
Rather than reacting to mortgage-rate headlines, you can compare scenarios based on your specific loan amount and objectives.
Want to Know What a 0.25% Rate Change Means for You?
Send us your approximate purchase price, down payment, and loan amount, and we can help you compare the numbers.
A quarter-point change may cost $40 per month for one borrower and well over $100 for another.
Don't guess. Run the numbers.
Bill Rapp
Partner & Director of Capital Advisory | Medallion Funds
Commercial Lending Nationwide
Residential Lending in AL, CA, CO, NV & TXBottom of Form
https://www.billrapponline.com/
https://findamortgagebroker.com/Profile/WilliamRappJr28883
https://billrapp.commloan.com/
https://billrapponline.com/financingfuturescre-houston-katy
https://houstoncommercialmortgage.com/
https://author.billrapponline.com
https://doctorvideo.billrapponline.com/
https://veteransvideo.billrapponline.com/
https://mortgageviking.billrapponline.com/
https://fha203h.billrapponline.com/
https://renovationvideo.billrapponline.com
https://medallionfunds.com/bill-rapp/
https://www.amazon.com/dp/B0F32Z5BH2
https://veed.cello.so/FOmzTty6oi9
https://buymeacoffee.com/vikingente3
https://creplaybookseries.billrapponline.com
https://creplaybook.billrapponline.com/
© Bill Rapp, Medallion Funds LLC, Director of Capital Advisory
10 Tips for First-Time Homebuyers
Buying your first home can be both exciting and nerve-wracking at the same time. With so many things to consider and....
How To Choose the Right Lender for You
Lorem Ipsum is simply dummy text of the printing and typesetting industry. Lorem Ipsum has been the industry's standard dummy
Refinancing youe loan and when to do it
Lorem Ipsum is simply dummy text of the printing and typesetting industry. Lorem Ipsum has been the industry's standard dummy
Copyright ©2021 | Mortgage Viking Team
Licensed to Do Business | NMLS # 228246
This is not an offer to enter into an agreement. Not all customers will qualify. Information, rates and programs are subject to change without notice. All products are subject to credit and property approval. Other restrictions and limitations may apply. Copyright © 2021 | Medallion Funds
Corporate | NMLS ID NMLS # 1825831
Corporate Address : 2651 N. Green Valley Pkwy STE. 101 Henderson, NV 89014
Corporate NMLS NMLS # 1825831 | Company Website: https://medallionfunds.com/bill-rapp/
Copyright ©2021 | Mortgage Viking Team Licensed to Do Business | NMLS # 228246
This is not an offer to enter into an agreement. Not all customers will qualify. Information, rates and programs are subject to change without notice. All products are subject to credit and property approval. Other restrictions and limitations may apply
Corporate | NMLS ID NMLS # 1825831
Corporate Address : 2651 N. Green Valley Pkwy STE. 101 Henderson, NV 89014 https://medallionfunds.com/bill-rapp/
Facebook
Instagram
X
LinkedIn
Youtube
TikTok