Low Rates.
Our rates are low, our application is quick and easy! We can get you clear to close in as little as 10 days!
Trusted By Agents With
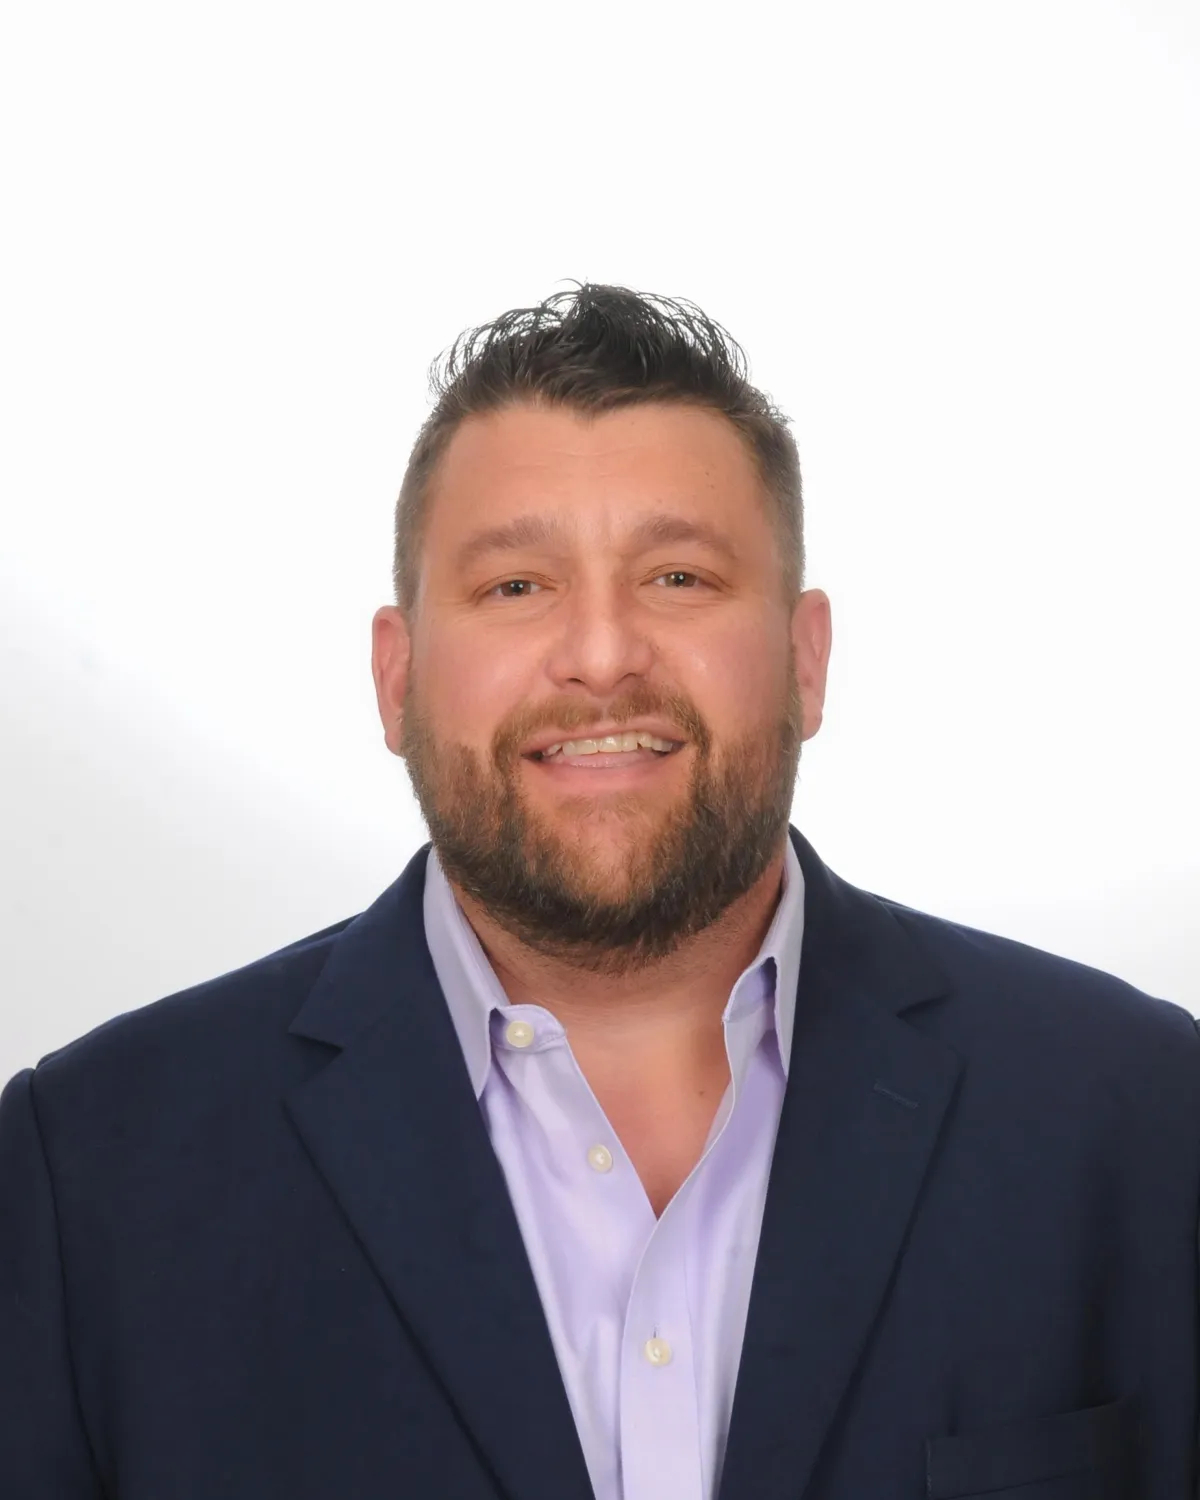
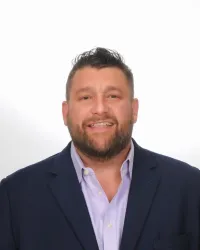
Meet Bill Rapp
NMLS ID # NMLS # 228246
Bill Rapp, CCIM is a Houston-based Capital Advisor at Medallion Funds, specializing in commercial real estate finance and strategic lending solutions. With over two decades of experience across brokerage and capital markets, Bill has worked with leading firms including eXp Commercial, NEXA Mortgage, Viking Enterprise LLC, and Sun Realty Houston.
A graduate of Texas A&M University with a BBA in Finance, Bill brings a disciplined, underwriting-first approach to every deal. His expertise spans commercial and residential financing, including asset-based lending, FHA financing, reverse mortgages, REO properties, and investment strategies for both single-family and commercial assets.
Known for his focus on structure over rate, Bill helps investors, business owners, and developers navigate complex transactions with clarity, precision, and a long-term wealth-building mindset.
The Client Experience
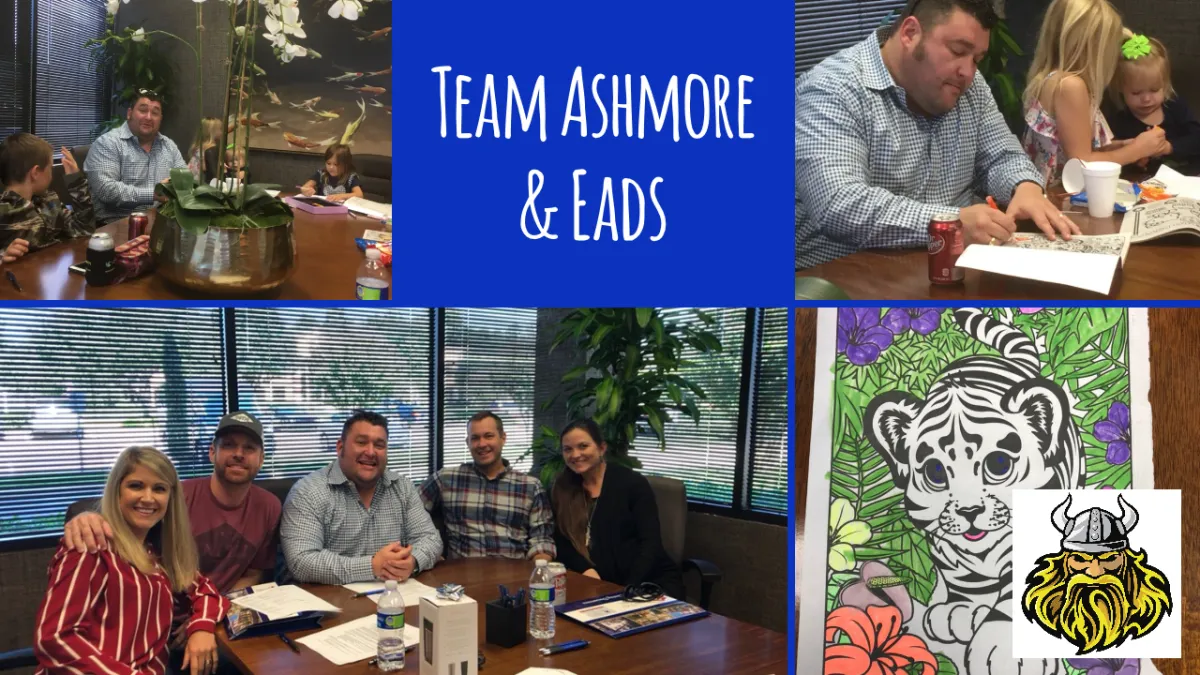
Great experience purchasing our first home! Bill was easy to reach and always able to answer any questions or concerns.

Loan Programs Available


Blogs
The Top 5 Mortgage Mistakes to Avoid
Buying your first home can be both exciting and nerve-wracking at the same time. With so many things to consider and....
Mortgage Do and
Do not list
Mortgages can be tricky, and it's easy to make mistakes that can end up costing you dearly. That's why we've put together this list....
Tips On How To Improve Your Credit Score
Let's talk about some ways you can improve your credit score! Your credit score is actually a big deal, and it can affect...
🏢 Commercial Bridge Loans: The Complete Borrower’s Guide for CRE Investors & Business Owners 🌉
🏢 Commercial Bridge Loans: The Complete Borrower’s Guide for CRE Investors & Business Owners 🌉
⚡ Commercial Bridge Loans Explained: How Short-Term CRE Financing Can Bridge the Gap 🏗️
________________________________________________________________________________
Commercial Bridge Loans: Complete Borrower’s Guide
Commercial real estate opportunities do not always wait for traditional financing.
An investor may find an acquisition that needs to close quickly. A property may have significant vacancy that prevents it from qualifying for permanent financing. A business owner may need capital to acquire and renovate a building before moving operations. Or an existing commercial loan may be approaching maturity before the property is ready for a conventional refinance.
These are situations where a commercial bridge loan may provide a solution.
Commercial bridge financing is designed to provide short-term capital while the borrower executes a specific business plan and works toward a more permanent financing solution.
The key word is bridge.
The loan is intended to get the borrower from the property's current situation to a future event—such as stabilization, renovation completion, lease-up, sale, or permanent refinancing.
Understanding how bridge loans work, what lenders evaluate, and how to structure a realistic exit strategy can help commercial real estate investors and business owners determine whether bridge financing makes sense for a particular transaction.
What Is a Commercial Bridge Loan?
A commercial bridge loan is a short-term commercial real estate loan typically used when conventional or permanent financing is unavailable, impractical, or too slow for the transaction.
Instead of underwriting only the property's current performance, a bridge lender may place significant emphasis on:
·Property value and basis
·Borrower equity
·Current and projected cash flow
·Renovation or repositioning plan
·Sponsorship and experience
·Market fundamentals
·Collateral
·Liquidity and reserves
·The borrower's exit strategy
This can make bridge financing useful for properties that are temporarily unable to satisfy traditional bank, agency, CMBS, or other permanent-loan requirements.
How Commercial Bridge Loans Work
Consider an investor purchasing a multifamily property with substantial vacancy and several units requiring renovation.
The property's current NOI may not support the amount of permanent financing the investor ultimately wants.
However, the investor's business plan calls for renovating the units, increasing occupancy, improving operations, and stabilizing NOI.
A bridge lender may potentially finance the acquisition and, depending on the program, provide funding for some renovation costs.
Once the property reaches stabilization, the investor may attempt to refinance the bridge loan with longer-term financing.
The basic strategy becomes:
Acquire → Improve → Stabilize → Refinance or Sell
That final step is critical because a bridge loan should generally be structured around a clearly defined exit.
When Does a Commercial Bridge Loan Make Sense?
Bridge financing can potentially be useful in several situations.
Time-Sensitive Acquisitions
Some commercial real estate transactions require a faster closing than traditional lenders can accommodate.
A bridge lender may provide an alternative when execution speed is particularly important.
Value-Add Properties
A property may require renovations, operational improvements, or repositioning before it qualifies for attractive permanent financing.
Bridge financing can provide time to execute that strategy.
Lease-Up Opportunities
An office, retail, industrial, or multifamily property may have excessive vacancy at acquisition.
If the borrower has a credible leasing strategy, bridge financing may provide a path toward stabilization.
Maturing Commercial Loans
A borrower may have a balloon payment approaching but not yet qualify for the desired permanent refinance.
A bridge loan can potentially provide additional time, although borrowers should carefully evaluate the cost and feasibility of the eventual refinance.
Transitional Properties
Properties experiencing temporary operational or financial disruption can sometimes fall outside conventional lending parameters.
Bridge lenders may evaluate the transaction based partly on the property's future stabilized performance.
Commercial Bridge Loan Terms
There is no universal bridge-loan structure.
Terms depend on the lender, property, borrower, leverage, market, business plan, and exit strategy.
Bridge loans commonly feature relatively short terms compared with permanent commercial mortgages. Some programs may also provide extension options, subject to lender requirements and fees.
Borrowers should evaluate much more than the headline interest rate.
Important variables can include:
Loan amount: How much capital will the lender actually provide?
LTV: What percentage of the property's value can be financed?
LTC: For acquisition and renovation transactions, how much of the total project cost can be financed?
Interest rate: Bridge financing generally carries higher pricing than stabilized permanent debt because the lender is assuming additional transitional risk.
Origination fees: Upfront lender points or fees can materially affect the effective borrowing cost.
Interest reserves: Some transactions may include reserves designed to help service debt during renovation or stabilization.
Renovation funding: Certain lenders can finance eligible improvements, often through future funding or construction draws.
Extension options: Borrowers should understand the requirements, fees, and conditions for extending the loan.
Prepayment provisions: These can matter substantially when the strategy is to refinance or sell quickly.
LTV Is Not the Whole Story
Borrowers sometimes focus on one question:
“What is your maximum LTV?”
That is important—but it does not necessarily determine the final loan amount.
Commercial lenders may evaluate several constraints simultaneously.
For example, proceeds could be influenced by:
Loan-to-value (LTV): Loan amount relative to collateral value.
Loan-to-cost (LTC): Loan amount relative to total project cost.
Debt yield: Property NOI relative to loan amount.
DSCR: Property cash flow relative to required debt payments.
Borrower equity: The amount of cash the sponsor has invested or will contribute.
Depending on the lender and transaction, one of these metrics may become the limiting factor.
That is why borrowers should underwrite the entire capital stack, rather than assuming the maximum advertised LTV equals guaranteed proceeds.
What Do Commercial Bridge Lenders Look For?
Bridge lenders generally want to understand two things:
Why does the property need bridge financing today?
And:
What will change so the borrower can repay the bridge loan tomorrow?
A credible transaction should therefore tell a coherent story.
For example:
The property is currently 70% occupied. The borrower plans to renovate vacant units, increase occupancy to 93%, grow NOI, and refinance into permanent financing after stabilization.
The lender will then test those assumptions.
Can the renovations realistically be completed?
Is the proposed rent supported by the market?
Is the stabilization timeline achievable?
Does the sponsor have sufficient liquidity?
What happens if stabilization takes longer than expected?
And most importantly:
Will the projected stabilized property support the anticipated permanent refinance?
The Exit Strategy Is Critical
Bridge financing without a realistic exit strategy can create substantial risk.
Common exit strategies include:
Permanent refinance: Improve the property sufficiently to qualify for longer-term financing.
Property sale: Complete renovations or repositioning and sell the asset.
Business stabilization: An owner-user improves operations or completes a transition before refinancing.
The exit should ideally be evaluated before the bridge loan closes.
If the plan is refinancing, estimate future NOI, property value, interest rate, DSCR, LTV, and expected permanent-loan proceeds.
Do not assume tomorrow's lender will refinance the entire bridge balance.
Stress-Test Your Bridge Loan
A prudent borrower should test what happens when the business plan does not perform exactly as projected.
Ask questions such as:
What happens if renovations take six months longer?
What if occupancy stabilizes at 88% instead of 95%?
What if NOI is 10% below projections?
What if the property's appraised value is lower than expected?
What if permanent interest rates are higher at refinance?
What if the permanent lender requires a lower LTV?
This analysis can reveal whether the transaction has enough margin for error.
Commercial Bridge Loans vs. Hard Money Loans
The terms bridge loan and hard money loan are sometimes used interchangeably, but they do not always describe exactly the same product.
Both can provide short-term capital for transactions that may not fit traditional lending requirements.
However, the bridge-loan market includes a wide spectrum of capital sources—from banks and debt funds to private lenders and institutional lenders.
Pricing, leverage, documentation requirements, recourse, underwriting standards, and closing speed can therefore vary significantly.
Borrowers should compare the complete financing structure, rather than focusing solely on how a lender describes its product.
The Cost of Commercial Bridge Financing
Bridge financing is typically more expensive than permanent commercial debt.
But cost should be considered in context.
Suppose an investor has an opportunity to acquire a property at an attractive basis, execute renovations, increase NOI, and create substantial value.
In that situation, paying more for short-term capital may potentially make economic sense.
Conversely, expensive bridge debt without a credible value-creation strategy or refinance path can create significant risk.
The question is not simply:
“Is the bridge rate high?”
A better question is:
“Does the projected return justify the cost and risk of the bridge capital?”
Documents You May Need
Requirements vary substantially among lenders, but borrowers should generally be prepared to provide information relating to the property, borrower, guarantors, and proposed business plan.
That can include purchase agreements, rent rolls, operating statements, borrower financial statements, schedules of real estate owned, renovation budgets, construction scopes, organizational documents, bank statements, leases, property photos, and other due-diligence materials.
Having a complete package prepared can make lender discussions more efficient.
How a Commercial Mortgage Broker Can Help
The bridge lending market can be fragmented.
Different lenders specialize in different property types, transaction sizes, leverage levels, geographic markets, borrower profiles, and business plans.
A commercial mortgage broker can help package the transaction, identify potential capital sources, compare financing structures, and evaluate the proposed exit strategy.
Through the CommLoan Empower Program, I work with commercial real estate investors and business owners to evaluate financing opportunities and identify potential lending solutions through the CommLoan platform and lender marketplace.
The objective is not simply to find a loan.
It is to find a financing structure that fits the property, borrower, business plan, capital stack, and exit strategy.
Final Thoughts
Commercial bridge loans can be powerful tools when the financing structure matches the investment strategy.
They can help investors acquire transitional properties, renovate assets, improve occupancy, bridge maturity dates, and reposition commercial real estate before moving into permanent financing.
But short-term financing creates a short-term deadline.
Before closing a bridge loan, understand the costs, leverage, extension provisions, reserves, renovation requirements, prepayment terms, and—most importantly—the exit strategy.
Bridge financing should solve a temporary problem while creating a realistic path toward a permanent solution.
Top of Form
Bottom of Form
Bill Rapp, CCIM
Director | CommLoan
📞 281-222-0433
📧 [email protected]
🌐 https://billrapp.commloan.com/
🌐 https://HoustonCommercialMortgage.com/
Commercial Real Estate Financing Nationwide
https://billrapp.commloan.com/
https://author.billrapponline.com/
https://www.amazon.com/dp/B0F32Z5BH2
https://veed.cello.so/FOmzTty6oi9
https://buymeacoffee.com/vikingente3
https://creplaybookseries.billrapponline.com
https://creplaybook.billrapponline.com/
©Bill Rapp, CCIM - Director - CommLoan
10 Tips for First-Time Homebuyers
Buying your first home can be both exciting and nerve-wracking at the same time. With so many things to consider and....
How To Choose the Right Lender for You
Lorem Ipsum is simply dummy text of the printing and typesetting industry. Lorem Ipsum has been the industry's standard dummy
Refinancing youe loan and when to do it
Lorem Ipsum is simply dummy text of the printing and typesetting industry. Lorem Ipsum has been the industry's standard dummy
Copyright ©2021 | Mortgage Viking Team
Licensed to Do Business | NMLS # 228246
This is not an offer to enter into an agreement. Not all customers will qualify. Information, rates and programs are subject to change without notice. All products are subject to credit and property approval. Other restrictions and limitations may apply. Copyright © 2021 | Medallion Funds
Corporate | NMLS ID NMLS # 1825831
Corporate Address : 2651 N. Green Valley Pkwy STE. 101 Henderson, NV 89014
Corporate NMLS NMLS # 1825831 | Company Website: https://medallionfunds.com/bill-rapp/
Copyright ©2021 | Mortgage Viking Team Licensed to Do Business | NMLS # 228246
This is not an offer to enter into an agreement. Not all customers will qualify. Information, rates and programs are subject to change without notice. All products are subject to credit and property approval. Other restrictions and limitations may apply
Corporate | NMLS ID NMLS # 1825831
Corporate Address : 2651 N. Green Valley Pkwy STE. 101 Henderson, NV 89014 https://medallionfunds.com/bill-rapp/
Facebook
Instagram
X
LinkedIn
Youtube
TikTok