Low Rates.
Our rates are low, our application is quick and easy! We can get you clear to close in as little as 10 days!
Trusted By Agents With
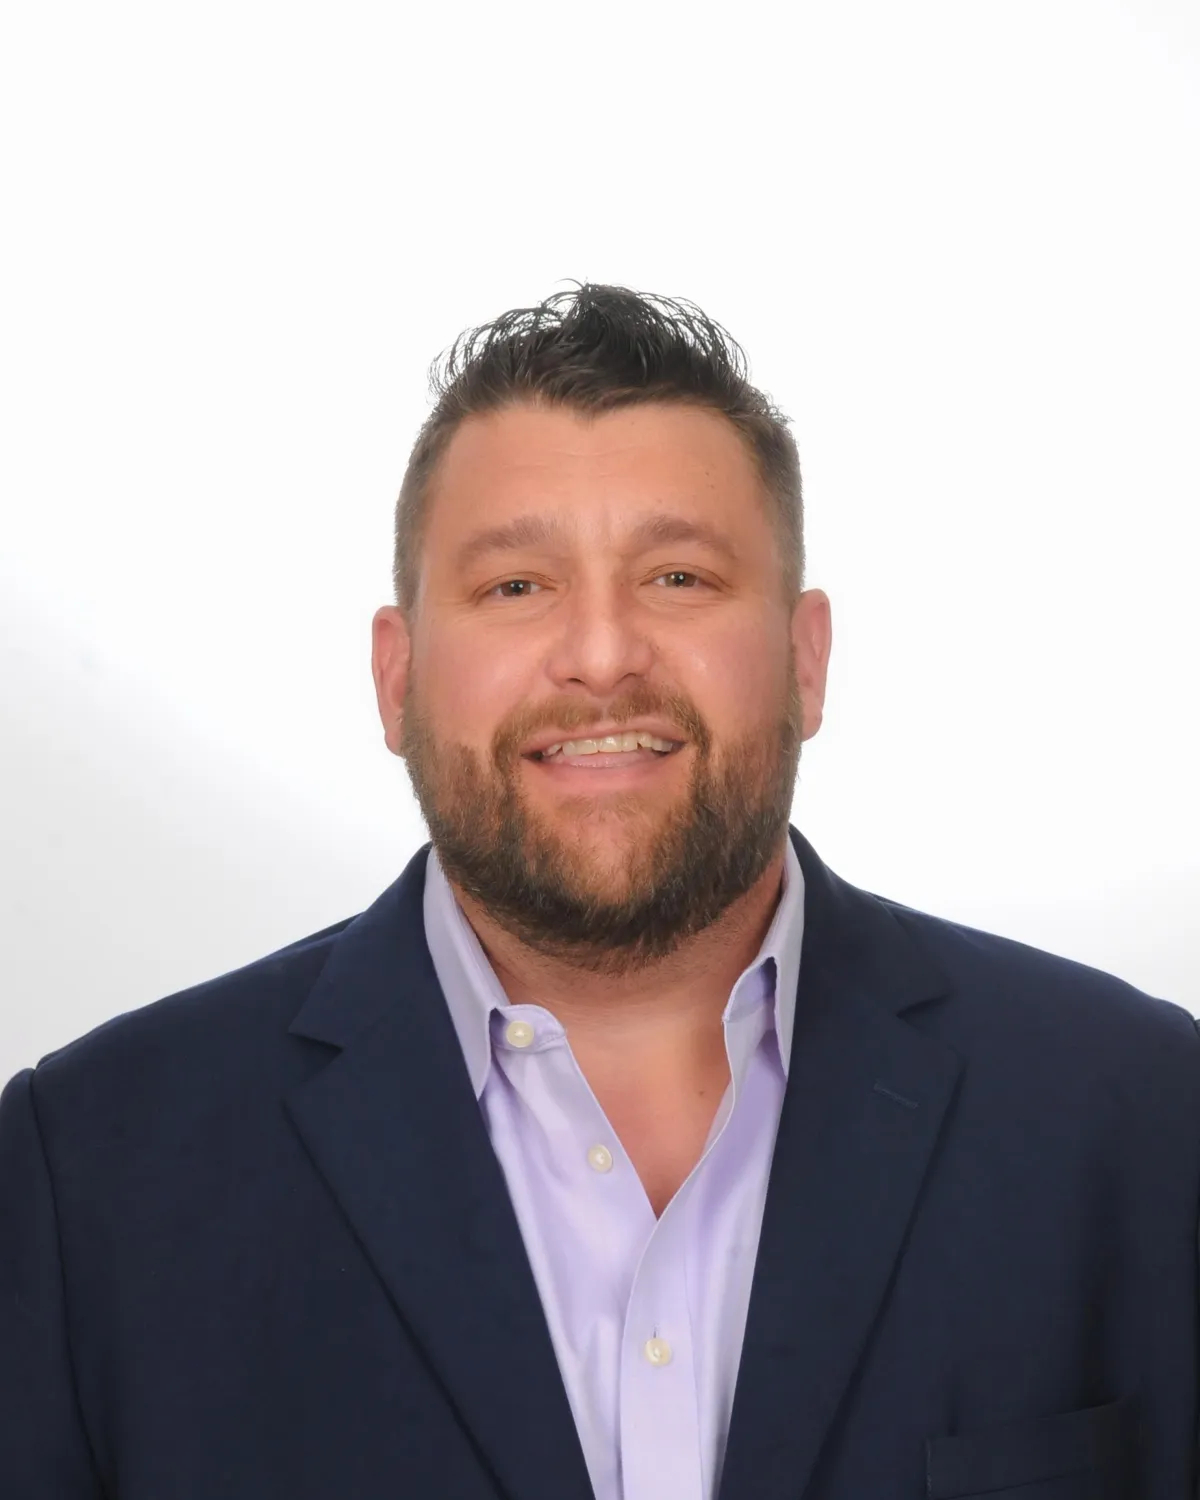
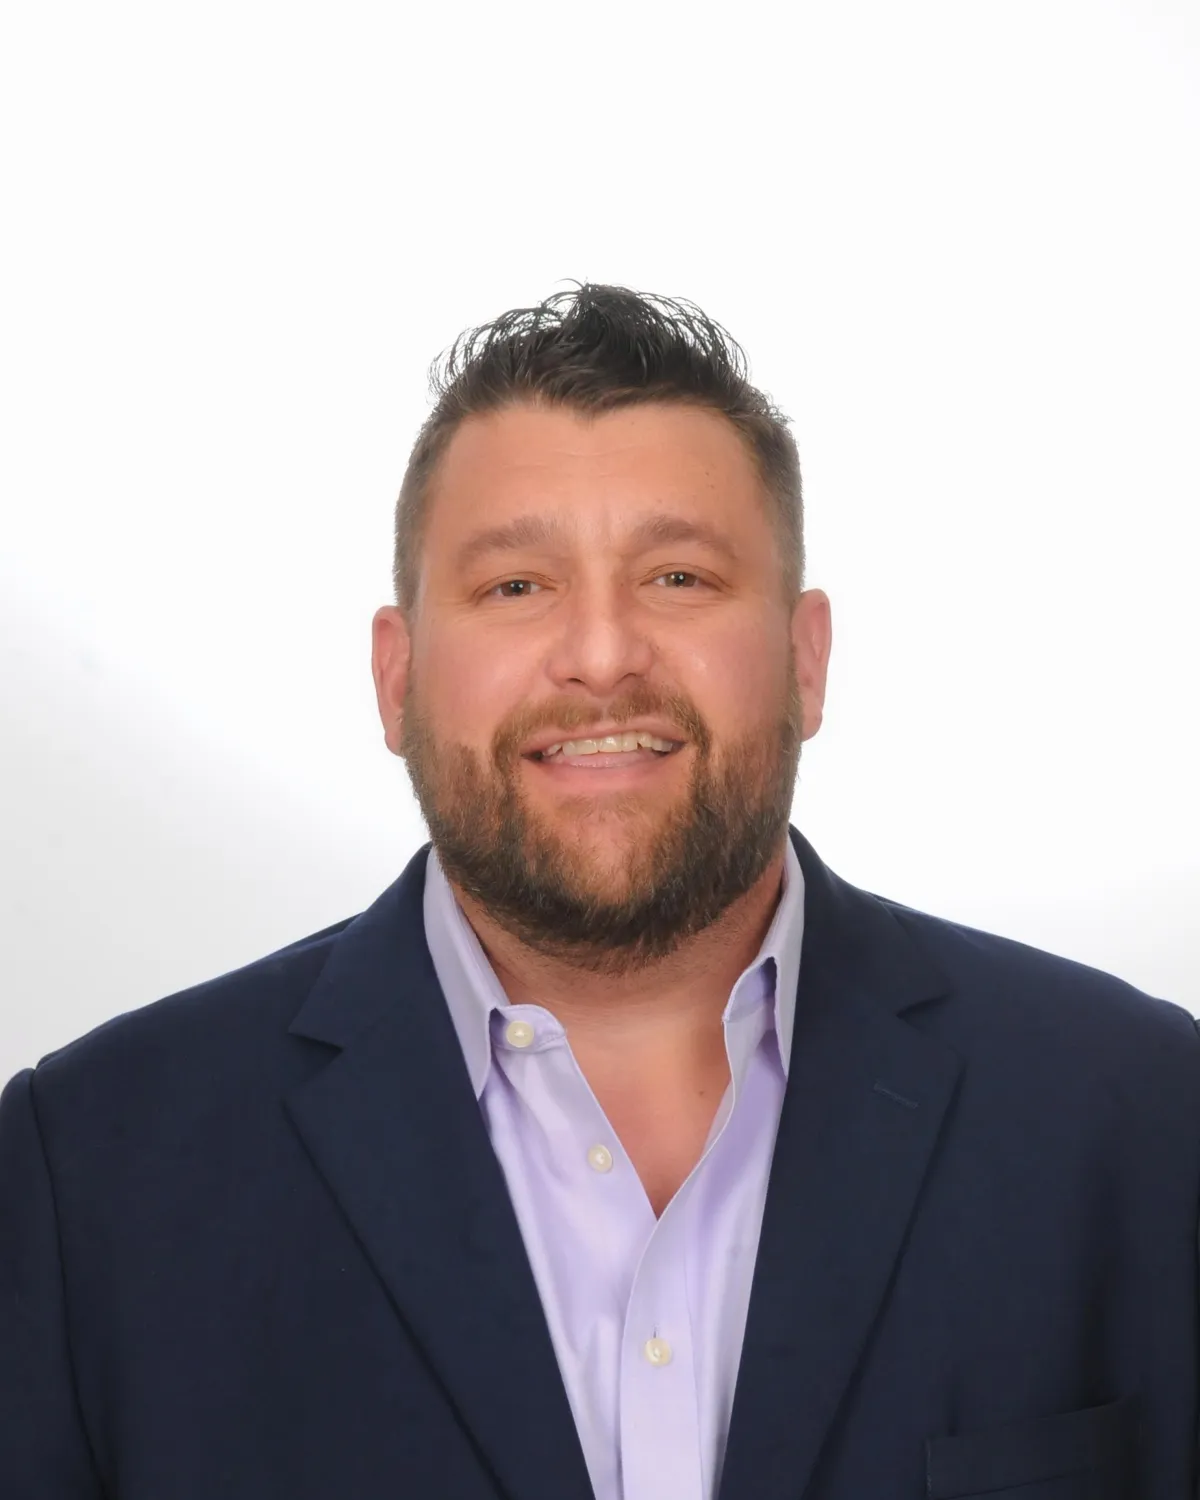
Meet Bill Rapp
NMLS ID # NMLS # 228246
Bill Rapp, CCIM is a Houston-based Capital Advisor at Medallion Funds, specializing in commercial real estate finance and strategic lending solutions. With over two decades of experience across brokerage and capital markets, Bill has worked with leading firms including eXp Commercial, NEXA Mortgage, Viking Enterprise LLC, and Sun Realty Houston.
A graduate of Texas A&M University with a BBA in Finance, Bill brings a disciplined, underwriting-first approach to every deal. His expertise spans commercial and residential financing, including asset-based lending, FHA financing, reverse mortgages, REO properties, and investment strategies for both single-family and commercial assets.
Known for his focus on structure over rate, Bill helps investors, business owners, and developers navigate complex transactions with clarity, precision, and a long-term wealth-building mindset.
The Client Experience
Great experience purchasing our first home! Bill was easy to reach and always able to answer any questions or concerns.
Loan Programs Available


Blogs
The Top 5 Mortgage Mistakes to Avoid
Buying your first home can be both exciting and nerve-wracking at the same time. With so many things to consider and....
Mortgage Do and
Do not list
Mortgages can be tricky, and it's easy to make mistakes that can end up costing you dearly. That's why we've put together this list....
Tips On How To Improve Your Credit Score
Let's talk about some ways you can improve your credit score! Your credit score is actually a big deal, and it can affect...
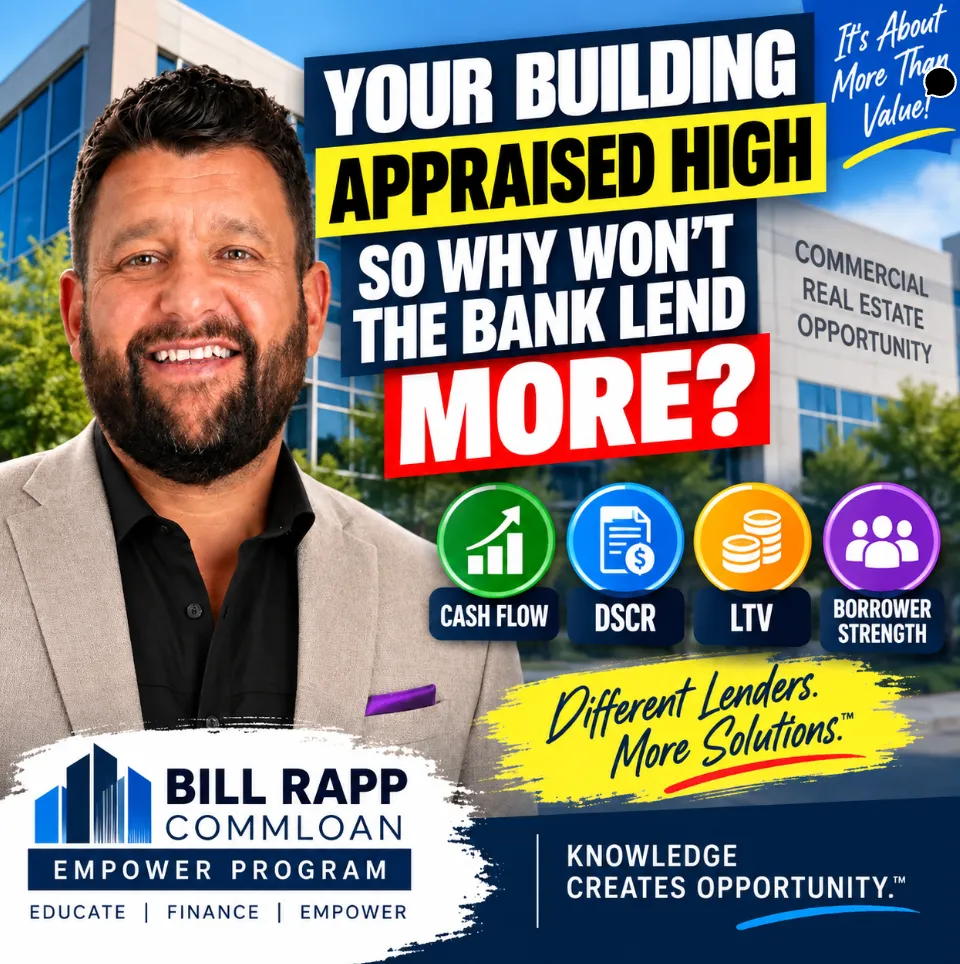
🏢 Your Building Appraised High—So Why Won’t the Bank Lend More? Understanding Commercial Loan Limits 💰
🏢 Your Building Appraised High—So Why Won’t the Bank Lend More? Understanding Commercial Loan Limits 💰
📊 High Commercial Property Value, Lower Loan Amount? Why DSCR Can Override Your Appraisal 🏦
________________________________________________________________________________
Your Building Appraised High—So Why Won’t the Bank Lend More?
You receive the commercial real estate appraisal and get good news.
Your property is worth more than expected.
Maybe the building appraises for $5 million, and you assume that a lender offering 70% loan-to-value could potentially lend $3.5 million.
Then the lender comes back with a much smaller loan amount.
What happened?
One of the biggest misconceptions in commercial real estate financing is that a strong appraisal automatically supports a larger commercial mortgage.
It doesn't.
Property value is only one component of commercial loan underwriting.
Depending on the property, borrower, loan program, and lender, the ultimate loan amount may be constrained by loan-to-value (LTV), debt service coverage ratio (DSCR), debt yield, borrower strength, liquidity, property performance, or lender-specific credit policies.
The limiting factor can determine how much you can actually borrow.
A High Appraisal Establishes Value—Not Repayment Capacity
An appraisal helps the lender evaluate the collateral supporting a commercial real estate loan.
Suppose a commercial property appraises for $5,000,000.
At 70% LTV:
$5,000,000 × 70% = $3,500,000
From an LTV perspective, a $3.5 million loan may appear supportable.
But the lender still has to answer a much more important credit question:
Does the property generate enough cash flow to service $3.5 million of debt?
That's where DSCR enters the equation.
DSCR Can Become the Real Loan Constraint
The debt service coverage ratio measures the relationship between a property's net operating income and its annual debt service.
The basic formula is:
DSCR = Net Operating Income ÷ Annual Debt Service
For example, if a property generates $300,000 of NOI and annual principal and interest payments are $240,000:
$300,000 ÷ $240,000 = 1.25x DSCR
A 1.25x DSCR means the property produces $1.25 of NOI for every $1.00 of debt service.
Individual lender requirements vary, but commercial lenders commonly establish minimum DSCR thresholds as part of their underwriting.
If the proposed loan produces debt service that exceeds what the property's NOI can support under the lender's required DSCR, the lender may reduce the loan—even when the appraisal supports substantially more leverage.
LTV and DSCR Are Two Different Tests
This distinction is critical for commercial real estate investors.
LTV asks: How large is the loan relative to the property's value?
DSCR asks: Can the property's cash flow support the required debt payments?
A property can perform extremely well under one test and poorly under another.
Imagine a property worth $5 million with relatively low NOI.
The appraisal could comfortably support a $3.5 million loan at 70% LTV. But if the property's NOI only supports $2.8 million under the lender's DSCR requirements, the lender may cap proceeds near $2.8 million.
In that situation, DSCR—not LTV—is effectively controlling the loan amount.
Interest Rates Can Reduce Loan Proceeds Without Changing Property Value
This becomes particularly important when interest rates rise.
Higher interest rates generally produce higher debt service on the same loan amount.
Higher debt service can weaken DSCR.
That means a property could have:
·the same appraised value,
·the same NOI,
·the same borrower,
·and the same LTV requirement,
yet potentially qualify for a smaller loan because the proposed debt has become more expensive to service.
This is why commercial real estate borrowers should evaluate cash flow and debt service capacity, not simply estimated property value.
Debt Yield Can Create Another Constraint
Some commercial lenders also evaluate debt yield.
Debt yield is generally calculated as:
NOI ÷ Loan Amount = Debt Yield
Unlike DSCR, debt yield does not directly incorporate the interest rate or amortization schedule.
For example, if a property produces $300,000 of NOI and the requested loan is $3 million:
$300,000 ÷ $3,000,000 = 10% debt yield
A lender's minimum debt-yield requirement can therefore create another ceiling on proceeds.
This creates three important underwriting measurements:
LTV → collateral value
DSCR → debt-service capacity
Debt Yield → NOI relative to loan exposure
Depending on the transaction and lender, one may become more restrictive than the others.
The Borrower Still Matters
Commercial real estate underwriting isn't limited to property-level ratios.
Lenders may also evaluate factors including borrower and guarantor credit, liquidity, net worth, experience, global cash flow, post-closing reserves, property type, tenant quality, lease rollover, occupancy, environmental risk, market conditions and concentration limits.
For owner-occupied properties, the operating company's financial performance can be particularly important because repayment may depend substantially on business cash flow.
A strong appraisal cannot necessarily compensate for weaknesses elsewhere in the credit profile.
Why Two Lenders May Offer Different Loan Amounts
This is also why commercial borrowers shouldn't assume every lender will reach the same conclusion.
Different lenders can have different:
·minimum DSCR requirements,
·maximum LTV limits,
·debt-yield thresholds,
·amortization schedules,
·interest rates,
·liquidity requirements,
·property-type appetites,
·geographic preferences,
·sponsor requirements,
·and credit policies.
One lender's maximum proceeds may therefore differ significantly from another lender's structure.
That doesn't mean underwriting standards disappear by shopping lenders. It means different capital sources may evaluate the same transaction under different parameters.
Start With the Deal, Not Just the Appraisal
Before asking, "What percentage of the appraisal will the bank lend?", consider asking:
"What loan amount can this property's cash flow reasonably support?"
Then evaluate that amount against LTV, debt yield, borrower strength and the lender's other underwriting requirements.
This approach provides a much more realistic picture of potential financing proceeds.
Commercial Lending Is About the Entire Capital Structure
A high appraisal is certainly useful. Strong collateral can improve a transaction's financing profile.
But commercial lending isn't simply:
Property Value × LTV = Loan Amount
The better framework is to analyze the entire transaction:
Value + NOI + DSCR + Debt Yield + Borrower + Liquidity + Loan Structure + Lender Criteria
The ultimate financing structure depends on how those pieces interact.
That's also where a marketplace approach to commercial mortgage brokerage can add value. Instead of evaluating a transaction through only one institution's credit box, borrowers can explore potential capital sources and determine which financing structures align with the property's performance and their objectives.
Knowledge Creates Opportunity.™
Top of Form
Bottom of Form
Bill Rapp, CCIM
Director | CommLoan
📞 281-222-0433
📧 [email protected]
🌐 https://billrapp.commloan.com/
🌐 https://HoustonCommercialMortgage.com/
Commercial Real Estate Financing Nationwide
https://billrapp.commloan.com/
https://author.billrapponline.com/
https://www.amazon.com/dp/B0F32Z5BH2
https://veed.cello.so/FOmzTty6oi9
https://buymeacoffee.com/vikingente3
https://creplaybookseries.billrapponline.com
https://creplaybook.billrapponline.com/
©Bill Rapp, CCIM - Director - CommLoan
10 Tips for First-Time Homebuyers
Buying your first home can be both exciting and nerve-wracking at the same time. With so many things to consider and....
How To Choose the Right Lender for You
Lorem Ipsum is simply dummy text of the printing and typesetting industry. Lorem Ipsum has been the industry's standard dummy
Refinancing youe loan and when to do it
Lorem Ipsum is simply dummy text of the printing and typesetting industry. Lorem Ipsum has been the industry's standard dummy
Copyright ©2021 | Mortgage Viking Team
Licensed to Do Business | NMLS # 228246
This is not an offer to enter into an agreement. Not all customers will qualify. Information, rates and programs are subject to change without notice. All products are subject to credit and property approval. Other restrictions and limitations may apply. Copyright © 2021 | Medallion Funds
Corporate | NMLS ID NMLS # 1825831
Corporate Address : 2651 N. Green Valley Pkwy STE. 101 Henderson, NV 89014
Corporate NMLS NMLS # 1825831 | Company Website: https://medallionfunds.com/bill-rapp/
Copyright ©2021 | Mortgage Viking Team Licensed to Do Business | NMLS # 228246
This is not an offer to enter into an agreement. Not all customers will qualify. Information, rates and programs are subject to change without notice. All products are subject to credit and property approval. Other restrictions and limitations may apply
Corporate | NMLS ID NMLS # 1825831
Corporate Address : 2651 N. Green Valley Pkwy STE. 101 Henderson, NV 89014 https://medallionfunds.com/bill-rapp/
Facebook
Instagram
X
LinkedIn
Youtube
TikTok