Low Rates.
Our rates are low, our application is quick and easy! We can get you clear to close in as little as 10 days!
Trusted By Agents With
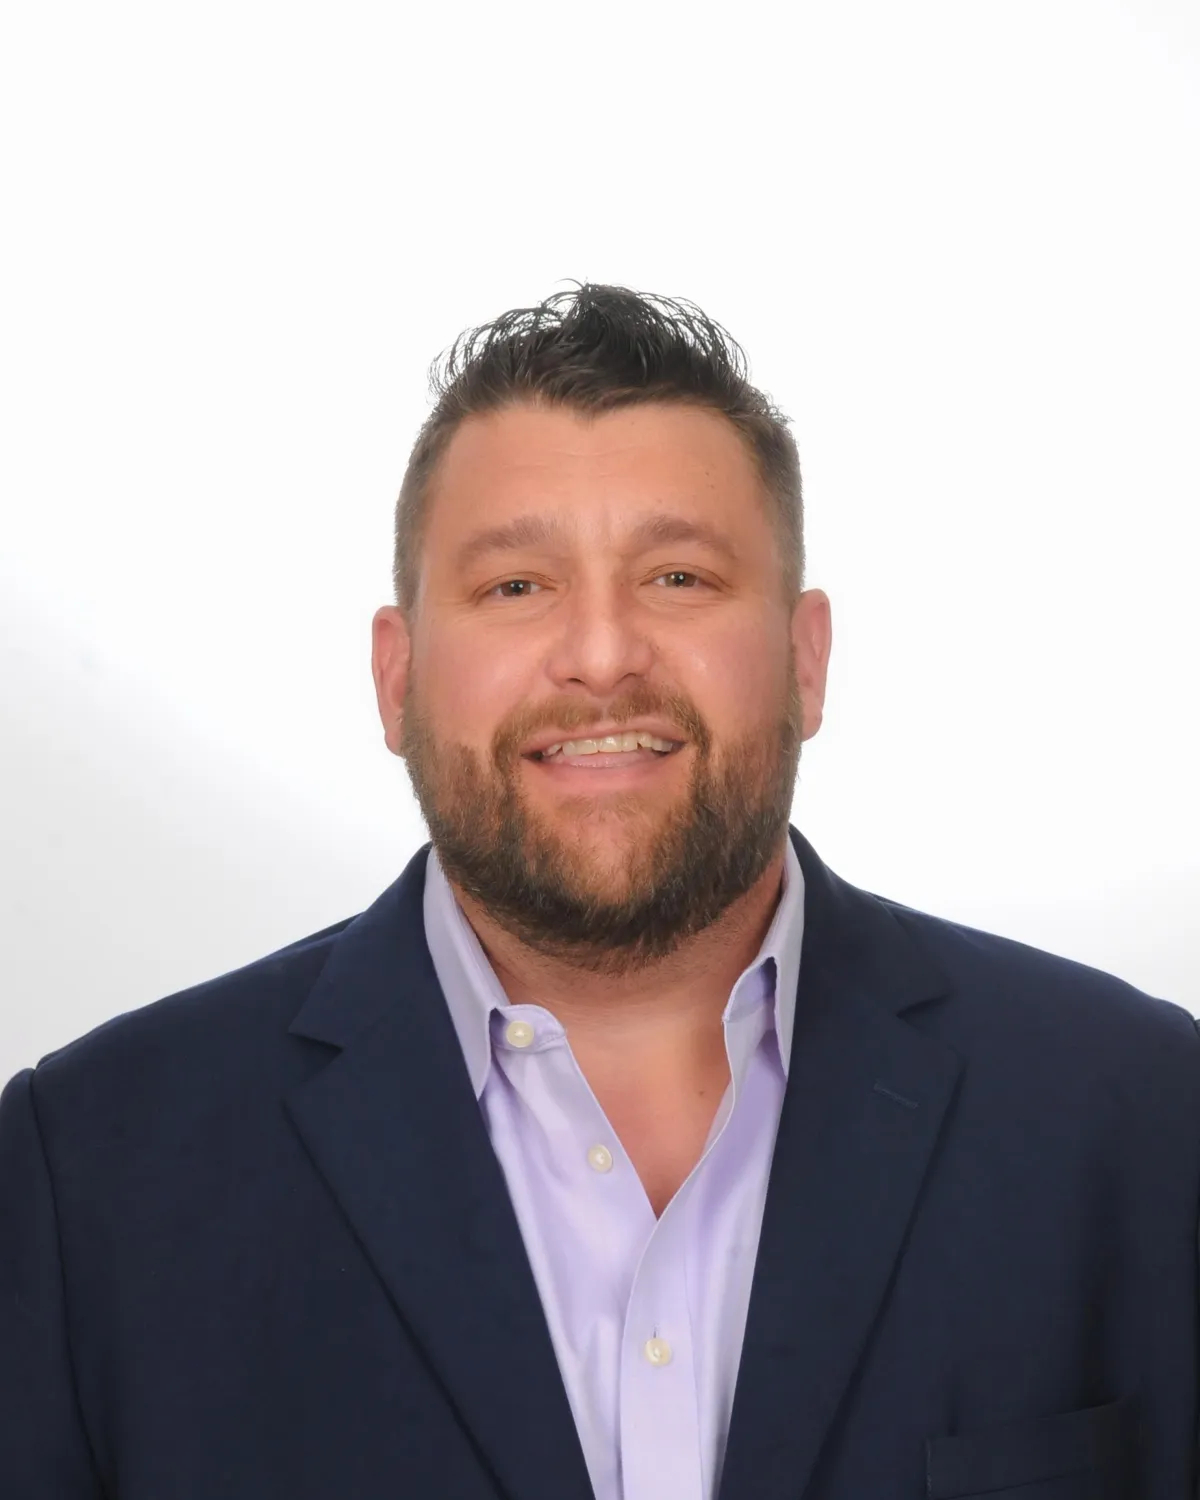
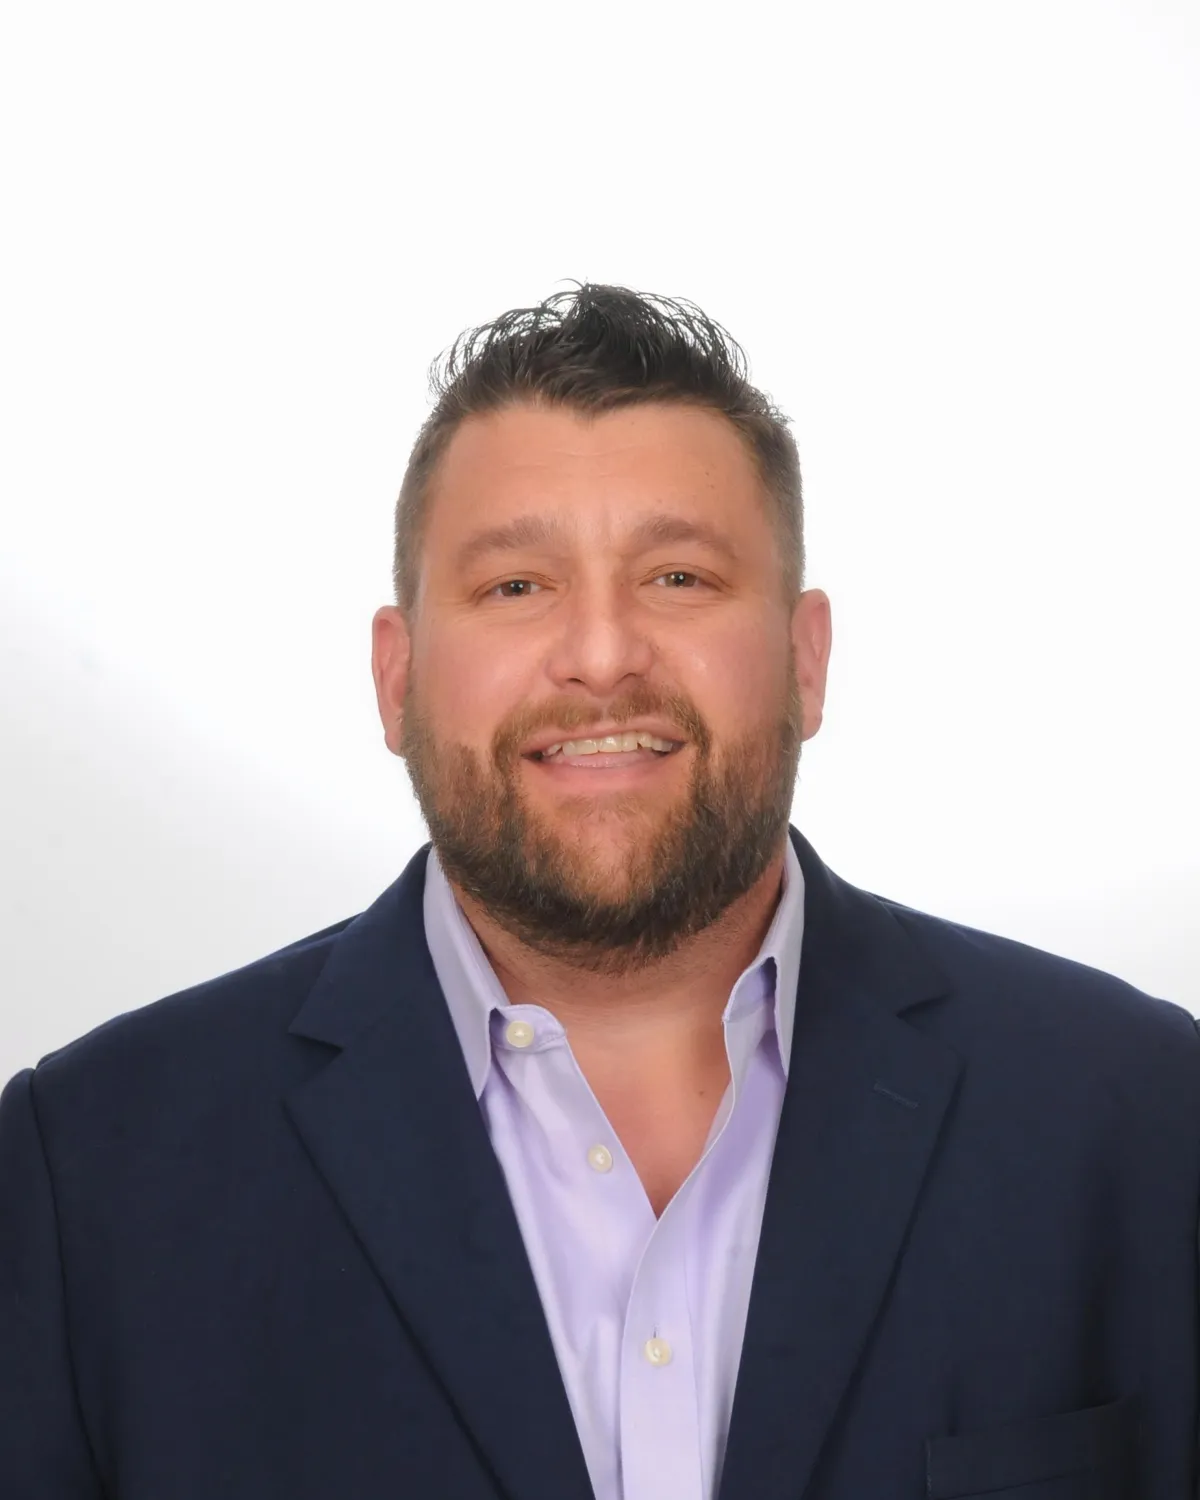
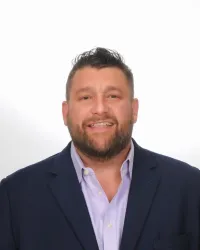
Meet Bill Rapp
NMLS ID # NMLS # 228246
Bill Rapp, CCIM is a Houston-based Capital Advisor at Medallion Funds, specializing in commercial real estate finance and strategic lending solutions. With over two decades of experience across brokerage and capital markets, Bill has worked with leading firms including eXp Commercial, NEXA Mortgage, Viking Enterprise LLC, and Sun Realty Houston.
A graduate of Texas A&M University with a BBA in Finance, Bill brings a disciplined, underwriting-first approach to every deal. His expertise spans commercial and residential financing, including asset-based lending, FHA financing, reverse mortgages, REO properties, and investment strategies for both single-family and commercial assets.
Known for his focus on structure over rate, Bill helps investors, business owners, and developers navigate complex transactions with clarity, precision, and a long-term wealth-building mindset.
The Client Experience
Great experience purchasing our first home! Bill was easy to reach and always able to answer any questions or concerns.

Loan Programs Available
Blogs
The Top 5 Mortgage Mistakes to Avoid
Buying your first home can be both exciting and nerve-wracking at the same time. With so many things to consider and....
Mortgage Do and
Do not list
Mortgages can be tricky, and it's easy to make mistakes that can end up costing you dearly. That's why we've put together this list....
Tips On How To Improve Your Credit Score
Let's talk about some ways you can improve your credit score! Your credit score is actually a big deal, and it can affect...
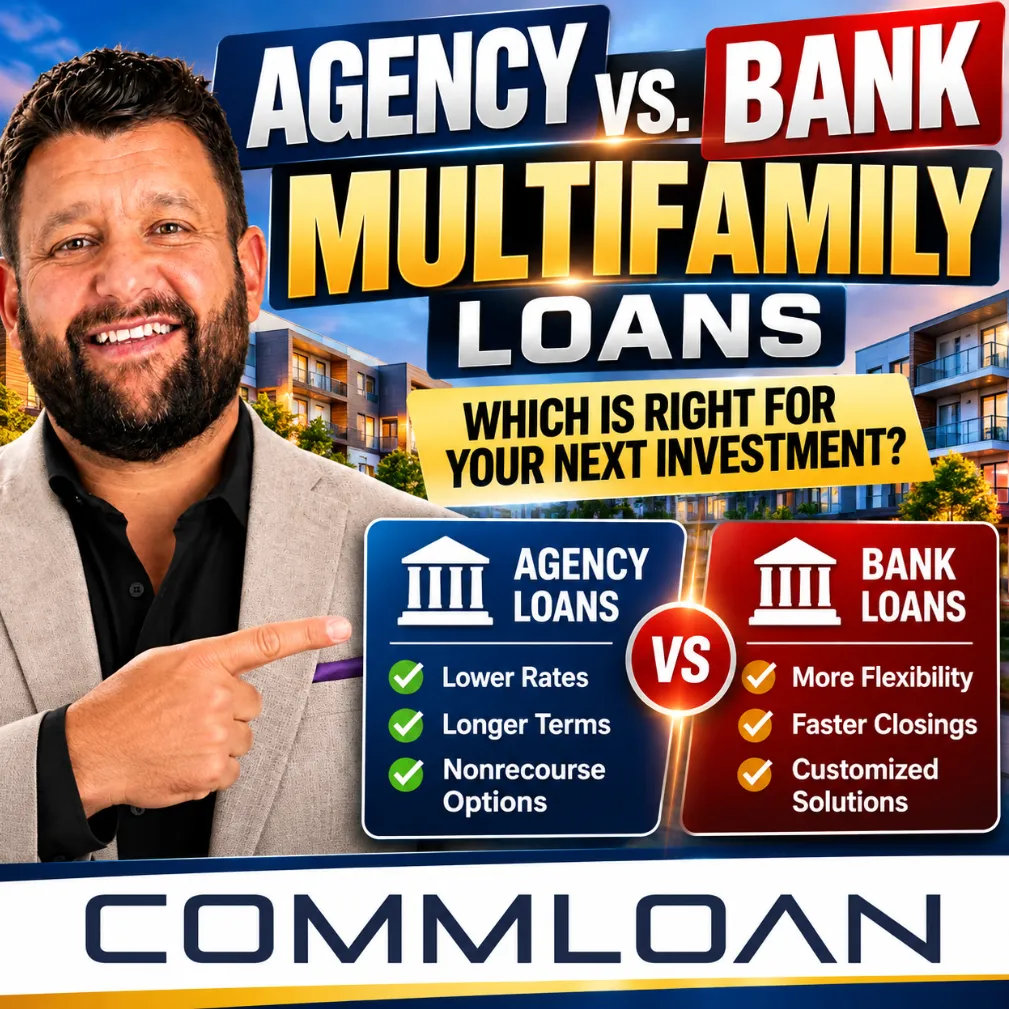
🏢 Agency vs. Bank Multifamily Loans: Which Financing Option Is Best for Apartment Investors? 💰
🏢 Agency vs. Bank Multifamily Loans: Which Financing Option Is Best for Apartment Investors? 💰
💵 Fannie Mae & Freddie Mac vs. Bank Loans: 7 Multifamily Financing Differences Investors Must Know 🏦
_______________________________________________________________________________
Agency vs. Bank Multifamily Loans: Which Financing Option Is Best for Apartment Investors?
When financing a multifamily investment property, choosing the right lender can be just as important as negotiating the purchase price.
Two of the most common financing options for apartment investors are Agency multifamily loans, primarily through Fannie Mae and Freddie Mac, and conventional commercial bank loans.
Both can finance apartment acquisitions and refinances. However, their differences in interest rates, loan terms, amortization, prepayment penalties, recourse requirements, and underwriting standards can significantly affect your investment returns.
So which financing option makes the most sense for your next multifamily investment?
Let's examine the differences.
What Is an Agency Multifamily Loan?
An Agency multifamily loan is commercial real estate financing originated through an approved lender under programs associated with Fannie Mae or Freddie Mac.
These programs typically finance stabilized multifamily properties containing five or more residential units.
Common Agency financing programs include:
Fannie Mae DUS Loans: Multifamily financing through approved Delegated Underwriting and Servicing lenders.
Freddie Mac Conventional Loans: Financing for qualifying stabilized apartment communities.
Freddie Mac Small Balance Loans: Financing designed for eligible smaller multifamily properties, generally within a $1 million to $7.5 million loan range, subject to current program requirements.
Agency financing is especially popular with experienced multifamily investors seeking long-term debt, competitive pricing, and potentially nonrecourse financing.
Unlike a traditional bank loan, Agency financing may allow investors to reduce personal repayment liability while maintaining predictable financing costs.
However, nonrecourse does not mean zero liability. Standard carve-outs for fraud, misrepresentation, environmental issues, and certain prohibited actions may still apply.
What Is a Conventional Bank Multifamily Loan?
A conventional bank multifamily loan is commercial real estate financing provided by a bank or other portfolio lender.
Banks may retain the loan on their balance sheet, allowing greater flexibility in underwriting and structuring certain transactions.
Bank multifamily loans are commonly used for:
Apartment acquisitions
Cash-out and rate-and-term refinances
Smaller multifamily investments
Properties requiring renovation or repositioning
Transitional or partially stabilized properties
Local real estate investment opportunities
Banks may evaluate both property-level cash flow and the borrower's overall financial strength.
This can make bank financing attractive when the investment does not fit standard Agency underwriting requirements.
However, bank loans frequently require personal guarantees and may expose borrowers to refinancing risk at maturity.
Agency vs. Bank Multifamily Loans: Seven Key Differences
1. Interest Rates and Loan Pricing
Agency multifamily financing can offer competitive interest rates for stabilized apartment properties.
Pricing depends on factors such as leverage, debt service coverage, property location, loan size, market conditions, and loan structure.
Bank financing may offer equally competitive or even better pricing in certain situations, particularly for borrowers with strong banking relationships.
Investor takeaway: Compare the full cost of financing, not simply the advertised interest rate. Evaluate origination fees, lender charges, reserves, prepayment costs, and anticipated holding periods.
2. Loan Terms and Amortization
Agency multifamily programs commonly offer loan terms ranging from approximately five to ten years, with certain programs offering longer structures.
Amortization periods of up to 30 years are common, depending on the program.
Bank loans may offer shorter fixed-rate or maturity periods, often three, five, or seven years, even when payments are calculated using a 20- to 30-year amortization schedule.
This distinction is important.
A five-year bank loan with 25-year amortization may require the borrower to refinance or repay the remaining principal balance at the end of year five.
Investor takeaway: Longer amortization can improve annual cash flow, while longer loan maturity can reduce near-term refinancing exposure.
3. Recourse vs. Nonrecourse Financing
One of the biggest potential advantages of Agency financing is access to nonrecourse debt.
With qualifying nonrecourse financing, the lender generally relies primarily on the pledged property as collateral, subject to contractual carve-outs.
Traditional bank loans frequently require personal guarantees from principals or sponsors.
For investors building larger apartment portfolios, recourse exposure can become an important consideration.
Investor takeaway: Evaluate both the economic cost of the loan and the personal liability associated with the financing structure.
4. Debt Service Coverage Ratio Requirements
Debt service coverage ratio, or DSCR, measures a property's ability to generate sufficient net operating income to cover its debt payments.
The formula is:
DSCR = Net Operating Income ÷ Annual Debt Service
For example, suppose an apartment building generates $600,000 in annual net operating income and requires $480,000 in annual debt payments.
The DSCR would be:
$600,000 ÷ $480,000 = 1.25x DSCR
That means the property generates $1.25 in net operating income for every $1.00 of scheduled debt service.
Agency programs commonly target DSCR levels around 1.25x or higher for many conventional transactions, although specific minimums vary by program and risk profile.
Banks may apply different requirements based on the asset, borrower, guarantees, and overall relationship.
Investor takeaway: Strong DSCR can improve financing options, but the lender's underwriting methodology matters just as much as the reported number.
5. Loan-to-Value Ratio
Loan-to-value ratio, or LTV, measures the loan amount relative to the property's appraised value.
LTV = Loan Amount ÷ Appraised Property Value
A $7 million loan against a $10 million apartment property represents 70% LTV.
Agency programs may permit leverage up to approximately 75%–80% on qualifying transactions, depending on program limits, DSCR, market, and property characteristics.
Bank leverage is lender-specific and may be more conservative, although exceptions exist.
Importantly, the maximum permitted LTV does not guarantee that a borrower will qualify for that amount.
The final loan may be constrained by DSCR, debt yield, property performance, and lender underwriting.
6. Prepayment Penalties and Exit Flexibility
Agency multifamily loans frequently include structured prepayment provisions.
Depending on the program, these may involve yield maintenance, defeasance, or other prepayment schedules.
These provisions can create substantial costs if the investor sells or refinances before the anticipated payoff date.
Bank loans may offer more negotiable prepayment terms, including step-down penalties or other arrangements.
Investor takeaway: Match the financing structure to your business plan.
An investor planning to sell after three years should evaluate financing differently from an investor planning to hold the property for fifteen years.
7. Property Condition, Stabilization, and Borrower Experience
Agency lenders generally prefer properties that satisfy program requirements for occupancy, physical condition, financial performance, and stabilization.
Bank lenders may have greater flexibility for properties undergoing renovations, lease-up, or operational improvements.
For example, a partially vacant apartment complex with deferred maintenance may not immediately qualify for permanent Agency financing.
A bank or bridge lender could potentially provide acquisition or transitional financing while the investor completes improvements.
Once the property is stabilized, Agency refinancing may become an option.
Investor takeaway: Financing should align with the property's current condition and the investor's future business plan.
Agency vs. Bank Multifamily Loans: Side-by-Side Comparison
Financing Feature | Agency Multifamily Loan | Conventional Bank Loan |
Typical property | Stabilized 5+ unit multifamily | Stabilized or transitional multifamily |
Loan maturity | Often 5–10 years; longer options available | Often 3–7 years; varies |
Amortization | Often up to 30 years | Commonly 20–30 years |
Recourse | Often nonrecourse with carve-outs | Often recourse |
DSCR | Program-specific; often around 1.25x+ | Bank-specific |
LTV | May reach 75%–80% on eligible transactions | Bank-specific |
Prepayment | May include yield maintenance or defeasance | Often more negotiable |
Renovation flexibility | Generally more limited for conventional stabilized programs | Potentially more flexible |
Underwriting | Program-driven | Relationship and lender-driven |
These are illustrative market conventions, not guaranteed program terms or financing offers. Current lender guidelines control.
Real-World Example: Financing a $10 Million Apartment Building
Let's assume an investor is acquiring a stabilized apartment complex for $10 million.
The property generates $650,000 in annual net operating income.
The investor is considering two hypothetical financing options.
Option A: Agency Multifamily Financing
Loan amount: $7,000,000
Interest rate: 6.00%
Amortization: 30 years
Loan maturity: 10 years
Recourse: Nonrecourse, subject to carve-outs
Estimated annual debt service: $503,600
Estimated DSCR: 1.29x
Estimated annual cash flow before taxes, capital expenditures, and other below-NOI items: $146,400
Option B: Conventional Bank Financing
Loan amount: $7,000,000
Interest rate: 6.25%
Amortization: 25 years
Loan maturity: 5 years
Recourse: Personal guarantee assumed
Estimated annual debt service: $554,100
Estimated DSCR: 1.17x
Estimated annual cash flow before taxes, capital expenditures, and other below-NOI items: $95,900
In this simplified example, the Agency structure produces approximately $50,500 more annual cash flow.
However, this does not automatically make Agency financing the better choice.
The Agency loan may include more restrictive prepayment provisions, while the bank may offer flexibility that better supports the investor's exit strategy.
Additionally, the bank's 1.17x DSCR could fall below its required minimum, potentially reducing the available loan amount.
The correct decision depends on actual loan quotes, underwriting approval, fees, reserves, and the intended holding period.
When Should Investors Choose Agency Financing?
Agency financing may be particularly attractive when:
The apartment property is stabilized.
The investor plans to hold the property for several years.
Predictable debt service is a priority.
Nonrecourse financing is important.
The property supports Agency underwriting requirements.
The investor wants to minimize near-term refinancing exposure.
When Should Investors Consider Bank Financing?
Bank financing may make more sense when:
The property needs renovations or repositioning.
The investor has a strong existing banking relationship.
The transaction requires customized underwriting.
The business plan involves a relatively short holding period.
The property does not meet Agency stabilization requirements.
Flexible prepayment or loan structuring is particularly valuable.
Can Investors Start With a Bank Loan and Refinance Into Agency Debt?
Yes. This is a common financing strategy for certain value-add multifamily investments.
An investor may acquire a property using bank or bridge financing, improve operations, increase occupancy, and stabilize net operating income.
Once the property qualifies for permanent financing, the investor may refinance into an Agency loan.
However, refinancing is never guaranteed.
Investors should evaluate interest-rate sensitivity, valuation risk, debt service coverage, prepayment costs, and future lending standards before relying on this strategy.
How the CommLoan Empower Program Helps Investors Compare Financing
Commercial multifamily financing is rarely one-size-fits-all.
Through the CommLoan Empower Program, I help investors evaluate financing alternatives and identify lenders whose underwriting requirements align with the property and investment strategy.
The objective is not simply to find a loan.
It is to identify financing that supports the investment's cash flow, capital structure, risk tolerance, and exit plan.
Whether you are purchasing a stabilized apartment community, refinancing an existing portfolio, or evaluating a value-add acquisition, comparing financing structures can help you make a more informed decision.
Final Thoughts: Which Multifamily Loan Is Better?
Agency loans can be an excellent option for stabilized multifamily investments, particularly when long-term financing and nonrecourse structures are priorities.
Bank loans may offer greater flexibility for transitional properties, relationship-based transactions, and specialized financing needs.
Neither option is universally better.
The best multifamily loan is the one that supports your property's financial performance and your investment strategy—not simply the one advertising the lowest rate.
Ready to compare your multifamily financing options?
I'm Bill Rapp, CCIM, with the CommLoan Empower Program.
Top of Form
Bottom of Form
Bill Rapp, CCIM
Director | CommLoan
📞 281-222-0433
📧 [email protected]
🌐 https://billrapp.commloan.com/
🌐 https://HoustonCommercialMortgage.com/
Commercial Real Estate Financing Nationwide
https://billrapp.commloan.com/
https://author.billrapponline.com/
https://www.amazon.com/dp/B0F32Z5BH2
https://veed.cello.so/FOmzTty6oi9
https://buymeacoffee.com/vikingente3
https://creplaybookseries.billrapponline.com
https://creplaybook.billrapponline.com/
©Bill Rapp, CCIM - Director - CommLoan
10 Tips for First-Time Homebuyers
Buying your first home can be both exciting and nerve-wracking at the same time. With so many things to consider and....
How To Choose the Right Lender for You
Lorem Ipsum is simply dummy text of the printing and typesetting industry. Lorem Ipsum has been the industry's standard dummy
Refinancing youe loan and when to do it
Lorem Ipsum is simply dummy text of the printing and typesetting industry. Lorem Ipsum has been the industry's standard dummy
Copyright ©2021 | Mortgage Viking Team
Licensed to Do Business | NMLS # 228246
This is not an offer to enter into an agreement. Not all customers will qualify. Information, rates and programs are subject to change without notice. All products are subject to credit and property approval. Other restrictions and limitations may apply. Copyright © 2021 | Medallion Funds
Corporate | NMLS ID NMLS # 1825831
Corporate Address : 2651 N. Green Valley Pkwy STE. 101 Henderson, NV 89014
Corporate NMLS NMLS # 1825831 | Company Website: https://medallionfunds.com/bill-rapp/
Copyright ©2021 | Mortgage Viking Team Licensed to Do Business | NMLS # 228246
This is not an offer to enter into an agreement. Not all customers will qualify. Information, rates and programs are subject to change without notice. All products are subject to credit and property approval. Other restrictions and limitations may apply
Corporate | NMLS ID NMLS # 1825831
Corporate Address : 2651 N. Green Valley Pkwy STE. 101 Henderson, NV 89014 https://medallionfunds.com/bill-rapp/
Facebook
Instagram
X
LinkedIn
Youtube
TikTok