Low Rates.
Our rates are low, our application is quick and easy! We can get you clear to close in as little as 10 days!
Trusted By Agents With
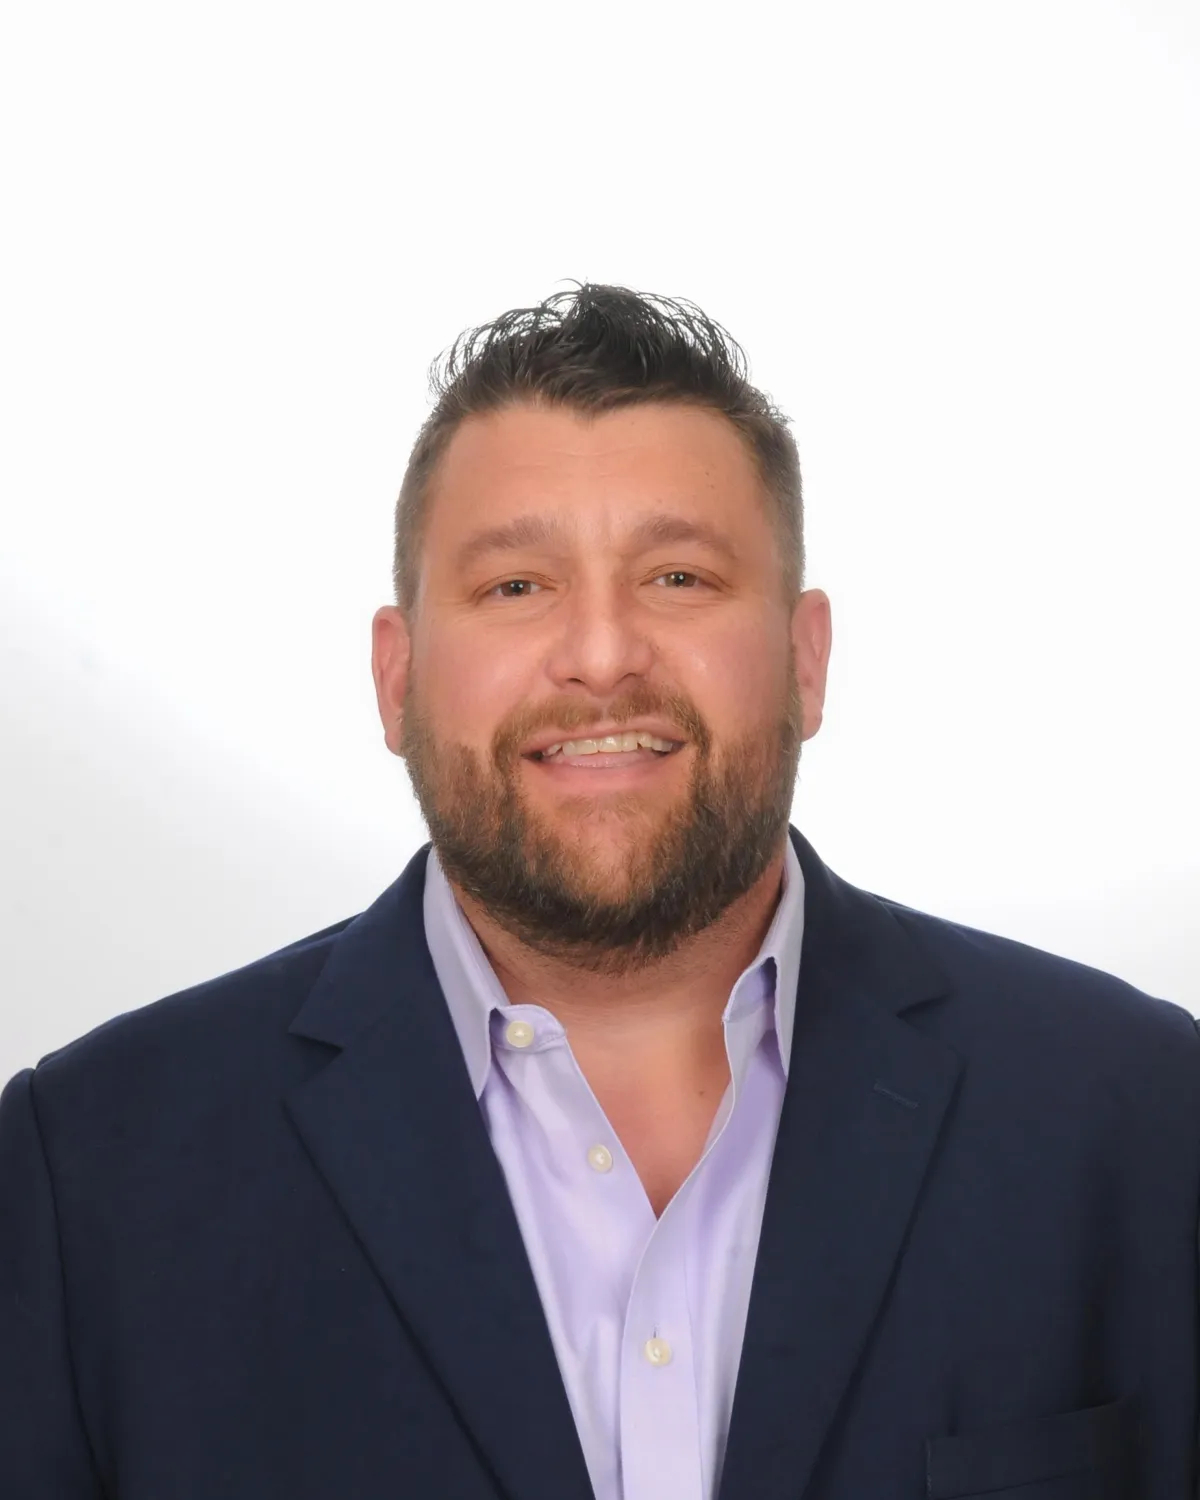
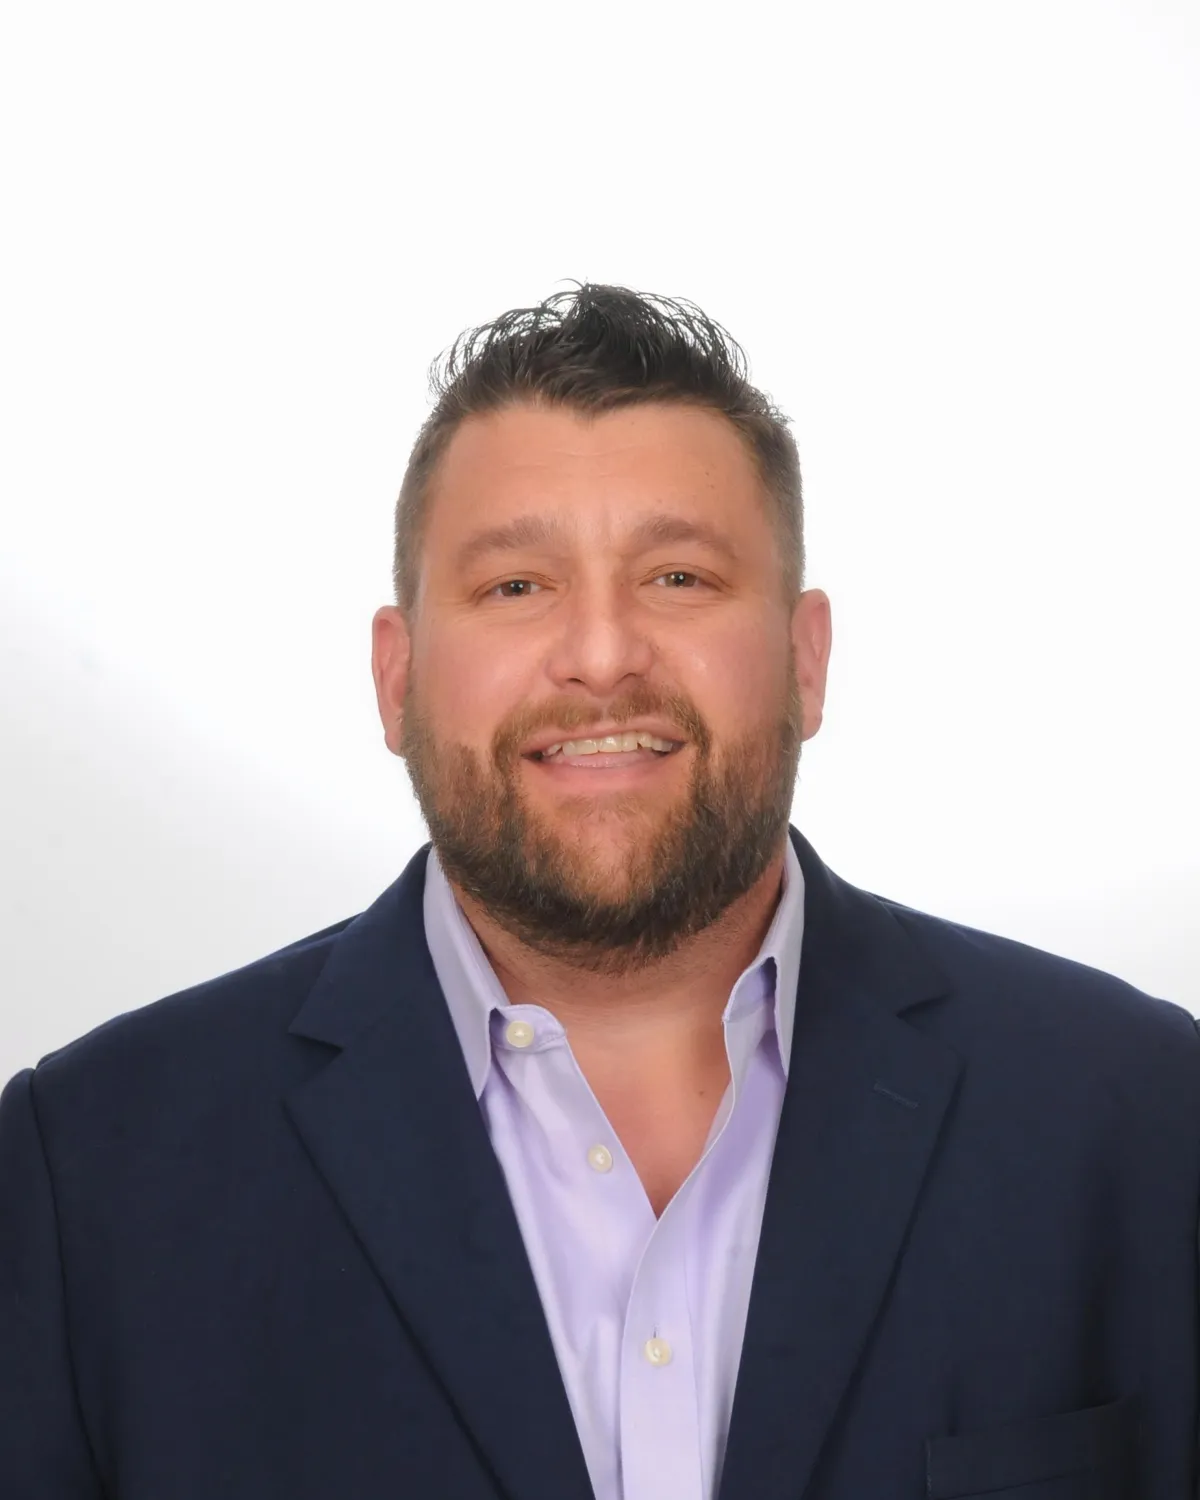
Meet Bill Rapp
NMLS ID # NMLS # 228246
Bill Rapp, CCIM is a Houston-based Capital Advisor at Medallion Funds, specializing in commercial real estate finance and strategic lending solutions. With over two decades of experience across brokerage and capital markets, Bill has worked with leading firms including eXp Commercial, NEXA Mortgage, Viking Enterprise LLC, and Sun Realty Houston.
A graduate of Texas A&M University with a BBA in Finance, Bill brings a disciplined, underwriting-first approach to every deal. His expertise spans commercial and residential financing, including asset-based lending, FHA financing, reverse mortgages, REO properties, and investment strategies for both single-family and commercial assets.
Known for his focus on structure over rate, Bill helps investors, business owners, and developers navigate complex transactions with clarity, precision, and a long-term wealth-building mindset.
The Client Experience
Great experience purchasing our first home! Bill was easy to reach and always able to answer any questions or concerns.
Loan Programs Available


Blogs
The Top 5 Mortgage Mistakes to Avoid
Buying your first home can be both exciting and nerve-wracking at the same time. With so many things to consider and....
Mortgage Do and
Do not list
Mortgages can be tricky, and it's easy to make mistakes that can end up costing you dearly. That's why we've put together this list....
Tips On How To Improve Your Credit Score
Let's talk about some ways you can improve your credit score! Your credit score is actually a big deal, and it can affect...
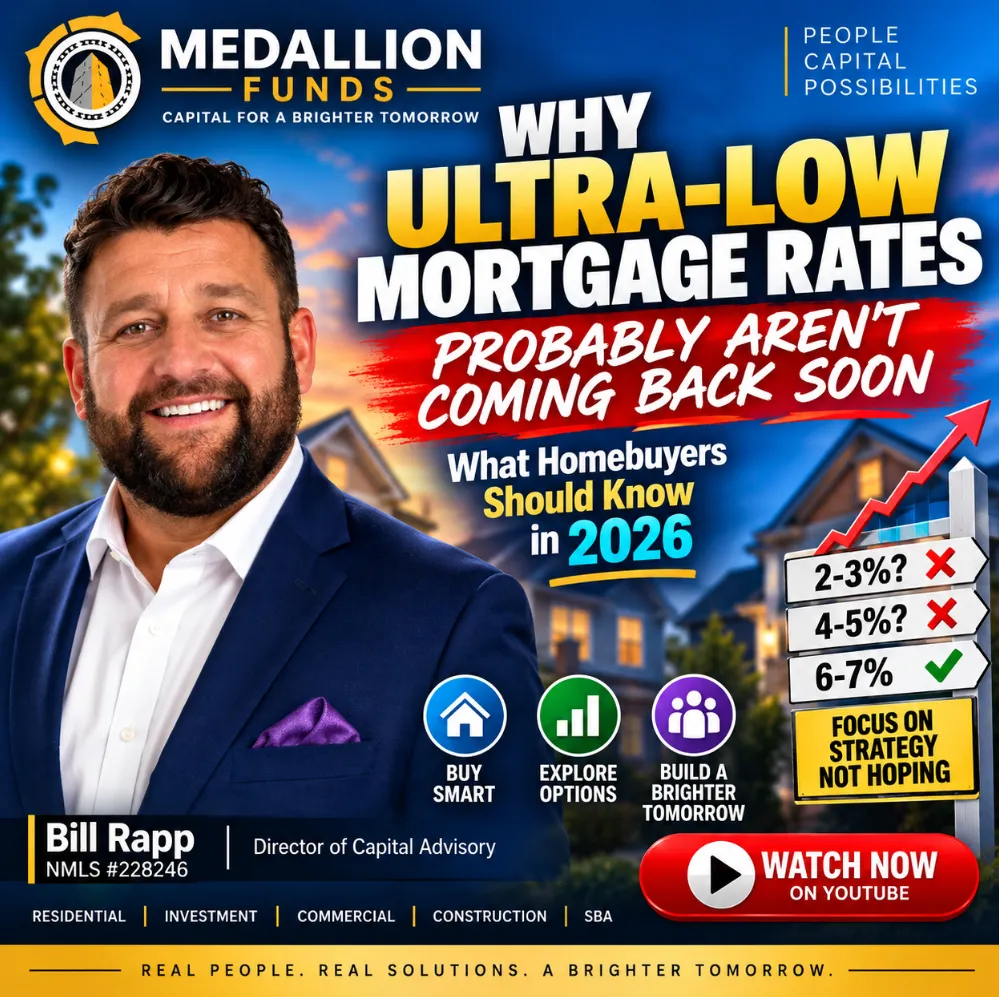
🏠 Why Ultra-Low Mortgage Rates Probably Aren't Coming Back Soon — What Homebuyers Should Do Instead 📈
🏠 Why Ultra-Low Mortgage Rates Probably Aren't Coming Back Soon — What Homebuyers Should Do Instead 📈
📉 Waiting for 3% Mortgage Rates? Why Today's Higher-Rate Market May Be the New Normal 🏡
________________________________________________________________________________
Why Ultra-Low Mortgage Rates Probably Aren't Coming Back Soon
For millions of homeowners and homebuyers, mortgage rates of 2%, 3%, and even the low-4% range became psychologically anchored as "normal."
They weren't.
The ultra-low mortgage rates experienced during the pandemic were the product of an extraordinary combination of economic conditions and monetary policy. Buyers waiting for those rates to return before purchasing a home could potentially be waiting for an environment that doesn't return anytime soon.
That doesn't mean mortgage rates can't decline.
It means there is an important difference between mortgage rates moving lower and mortgage rates returning to pandemic-era lows.
And understanding that difference can help homebuyers make better financial decisions.
Where Mortgage Rates Are Now
As of September 17, 2026, Freddie Mac reported that the average 30-year fixed mortgage rate was 6.95%, compared with 6.26% one year earlier.
Mortgage rates can move quickly as financial markets react to inflation, economic growth, employment, Federal Reserve policy, Treasury yields, and investor expectations.
That's why trying to perfectly time the mortgage market can be difficult.
More importantly, current forecasts don't necessarily point toward an imminent return to ultra-low rates. Fannie Mae's September 2026 housing forecast projects the 30-year fixed mortgage averaging approximately 6.8% during Q4 2026 and 6.7% for 2027.
Forecasts can change, but today's expectations illustrate an important point:
Lower rates don't necessarily mean 3% rates.
Why Were Mortgage Rates So Low in the First Place?
To understand why ultra-low mortgage rates may not return soon, it helps to understand why they became so low.
The pandemic produced an extraordinary economic shock.
Policymakers responded with aggressive measures designed to support financial markets and the economy. Interest rates fell sharply, and the Federal Reserve purchased large quantities of Treasury securities and agency mortgage-backed securities.
That environment helped push mortgage borrowing costs to historic lows.
Those weren't ordinary economic conditions.
That's an important distinction for anyone whose homebuying strategy depends on seeing those rates again.
Mortgage Rates Aren't Controlled by One Number
One of the biggest misconceptions among consumers is that the Federal Reserve directly sets mortgage rates.
It doesn't.
The Fed controls short-term monetary policy, but 30-year mortgage rates are influenced by a much broader capital market.
Important factors include:
·Treasury yields
·Mortgage-backed securities pricing
·Inflation expectations
·Economic growth
·Federal Reserve policy
·Investor demand
·Market volatility
·Lender margins and risk
That's why a Federal Reserve rate cut doesn't automatically produce an equivalent reduction in your mortgage rate.
Mortgage markets frequently anticipate economic and monetary-policy changes before the Fed actually acts.
The 10-Year Treasury Matters
Mortgage rates often move in the same general direction as longer-term Treasury yields, particularly the 10-year Treasury.
The relationship isn't one-for-one because mortgages carry additional risks and costs. But Treasury yields provide an important benchmark for understanding mortgage pricing.
When investors demand higher yields on long-term bonds, mortgage rates generally face upward pressure.
That means homebuyers shouldn't simply ask:
"When will the Fed cut rates?"
A better question is:
"What is happening across the bond and mortgage-backed securities markets?"
Inflation Is Still Critical
Inflation is another major part of the mortgage-rate equation.
Investors lending money for long periods want compensation for the purchasing power inflation could erode.
If inflation expectations remain elevated or uncertain, long-term interest rates can remain higher even when economic growth slows.
For mortgage rates to fall substantially and remain there, markets would generally need greater confidence that inflation is under control without other factors simultaneously pushing long-term yields higher.
Could Mortgage Rates Still Fall?
Absolutely.
Saying ultra-low rates probably aren't coming back soon isn't the same as saying mortgage rates can't decline.
Economic weakness, lower inflation, falling Treasury yields, changing monetary policy, or financial-market stress could all put downward pressure on rates.
The important question is the magnitude.
A decline from 7% toward 6%, for example, could materially improve affordability.
But that's very different from assuming rates will return to 2.75% or 3%.
Fannie Mae's current forecast illustrates that distinction: its September 2026 forecast anticipates mortgage rates remaining in the upper-6% range through 2027 rather than returning to pandemic-era lows.
No forecast is guaranteed, but buyers should be careful about building a homebuying strategy around an extreme-rate scenario.
The Problem With Waiting for the "Perfect" Rate
Suppose you find the right house, can comfortably afford the payment, have adequate reserves, and negotiate favorable terms.
Should you automatically walk away because rates might decline later?
Not necessarily.
Waiting has its own risks.
Home prices can change. Seller negotiating leverage can change. Inventory can decline. Your income or credit profile can change. The house you want can sell to someone else.
And there's another consideration:
If rates fall significantly, more buyers may return to the market.
That could increase competition for desirable properties.
Instead of evaluating only the mortgage rate, buyers should evaluate the entire transaction.
Think in Terms of Payment, Cash and Flexibility
A mortgage rate is important, but it isn't the only number that determines whether a transaction makes sense.
I encourage borrowers to look closely at three numbers:
1. Monthly payment
What will the complete housing payment look like after principal, interest, taxes, insurance and applicable HOA expenses?
2. Cash required at closing
How much cash will you need for your down payment, closing costs, prepaid expenses and reserves?
3. Cash remaining after closing
Buying a house shouldn't necessarily leave you without liquidity.
Maintaining reserves can be just as important as maximizing the down payment.
That's mortgage strategy—not simply rate shopping.
Seller Credits Can Matter More Than Buyers Realize
In a market where sellers are willing to negotiate, financing strategy can become part of the purchase negotiation.
Instead of focusing exclusively on reducing the purchase price, a buyer might negotiate seller concessions that can potentially be applied toward eligible closing costs or a temporary or permanent interest-rate buydown, subject to loan-program limits.
Depending on the transaction, strategically using concessions could have a greater near-term impact on affordability than a relatively small reduction in purchase price.
The numbers should be modeled before making the offer.
Buy Now and Refinance Later?
You've probably heard the phrase:
"Marry the house, date the rate."
It's catchy, but it can also be dangerous if interpreted as a guarantee.
Never purchase a house you cannot comfortably afford today based solely on the assumption that you'll refinance later.
There is no guarantee that rates will fall, that your property value will support the refinance, or that your financial situation will remain unchanged.
A better approach is:
Make sure today's financing works today.
Then, if rates decline enough in the future to justify refinancing, evaluate the opportunity at that time.
What Should Texas Homebuyers Do?
Instead of trying to predict the exact bottom in mortgage rates, build a financing strategy around what you can control.
Understand your target payment.
Know how different down-payment amounts affect your liquidity.
Compare loan programs.
Evaluate whether paying discount points makes sense.
Model seller concessions.
Consider your expected holding period.
And determine what would need to happen for a future refinance to make financial sense.
The objective isn't necessarily finding the lowest advertised mortgage rate.
It's building the financing structure that best supports your goals.
The Bottom Line
The mortgage market could absolutely improve.
Rates could decline.
But buyers shouldn't assume that a return to 2% or 3% mortgages is right around the corner.
Those rates emerged from an extraordinary economic environment. Today's mortgage market is operating under very different conditions.
Instead of asking:
"When will 3% mortgage rates come back?"
Consider asking:
"What financing strategy makes sense if they don't?"
That's a much more useful question.
At Medallion Funds, we help homebuyers, homeowners, investors, doctors, self-employed borrowers and business owners evaluate financing beyond the headline interest rate.
The goal is to understand the transaction, compare available financing structures and make an informed decision based on the numbers.
Bill Rapp
Partner & Director of Capital Advisory | Medallion Funds
Commercial Lending Nationwide
Residential Lending in AL, CA, CO, NV & TXBottom of Form
https://www.billrapponline.com/
https://findamortgagebroker.com/Profile/WilliamRappJr28883
https://billrapp.commloan.com/
https://billrapponline.com/financingfuturescre-houston-katy
https://houstoncommercialmortgage.com/
https://author.billrapponline.com
https://doctorvideo.billrapponline.com/
https://veteransvideo.billrapponline.com/
https://mortgageviking.billrapponline.com/
https://fha203h.billrapponline.com/
https://renovationvideo.billrapponline.com
https://medallionfunds.com/bill-rapp/
https://www.amazon.com/dp/B0F32Z5BH2
https://veed.cello.so/FOmzTty6oi9
https://buymeacoffee.com/vikingente3
https://creplaybookseries.billrapponline.com
https://creplaybook.billrapponline.com/
© Bill Rapp, Medallion Funds LLC, Director of Capital Advisory
10 Tips for First-Time Homebuyers
Buying your first home can be both exciting and nerve-wracking at the same time. With so many things to consider and....
How To Choose the Right Lender for You
Lorem Ipsum is simply dummy text of the printing and typesetting industry. Lorem Ipsum has been the industry's standard dummy
Refinancing youe loan and when to do it
Lorem Ipsum is simply dummy text of the printing and typesetting industry. Lorem Ipsum has been the industry's standard dummy
Copyright ©2021 | Mortgage Viking Team
Licensed to Do Business | NMLS # 228246
This is not an offer to enter into an agreement. Not all customers will qualify. Information, rates and programs are subject to change without notice. All products are subject to credit and property approval. Other restrictions and limitations may apply. Copyright © 2021 | Medallion Funds
Corporate | NMLS ID NMLS # 1825831
Corporate Address : 2651 N. Green Valley Pkwy STE. 101 Henderson, NV 89014
Corporate NMLS NMLS # 1825831 | Company Website: https://medallionfunds.com/bill-rapp/
Copyright ©2021 | Mortgage Viking Team Licensed to Do Business | NMLS # 228246
This is not an offer to enter into an agreement. Not all customers will qualify. Information, rates and programs are subject to change without notice. All products are subject to credit and property approval. Other restrictions and limitations may apply
Corporate | NMLS ID NMLS # 1825831
Corporate Address : 2651 N. Green Valley Pkwy STE. 101 Henderson, NV 89014 https://medallionfunds.com/bill-rapp/
Facebook
Instagram
X
LinkedIn
Youtube
TikTok