Low Rates.
Our rates are low, our application is quick and easy! We can get you clear to close in as little as 10 days!
Trusted By Agents With
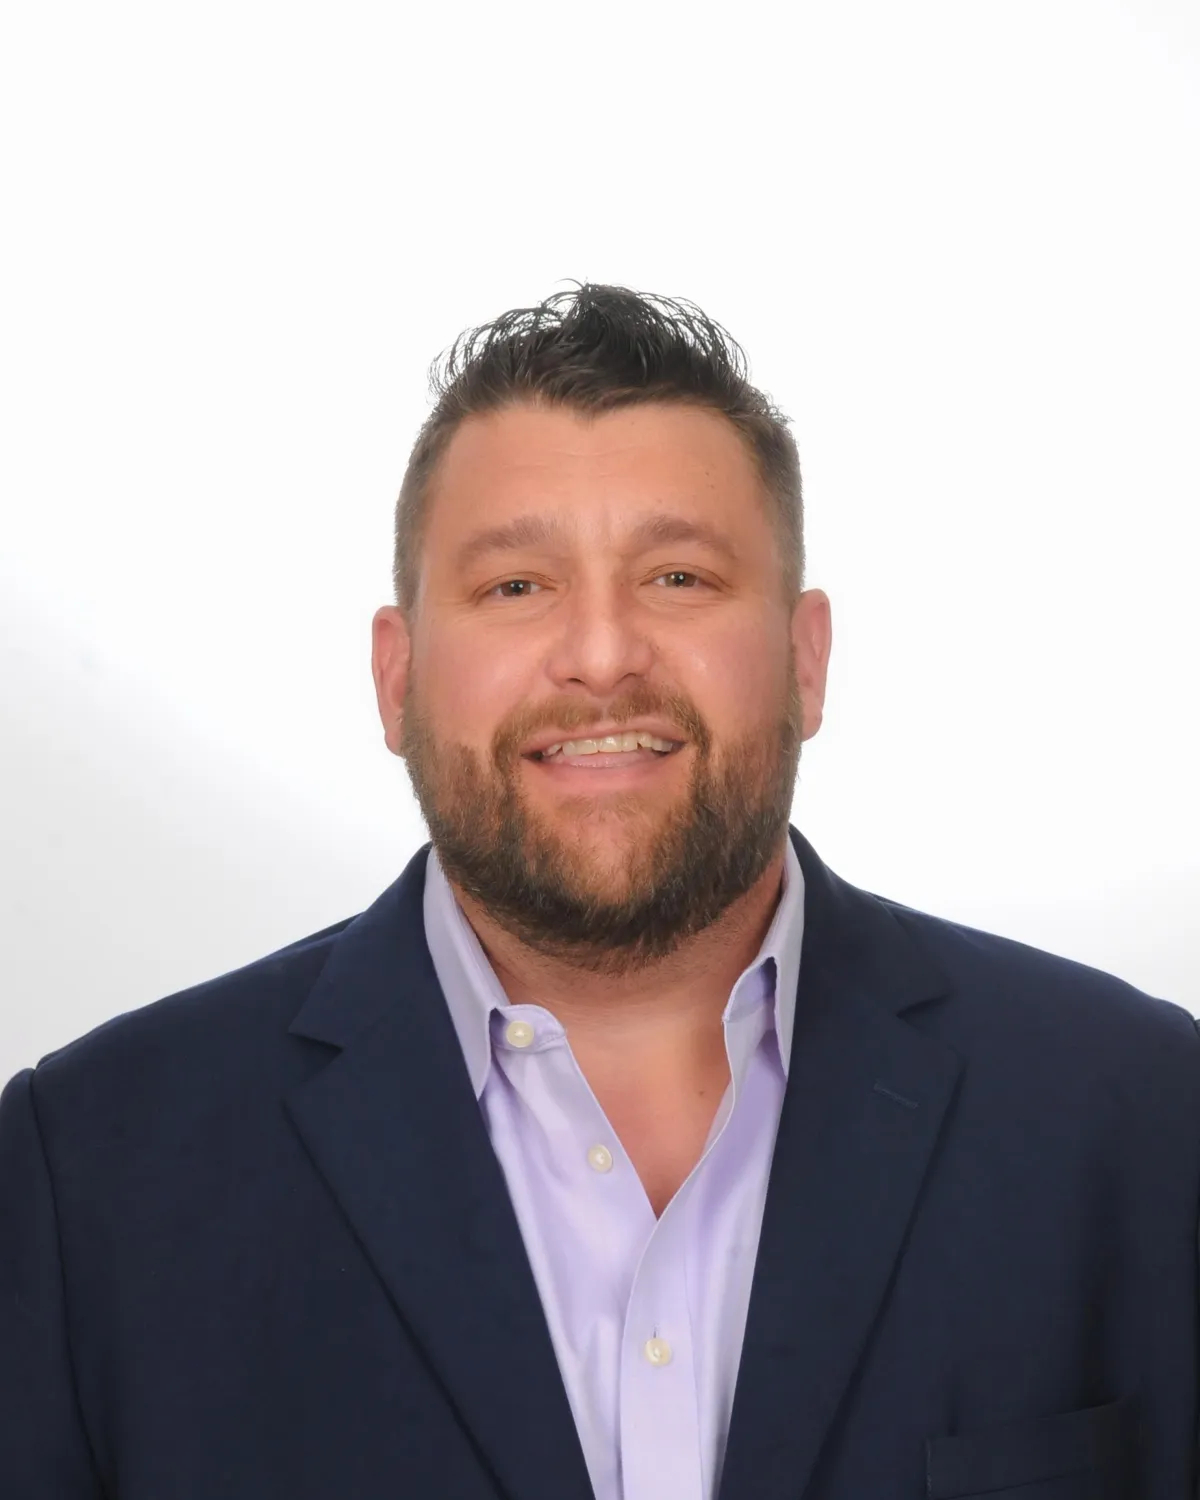
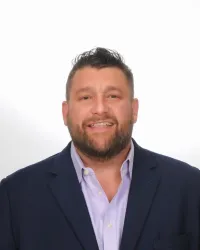
Meet Bill Rapp
NMLS ID # NMLS # 228246
Bill Rapp, CCIM is a Houston-based Capital Advisor at Medallion Funds, specializing in commercial real estate finance and strategic lending solutions. With over two decades of experience across brokerage and capital markets, Bill has worked with leading firms including eXp Commercial, NEXA Mortgage, Viking Enterprise LLC, and Sun Realty Houston.
A graduate of Texas A&M University with a BBA in Finance, Bill brings a disciplined, underwriting-first approach to every deal. His expertise spans commercial and residential financing, including asset-based lending, FHA financing, reverse mortgages, REO properties, and investment strategies for both single-family and commercial assets.
Known for his focus on structure over rate, Bill helps investors, business owners, and developers navigate complex transactions with clarity, precision, and a long-term wealth-building mindset.
The Client Experience
Great experience purchasing our first home! Bill was easy to reach and always able to answer any questions or concerns.

Loan Programs Available
Blogs
The Top 5 Mortgage Mistakes to Avoid
Buying your first home can be both exciting and nerve-wracking at the same time. With so many things to consider and....
Mortgage Do and
Do not list
Mortgages can be tricky, and it's easy to make mistakes that can end up costing you dearly. That's why we've put together this list....
Tips On How To Improve Your Credit Score
Let's talk about some ways you can improve your credit score! Your credit score is actually a big deal, and it can affect...
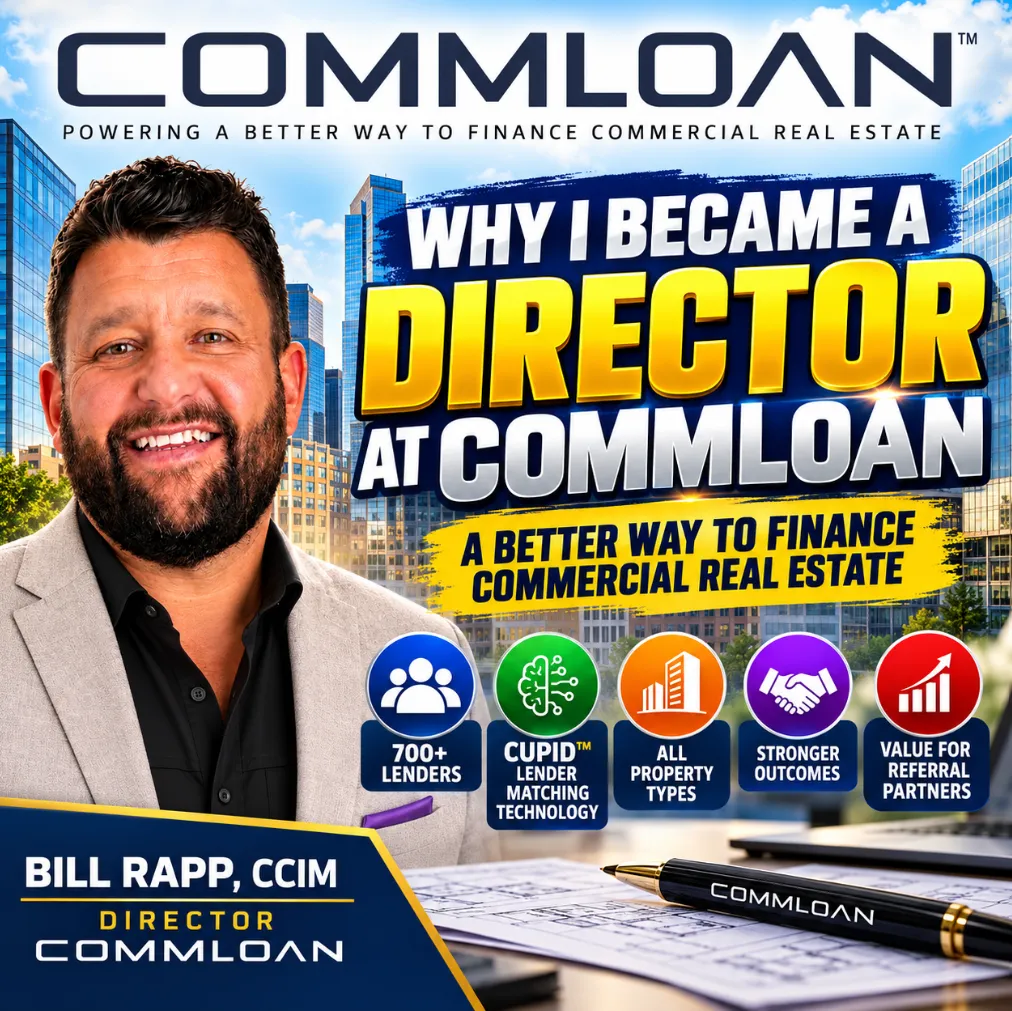
🚀 Why I Chose CommLoan: 700+ Lenders, Smarter Technology & a Better Way to Finance Commercial Real Estate 🏢💰
🚀 Why I Became a Director at CommLoan: How 700+ Lenders and Smarter Technology Are Changing Commercial Real Estate Financing 🏢
By Bill Rapp, CCIM | Director, CommLoan Empower Program
Commercial real estate financing is changing, and I believe investors, business owners, and commercial real estate professionals deserve a better way to access capital.
After more than two decades of experience in lending and years working in commercial real estate brokerage and capital advisory, I've seen firsthand how difficult securing the right commercial mortgage can be.
A borrower might have a strong investment opportunity, an experienced management team, and a well-located commercial property—yet struggle to secure financing because a particular bank doesn't finance that property type, has reached its lending concentration limits, or simply doesn't offer the right loan structure.
That's one of the primary reasons I became a Director at CommLoan.
I wanted to align myself with a technology-driven commercial real estate lending platform that offers access to more lenders, more financing options, and a more efficient process for borrowers and referral partners.
Through the CommLoan Empower Program, I can help commercial real estate investors, business owners, and professional advisors navigate financing opportunities using a marketplace of more than 700 lenders and CommLoan's proprietary CUPID™ technology.
Here's why I believe this model represents an important evolution in commercial real estate financing.
🏦 The Problem With Traditional Commercial Real Estate Lending
Traditional banks remain an important source of commercial real estate financing.
However, every bank has its own lending policies, underwriting requirements, concentration limits, geographic preferences, and risk tolerances.
For example, one bank may specialize in owner-occupied commercial real estate while another prefers stabilized multifamily investments.
A third lender may be interested in industrial properties but unwilling to finance hospitality assets.
This creates a challenge for borrowers.
A Bank Decline Doesn't Always Mean a Bad Deal
Imagine you're purchasing a $3 million commercial investment property.
You approach your local bank, but the lender declines the request because the property type falls outside its current lending appetite.
Does that automatically mean your investment isn't financeable?
Absolutely not.
It may simply mean you haven't found the right capital source.
The challenge isn't always the borrower or the property. Sometimes it's the lender fit.
This is why having access to a broader commercial lending marketplace can be valuable.
💻 What Is CommLoan?
CommLoan is a commercial real estate lending technology platform designed to connect borrowers and financing professionals with potential commercial mortgage lenders.
Rather than relying exclusively on one financial institution, the platform provides access to a marketplace of more than 700 lenders with different financing programs, underwriting standards, and investment preferences.
Through the CommLoan Empower Program, capital advisors can help borrowers evaluate financing opportunities across this lender network.
The objective is straightforward:
Help match the right commercial real estate transaction with an appropriate financing source.
CommLoan's approach combines three important components:
Technology-driven lender matching.
Access to a broad commercial lending marketplace.
Professional capital advisory support.
Together, these resources can help borrowers evaluate financing options more efficiently.
🤖 How CUPID™ Technology Changes Commercial Lending
One of the most compelling reasons I joined CommLoan is its proprietary CUPID™ commercial lending technology.
CUPID is designed to help identify potential lender matches based on the characteristics of a commercial real estate financing request.
How Does CUPID Work?
Commercial lenders evaluate numerous factors before deciding whether to finance a transaction.
These may include:
Property type and geographic location
Purchase price and appraised value
Requested loan amount
Loan-to-value ratio (LTV)
Debt service coverage ratio (DSCR)
Debt yield
Net operating income (NOI)
Borrower liquidity and net worth
Credit profile and experience
Occupancy and tenant characteristics
Loan purpose and repayment strategy
CUPID helps organize transaction information and identify lenders whose financing criteria may align with the request.
Instead of approaching lenders without knowing whether a transaction fits their programs, advisors can use technology to narrow the field of potential capital sources.
Why Does This Matter?
Commercial real estate financing isn't one-size-fits-all.
A multifamily investor refinancing a stabilized apartment complex has very different financing needs from a business owner purchasing an industrial warehouse.
Technology can help improve the initial lender-selection process, but successful financing still requires professional analysis, underwriting, documentation, and execution.
Technology helps identify possibilities. Experienced advisors help evaluate the financing strategy.
🌎 Why Access to 700+ Commercial Lenders Matters
One of CommLoan's most significant advantages is access to a marketplace of more than 700 commercial lenders.
That doesn't mean every lender will finance every transaction.
Instead, it means borrowers can potentially explore financing alternatives beyond the limited products available through one institution.
Different lenders specialize in different asset classes, loan amounts, geographic markets, and risk profiles.
Example: A $5 Million Multifamily Acquisition
Consider an investor purchasing a $5 million apartment property.
The investor requests $3.5 million in financing, representing a 70% loan-to-value ratio.
Potential financing sources might include:
Regional and community banks
Credit unions
Agency multifamily lenders
Debt funds
Commercial mortgage banking institutions
Private capital providers
Each financing source may evaluate the transaction differently.
One lender may prioritize DSCR, another may emphasize debt yield, and another may focus on borrower experience, property occupancy, or market fundamentals.
The most attractive financing structure isn't necessarily the one with the lowest advertised interest rate.
Borrowers should also evaluate amortization, loan term, prepayment provisions, recourse requirements, reserves, lender fees, and total financing costs.
The goal is to identify financing that aligns with the investment strategy—not simply obtain a loan approval.
🏢 What Types of Commercial Properties Can CommLoan Help Finance?
Commercial real estate financing needs vary considerably across property types.
Depending on borrower qualifications, lender availability, and transaction characteristics, the CommLoan marketplace may provide access to financing options for several major commercial property categories.
1. Multifamily Apartment Buildings
Financing for apartment acquisitions, refinancing, stabilized investment properties, and qualifying value-add opportunities.
2. Retail and Shopping Centers
Commercial mortgages for neighborhood retail centers, single-tenant properties, and multi-tenant shopping centers.
3. Industrial and Warehouse Properties
Financing for distribution centers, manufacturing facilities, flex properties, and owner-occupied industrial buildings.
4. Office and Medical Office Buildings
Loans for professional office properties, medical facilities, and qualifying owner-user acquisitions.
5. Hotels and Hospitality Properties
Potential financing through lenders specializing in hospitality real estate and hotel operations.
6. Commercial Construction and Development
Financing for eligible ground-up construction projects, property improvements, and development opportunities.
7. Owner-Occupied Commercial Real Estate
Commercial financing for business owners purchasing facilities for their own operations.
Eligible borrowers may also consider SBA financing.
8. Bridge and Transitional Properties
Short-term financing for acquisitions, repositioning strategies, lease-up situations, and other qualifying transitional opportunities.
The availability of each financing program depends on the transaction and the lender's underwriting requirements.
💰 Understanding the Commercial Mortgage Underwriting Process
One of the most important parts of commercial real estate financing is understanding how lenders evaluate risk.
Although requirements vary, several financial metrics consistently influence commercial mortgage underwriting.
Loan-to-Value Ratio (LTV)
LTV measures the loan amount relative to the property's value.
LTV = Loan Amount ÷ Property Value
For example:
Property value: $4,000,000
Requested loan: $2,800,000
LTV: 70%
A lower LTV generally provides a lender with a larger equity cushion.
Debt Service Coverage Ratio (DSCR)
DSCR measures a property's ability to generate sufficient income to cover debt payments.
DSCR = Net Operating Income ÷ Annual Debt Service
For example:
Annual NOI: $360,000
Annual debt service: $280,000
DSCR: 1.29x
A DSCR of 1.29x means the property generates approximately $1.29 in NOI for every $1.00 of annual debt service.
Debt Yield
Debt yield measures the property's NOI relative to the outstanding loan amount.
Debt Yield = NOI ÷ Loan Amount
For example:
NOI: $360,000
Loan amount: $3,000,000
Debt yield: 12%
Debt yield is particularly important to certain institutional and commercial mortgage lenders because it measures income relative to loan exposure without relying on the interest rate or amortization schedule.
Why These Metrics Matter
A borrower may qualify with one lender but not another because underwriting thresholds differ.
This is another reason why lender selection and loan structuring matter.
🤝 Why CommLoan Is Valuable for Commercial Real Estate Referral Partners
One of the reasons I became a Director at CommLoan is the opportunity to build stronger relationships with professionals who serve commercial real estate clients.
These relationships can create value for both borrowers and referral sources.
Commercial Real Estate Brokers
A commercial broker may identify an attractive investment opportunity, but the buyer still needs appropriate financing.
Working with a capital advisor can help the broker and buyer evaluate financing feasibility, identify documentation requirements, and understand potential lender constraints.
CPAs and Accountants
CPAs frequently advise business owners and investors on acquisitions, tax planning, cash flow, and financial strategy.
Having a commercial financing resource can help clients explore capital options when purchasing or refinancing real estate.
Attorneys
Real estate and business attorneys regularly work with clients involved in acquisitions, ownership restructuring, development, and commercial transactions.
A knowledgeable financing professional can be a useful resource during the transaction process.
Financial Advisors
Financial advisors may work with clients who own investment properties, operate businesses, or need to evaluate liquidity and leverage.
Commercial real estate financing can become an important component of the broader financial planning conversation.
Residential Mortgage Professionals
Residential loan officers occasionally encounter clients who need financing for apartment buildings, commercial investment properties, business facilities, or mixed-use assets.
Commercial lending relationships can help those professionals serve clients with financing needs outside traditional residential mortgage programs.
Referral relationships should always comply with applicable licensing, compensation, disclosure, and regulatory requirements.
📈 Why the Future of Commercial Lending Is Technology Plus Relationships
Technology is transforming nearly every segment of financial services.
Commercial real estate lending is no exception.
However, I don't believe technology eliminates the need for experienced financing professionals.
I believe it makes knowledgeable advisors more effective.
Commercial transactions frequently involve complicated financial statements, rent rolls, property operating histories, borrower structures, and unique underwriting considerations.
Software can help organize information and identify potential lenders.
But professional judgment remains essential when evaluating the transaction and negotiating appropriate financing terms.
The strongest model combines:
Technology + Lender Access + Underwriting Knowledge + Relationships + Execution
That's the approach that attracted me to CommLoan.
🎯 Why I Personally Chose CommLoan
My professional background includes commercial real estate brokerage, lending, and capital advisory.
As a CCIM designee, I understand that commercial real estate decisions involve more than finding a property or securing a mortgage.
They require evaluating the underlying economics of the investment.
I wanted a lending platform that complements that approach.
CommLoan provides an opportunity to combine my experience with technology and a broader network of potential financing sources.
My objective is to help clients answer several critical questions:
Is this commercial real estate transaction financeable?
Which lenders are most likely to consider the request?
What loan structure aligns with the borrower's investment strategy?
How much equity will the borrower need?
What are the likely underwriting challenges?
What documentation is required?
How can we position the transaction for an efficient financing process?
These questions matter whether you're acquiring your first commercial property or refinancing an established investment portfolio.
❓ Frequently Asked Questions About CommLoan and Commercial Real Estate Financing
What is CommLoan?
CommLoan is a technology-driven commercial real estate lending platform that connects financing professionals and borrowers with potential commercial lenders.
How many lenders are in the CommLoan marketplace?
CommLoan describes its commercial lending marketplace as providing access to more than 700 lenders.
Individual lender participation, programs, and availability may change.
What is CUPID technology?
CUPID™ is CommLoan's proprietary technology used to help match commercial real estate financing requests with potentially suitable lenders.
Can CommLoan help if my bank declined my commercial mortgage?
Potentially. A bank decline does not necessarily mean another lender will reject the transaction. However, approval depends on the underlying financials, borrower qualifications, property characteristics, and lender requirements.
Does CommLoan offer SBA loans?
The commercial lending marketplace may provide access to lenders offering SBA 7(a) and SBA 504 financing for eligible transactions. SBA programs have specific eligibility and occupancy requirements.
Can CommLoan finance investment properties?
Potential financing opportunities may include multifamily, retail, industrial, office, and other qualifying commercial investment properties.
Is using a commercial mortgage broker better than going directly to a bank?
It depends on the transaction. A commercial mortgage broker or capital advisor can help evaluate multiple potential lenders, while a direct bank relationship may offer advantages for certain borrowers. Compare total costs, terms, execution certainty, and service.
What documents are needed for a commercial mortgage?
Common requirements include a purchase contract, rent roll, trailing 12-month operating statement, historical financials, borrower financial statements, entity documents, and property information. Requirements vary by lender and loan program.
🚀 Ready to Explore a Better Way to Finance Commercial Real Estate?
Whether you're purchasing an apartment complex, refinancing a shopping center, acquiring an industrial warehouse, developing commercial property, or buying a building for your business, having access to the right capital sources matters.
I became a Director at CommLoan because I believe borrowers deserve more than a one-size-fits-all lending solution.
They deserve knowledgeable guidance, efficient technology, and the opportunity to evaluate financing options that fit their specific objectives.
Let's discuss your commercial real estate financing strategy.
Bill Rapp, CCIM
Director | CommLoan Empower Program
Commercial Real Estate & Capital Advisory
🌐 Explore Your Financing Options:
https://billrapp.commloan.com/
Disclaimer: Financing is subject to lender underwriting, borrower qualifications, property eligibility, and program availability. Lender access does not guarantee financing approval, specific terms, or loan funding. Examples are illustrative.
#CommLoan #CommercialRealEstate #CommercialFinancing #CommercialMortgage #CREInvesting #CommercialLending #CapitalMarkets #CUPIDTechnology #CommercialRealEstateLoans #BillRappCCIM
10 Tips for First-Time Homebuyers
Buying your first home can be both exciting and nerve-wracking at the same time. With so many things to consider and....
How To Choose the Right Lender for You
Lorem Ipsum is simply dummy text of the printing and typesetting industry. Lorem Ipsum has been the industry's standard dummy
Refinancing youe loan and when to do it
Lorem Ipsum is simply dummy text of the printing and typesetting industry. Lorem Ipsum has been the industry's standard dummy
Copyright ©2021 | Mortgage Viking Team
Licensed to Do Business | NMLS # 228246
This is not an offer to enter into an agreement. Not all customers will qualify. Information, rates and programs are subject to change without notice. All products are subject to credit and property approval. Other restrictions and limitations may apply. Copyright © 2021 | Medallion Funds
Corporate | NMLS ID NMLS # 1825831
Corporate Address : 2651 N. Green Valley Pkwy STE. 101 Henderson, NV 89014
Corporate NMLS NMLS # 1825831 | Company Website: https://medallionfunds.com/bill-rapp/
Copyright ©2021 | Mortgage Viking Team Licensed to Do Business | NMLS # 228246
This is not an offer to enter into an agreement. Not all customers will qualify. Information, rates and programs are subject to change without notice. All products are subject to credit and property approval. Other restrictions and limitations may apply
Corporate | NMLS ID NMLS # 1825831
Corporate Address : 2651 N. Green Valley Pkwy STE. 101 Henderson, NV 89014 https://medallionfunds.com/bill-rapp/
Facebook
Instagram
X
LinkedIn
Youtube
TikTok