Low Rates.
Our rates are low, our application is quick and easy! We can get you clear to close in as little as 10 days!
Trusted By Agents With
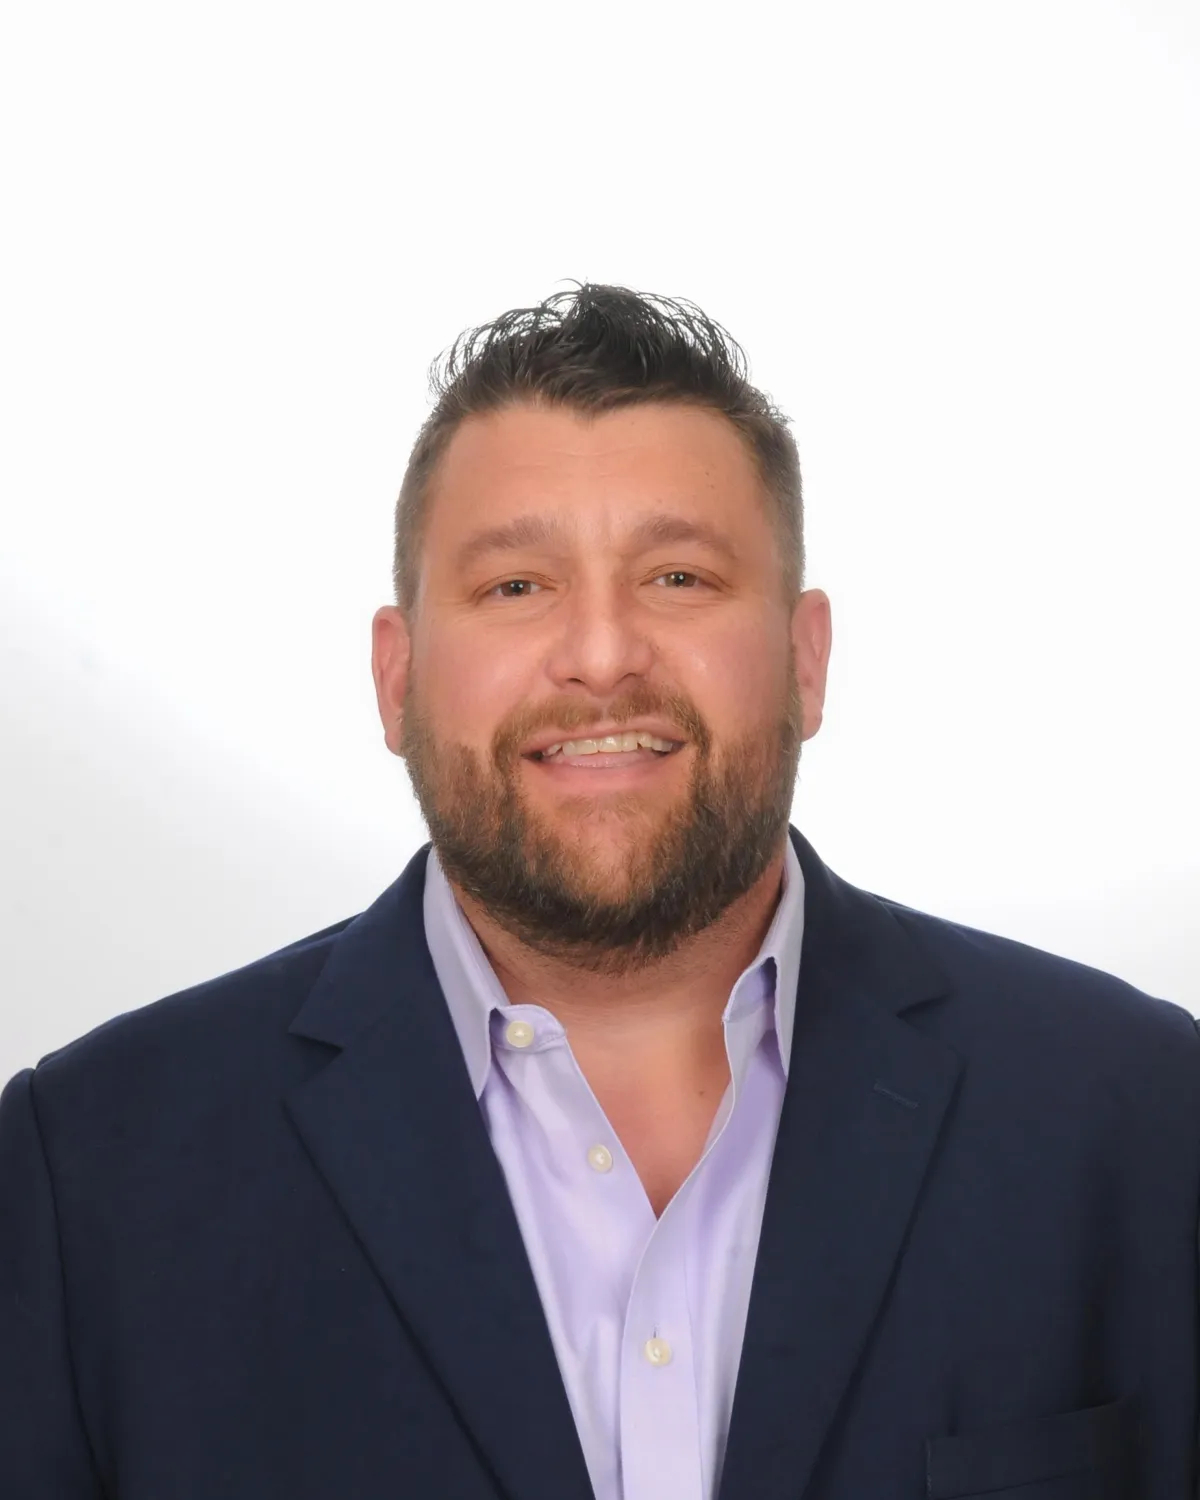
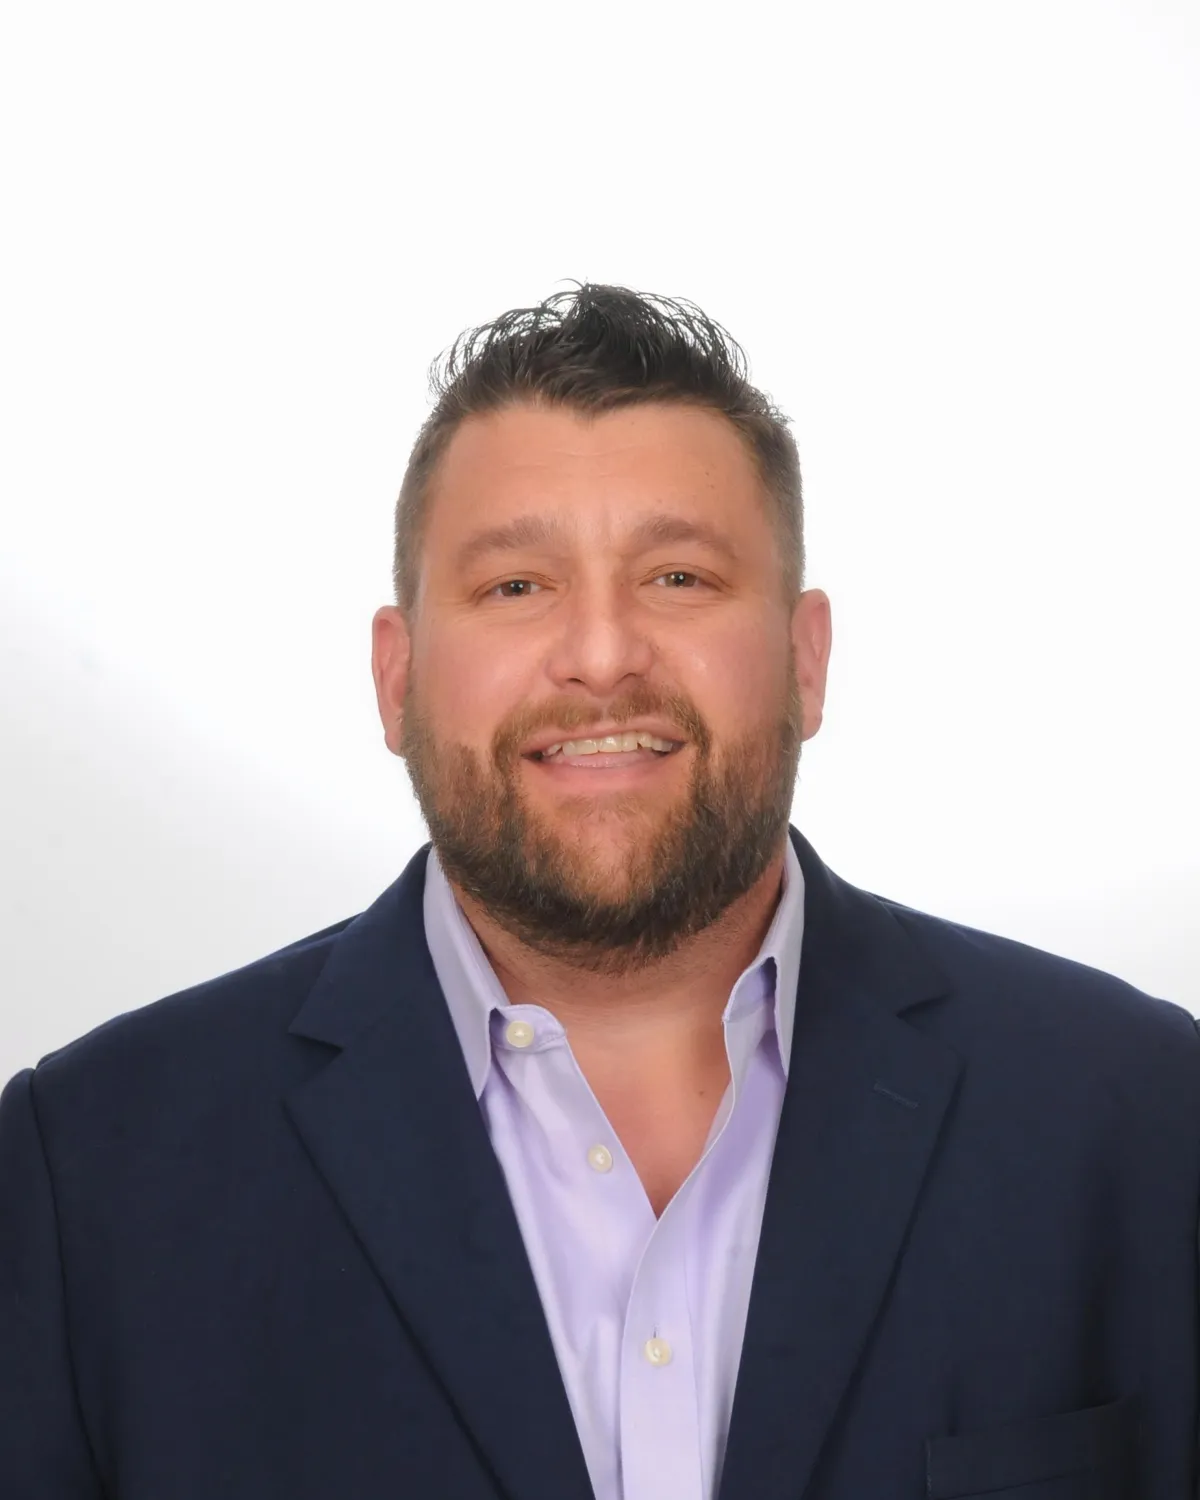
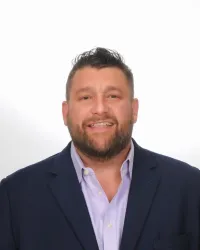
Meet Bill Rapp
NMLS ID # NMLS # 228246
Bill Rapp, CCIM is a Houston-based Capital Advisor at Medallion Funds, specializing in commercial real estate finance and strategic lending solutions. With over two decades of experience across brokerage and capital markets, Bill has worked with leading firms including eXp Commercial, NEXA Mortgage, Viking Enterprise LLC, and Sun Realty Houston.
A graduate of Texas A&M University with a BBA in Finance, Bill brings a disciplined, underwriting-first approach to every deal. His expertise spans commercial and residential financing, including asset-based lending, FHA financing, reverse mortgages, REO properties, and investment strategies for both single-family and commercial assets.
Known for his focus on structure over rate, Bill helps investors, business owners, and developers navigate complex transactions with clarity, precision, and a long-term wealth-building mindset.
The Client Experience
Great experience purchasing our first home! Bill was easy to reach and always able to answer any questions or concerns.

Loan Programs Available


Blogs
The Top 5 Mortgage Mistakes to Avoid
Buying your first home can be both exciting and nerve-wracking at the same time. With so many things to consider and....
Mortgage Do and
Do not list
Mortgages can be tricky, and it's easy to make mistakes that can end up costing you dearly. That's why we've put together this list....
Tips On How To Improve Your Credit Score
Let's talk about some ways you can improve your credit score! Your credit score is actually a big deal, and it can affect...
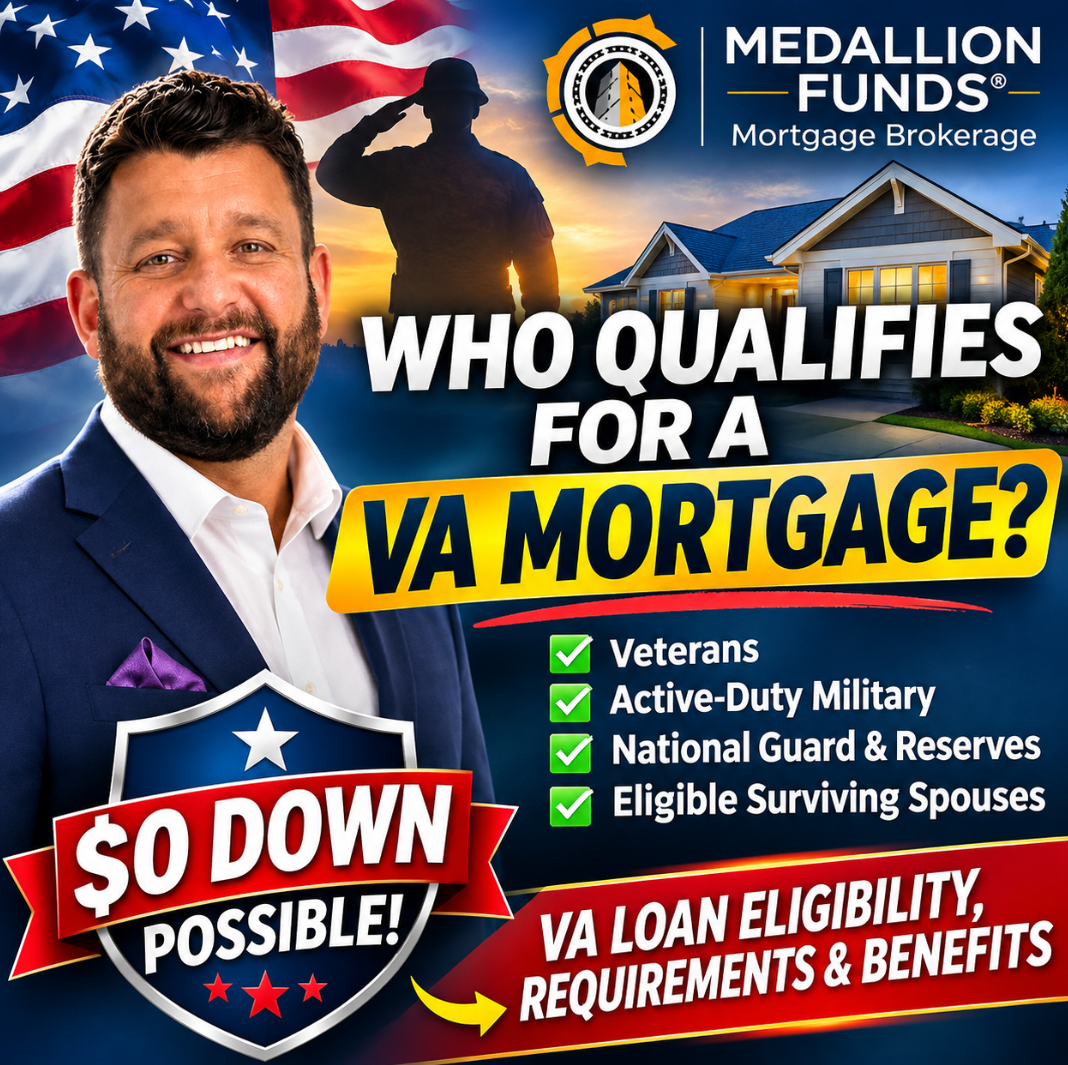
🏡 Who Qualifies for a VA Mortgage?
🏡 Who Qualifies for a VA Mortgage?
VA Loan Requirements: Who Is Eligible? 🏠
____________________________________________________________________________
🏡 Who Qualifies for a VA Mortgage? 🇺🇸
VA Loan Eligibility, Military Service Requirements, Credit Scores, and Zero-Down Home Financing Explained
If you served in the United States military, you may qualify for one of the most valuable home financing benefits available: the VA home loan.
VA mortgages can offer eligible borrowers no down payment, no monthly private mortgage insurance (PMI), and competitive interest rates. Yet many veterans and military families don't realize they qualify—or mistakenly believe they need perfect credit, a large savings account, or decades of military service.
The reality? VA mortgage eligibility is broader than many homebuyers expect.
I'm Bill Rapp with Medallion Funds, and I help homebuyers, veterans, and military families explore mortgage financing options that fit their financial goals.
Let's examine who qualifies for a VA mortgage, how the requirements work, and what you should know before buying a home.
1. Who Is Eligible for a VA Home Loan?
VA mortgage eligibility primarily depends on your military service history, discharge status, or qualifying relationship to a service member.
The Department of Veterans Affairs establishes eligibility rules, while approved mortgage lenders evaluate your financial qualifications.
Veterans
Many veterans qualify for VA home loan benefits based on their period of service and discharge characterization.
For veterans who served on active duty during the modern era, eligibility commonly requires:
·At least 24 continuous months of active-duty service for many veterans whose service began after September 7, 1980.
·A qualifying exception for certain shorter periods of service, including some service-connected disability discharges.
·A discharge status that satisfies VA eligibility requirements.
Different minimum service requirements apply to earlier service periods, and some discharges require an individual eligibility determination.
Important: You do not necessarily need to have served 20 years or retired from the military to qualify for a VA mortgage.
Active-Duty Military Members
Active-duty service members generally become eligible after 90 continuous days of active-duty service.
This can make VA financing available to service members much earlier in their military careers than they might expect.
National Guard and Reserve Members
Members of the National Guard and Reserves may qualify through several pathways, including:
·Six creditable years of qualifying National Guard or Reserve service, subject to applicable service and separation requirements.
·Qualifying federal active-duty service.
·Certain qualifying Title 32 National Guard service.
Eligibility can vary depending on the specific service orders and military record.
Eligible Surviving Spouses
Certain surviving spouses may qualify for VA home loan benefits, including spouses of service members who died in the line of duty or from a service-connected disability.
Other circumstances may also qualify, including certain spouses of veterans who were eligible for qualifying disability compensation at death.
The first step is determining whether you can obtain a VA Certificate of Eligibility.
2. What Is a VA Certificate of Eligibility?
A Certificate of Eligibility (COE) confirms that the VA recognizes your eligibility for the home loan benefit.
It does not guarantee that a mortgage lender will approve your loan.
Your COE generally helps establish:
·Your VA home loan eligibility.
·Your available entitlement.
·Whether a VA funding fee exemption may apply.
Many mortgage lenders can request a COE electronically. Depending on your service history, supporting documents such as a DD Form 214, statement of service, or National Guard and Reserve records may be required.
At Medallion Funds, we can help borrowers understand the COE process and identify the documentation needed to move forward.
3. What Credit Score Do You Need for a VA Loan?
One of the most common questions veterans ask is:
"Can I qualify for a VA mortgage with less-than-perfect credit?"
The VA does not establish a universal minimum credit score for its home loan guaranty program.
However, individual lenders may impose their own credit score requirements.
Some lenders use benchmarks around 580 or 620, while others may evaluate lower scores or require higher scores depending on the loan.
Lenders also consider:
·Payment history.
·Outstanding debt.
·Recent late payments.
·Bankruptcy or foreclosure history.
·Income stability.
·Available cash reserves.
A lower credit score does not automatically eliminate every VA loan opportunity.
Mortgage broker advantage: Working with a mortgage brokerage like Medallion Funds can help you compare participating lenders whose underwriting requirements may differ.
4. Can You Buy a Home With Zero Down Using a VA Loan?
Yes. One of the biggest advantages of VA financing is the possibility of purchasing an eligible home with 0% down.
Qualified borrowers with sufficient VA entitlement may finance up to 100% of the eligible property's value or purchase price, subject to lender and VA requirements.
For example:
Home purchase price: $350,000
Financing Option | Illustrative Down Payment |
Conventional loan at 5% down | $17,500 |
FHA loan at 3.5% down | $12,250 |
VA loan at 0% down | $0 |
This comparison illustrates down payments only. Actual eligibility, financing costs, and mortgage insurance differ by program.
A zero-down VA loan can preserve savings for moving expenses, emergency reserves, furniture, or future home maintenance.
However, zero down does not automatically mean zero cash needed at closing.
Buyers may still encounter closing costs, prepaid expenses, earnest money requirements, and a VA funding fee unless exempt. Seller concessions or lender credits may help with certain eligible expenses.
5. Do VA Loans Require Mortgage Insurance?
VA loans generally do not require monthly private mortgage insurance.
That can be a significant advantage compared with some conventional and FHA financing options.
However, many VA borrowers must pay a one-time VA funding fee.
For a purchase loan with less than 5% down, the standard funding fee is generally:
·2.15% for first use.
·3.30% for subsequent use.
Reduced funding fee percentages generally apply when the borrower makes a down payment of at least 5% or 10%.
Certain borrowers are exempt, including many veterans receiving VA compensation for service-connected disabilities and other qualifying categories.
Funding fee rules depend on the borrower and transaction, and rates can change.
6. What Income Do You Need to Qualify for a VA Mortgage?
VA loan approval depends on your ability to repay the mortgage, not simply on your military service.
Mortgage lenders evaluate qualifying income, employment stability, existing debt, and household expenses.
Debt-to-Income Ratio
Your debt-to-income ratio (DTI) compares your monthly debt obligations with your qualifying gross monthly income.
The VA uses 41% as an important underwriting benchmark, but this is not an absolute maximum.
Borrowers with higher DTI ratios may still qualify when the overall file meets applicable underwriting requirements.
VA Residual Income
VA financing also emphasizes residual income.
Residual income represents the money remaining after qualifying obligations and certain estimated living expenses are deducted.
The VA uses regional and household-size guidelines to help evaluate whether borrowers have enough income remaining to support everyday expenses.
This makes VA underwriting different from a simple credit-score or DTI-only evaluation.
7. Can You Use a VA Loan More Than Once?
Yes. VA mortgage benefits are not necessarily a one-time opportunity.
Depending on your entitlement, you may be able to:
·Purchase another primary residence.
·Restore entitlement after paying off and disposing of a previously financed property.
·Use remaining entitlement for another qualifying purchase.
·Refinance an existing VA loan through an Interest Rate Reduction Refinance Loan (IRRRL), when eligible.
·Explore a VA cash-out refinance, subject to applicable requirements.
Some borrowers may even have more than one VA loan outstanding, provided they have sufficient remaining entitlement and satisfy occupancy and lender requirements.
The amount of entitlement available is an important consideration.
8. What Types of Homes Qualify for VA Financing?
VA loans are primarily designed for eligible borrowers purchasing or refinancing homes they intend to occupy as a primary residence.
Potentially eligible properties include:
·Single-family homes.
·Certain VA-approved condominiums.
·Eligible manufactured homes.
·Two-to-four-unit residential properties.
·Certain newly constructed homes.
For a two-to-four-unit property, the borrower generally must intend to occupy one unit as a primary residence.
That can create an opportunity for eligible veterans to purchase a small multifamily property while living in one unit and potentially using qualifying rental income from the other units.
VA loans are not intended for purchasing a property solely as a vacation home or non-owner-occupied investment property.
The home must also satisfy applicable VA appraisal and minimum property requirements.
9. Real-World Example: A Veteran Buying a $350,000 Home
Consider a veteran purchasing a primary residence in Katy, Texas.
Purchase price: $350,000
Down payment: $0
VA loan eligibility: Confirmed
First-time VA loan use: Yes
Funding fee exemption: No
Assuming the standard 2.15% first-use funding fee:
·Base loan amount: $350,000
·VA funding fee: $7,525
·Total loan amount if the fee is financed: $357,525
The borrower could potentially purchase the home without a down payment while avoiding monthly PMI.
Actual closing costs, taxes, insurance, interest rates, and lender requirements would still apply.
A veteran exempt from the funding fee could have a different financing structure.
This is why comparing the full mortgage payment and closing costs—not just the interest rate—is so important.
10. How to Apply for a VA Mortgage
If you're considering buying a home with VA financing, here's a practical starting point.
Step 1: Verify your eligibility. Review your service history and request a Certificate of Eligibility.
Step 2: Review your finances. Examine your credit, income, existing debts, and available savings.
Step 3: Get pre-approved. Work with a mortgage professional familiar with VA financing.
Step 4: Compare financing options. Review interest rates, annual percentage rates, lender fees, funding fee treatment, and estimated monthly payments.
Step 5: Find an eligible home. Work with your real estate agent to identify properties that meet your needs and VA requirements.
Step 6: Complete underwriting and closing. The lender will evaluate the application, property appraisal, title, insurance, and other closing conditions.
Why Work With Medallion Funds for Your VA Mortgage?
VA loans offer valuable benefits, but finding the right financing structure requires more than simply checking eligibility.
At Medallion Funds, we help veterans, active-duty military members, and eligible homebuyers evaluate mortgage programs, compare lender options, and understand their financing decisions.
Whether you're purchasing your first home, relocating to Texas, considering a small multifamily property, or exploring a VA refinance, our goal is to help you make an informed decision.
Ready to Explore Your VA Home Loan Benefits?
Bill Rapp
Partner & Director of Capital Advisory | Medallion Funds
Commercial Lending Nationwide
Residential Lending in AL, CA, CO, NV & TXBottom of Form
📞 Call or Text: 281-222-0433
🌐 Website: https://billrapponline.com
🎥 Subscribe to Mortgage Viking: https://www.youtube.com/@billrapp-medallion-funds
https://www.billrapponline.com/
https://findamortgagebroker.com/Profile/WilliamRappJr28883
https://billrapp.commloan.com/
https://billrapponline.com/financingfuturescre-houston-katy
https://houstoncommercialmortgage.com/
https://author.billrapponline.com
https://doctorvideo.billrapponline.com/
https://veteransvideo.billrapponline.com/
https://mortgageviking.billrapponline.com/
https://fha203h.billrapponline.com/
https://renovationvideo.billrapponline.com
https://medallionfunds.com/bill-rapp/
https://www.amazon.com/dp/B0F32Z5BH2
https://veed.cello.so/FOmzTty6oi9
https://buymeacoffee.com/vikingente3
https://creplaybookseries.billrapponline.com
https://creplaybook.billrapponline.com/
© Bill Rapp, Medallion Funds LLC, Director of Capital Advisory
10 Tips for First-Time Homebuyers
Buying your first home can be both exciting and nerve-wracking at the same time. With so many things to consider and....
How To Choose the Right Lender for You
Lorem Ipsum is simply dummy text of the printing and typesetting industry. Lorem Ipsum has been the industry's standard dummy
Refinancing youe loan and when to do it
Lorem Ipsum is simply dummy text of the printing and typesetting industry. Lorem Ipsum has been the industry's standard dummy
Copyright ©2021 | Mortgage Viking Team
Licensed to Do Business | NMLS # 228246
This is not an offer to enter into an agreement. Not all customers will qualify. Information, rates and programs are subject to change without notice. All products are subject to credit and property approval. Other restrictions and limitations may apply. Copyright © 2021 | Medallion Funds
Corporate | NMLS ID NMLS # 1825831
Corporate Address : 2651 N. Green Valley Pkwy STE. 101 Henderson, NV 89014
Corporate NMLS NMLS # 1825831 | Company Website: https://medallionfunds.com/bill-rapp/
Copyright ©2021 | Mortgage Viking Team Licensed to Do Business | NMLS # 228246
This is not an offer to enter into an agreement. Not all customers will qualify. Information, rates and programs are subject to change without notice. All products are subject to credit and property approval. Other restrictions and limitations may apply
Corporate | NMLS ID NMLS # 1825831
Corporate Address : 2651 N. Green Valley Pkwy STE. 101 Henderson, NV 89014 https://medallionfunds.com/bill-rapp/
Facebook
Instagram
X
LinkedIn
Youtube
TikTok