Low Rates.
Our rates are low, our application is quick and easy! We can get you clear to close in as little as 10 days!
Trusted By Agents With
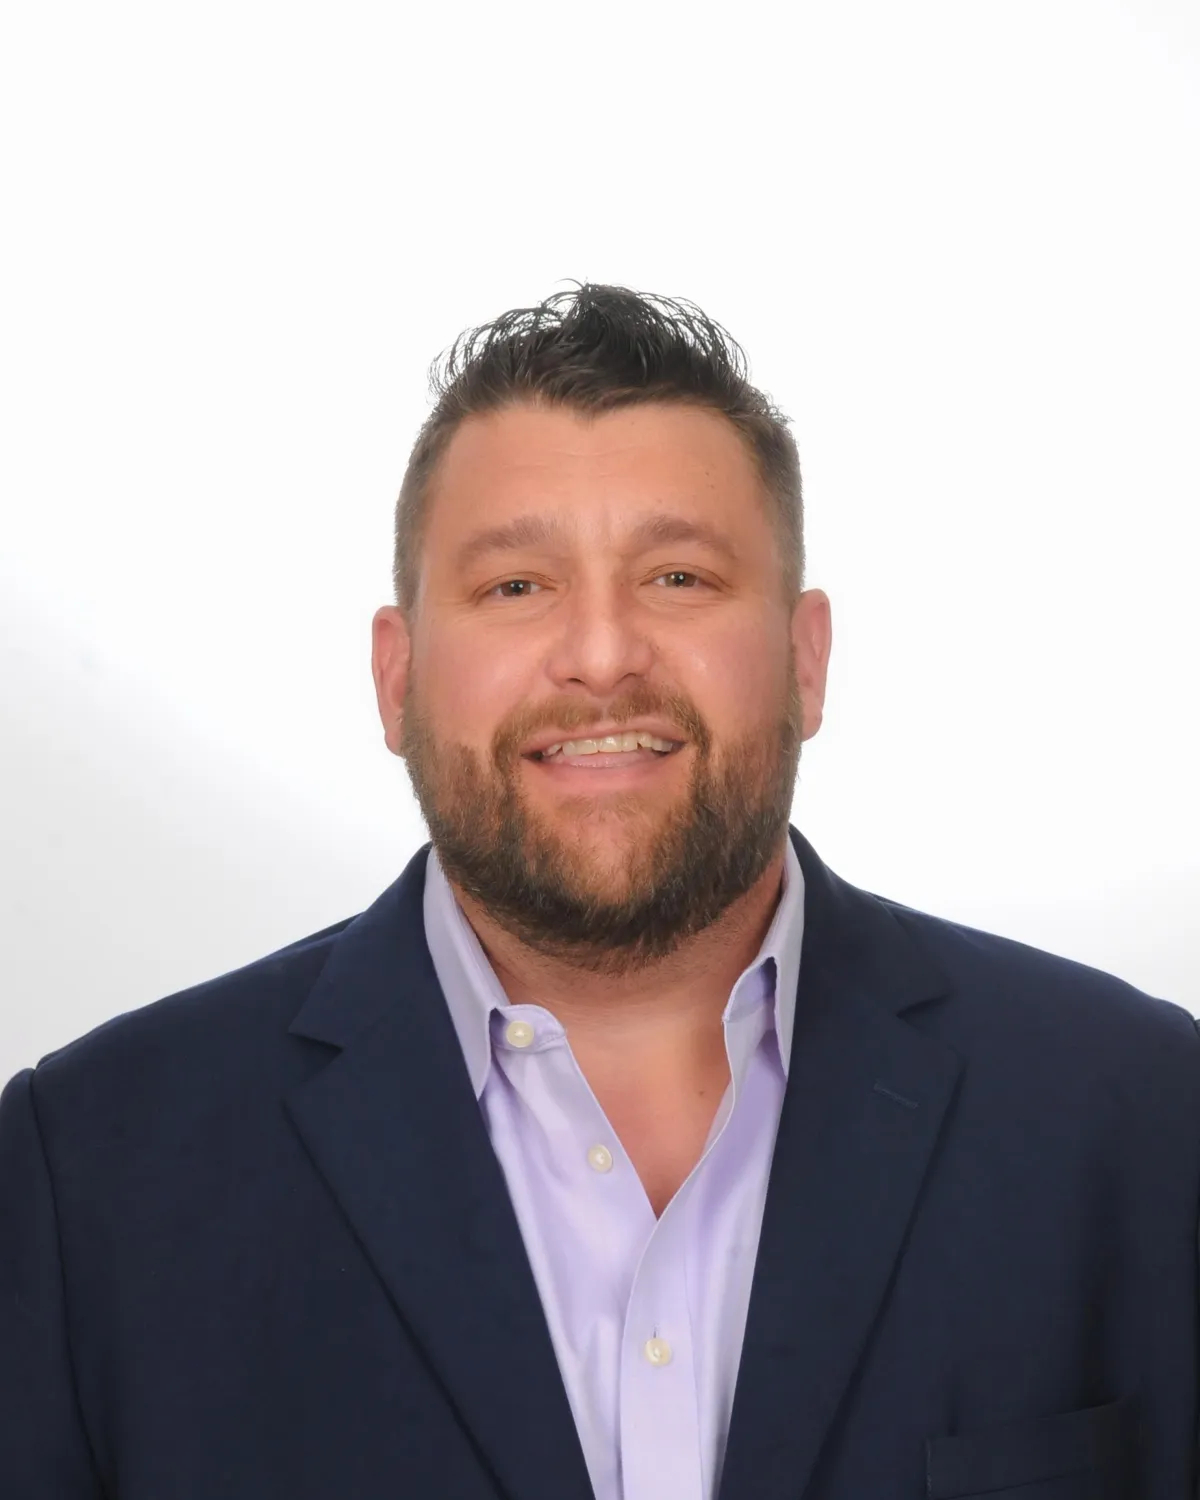
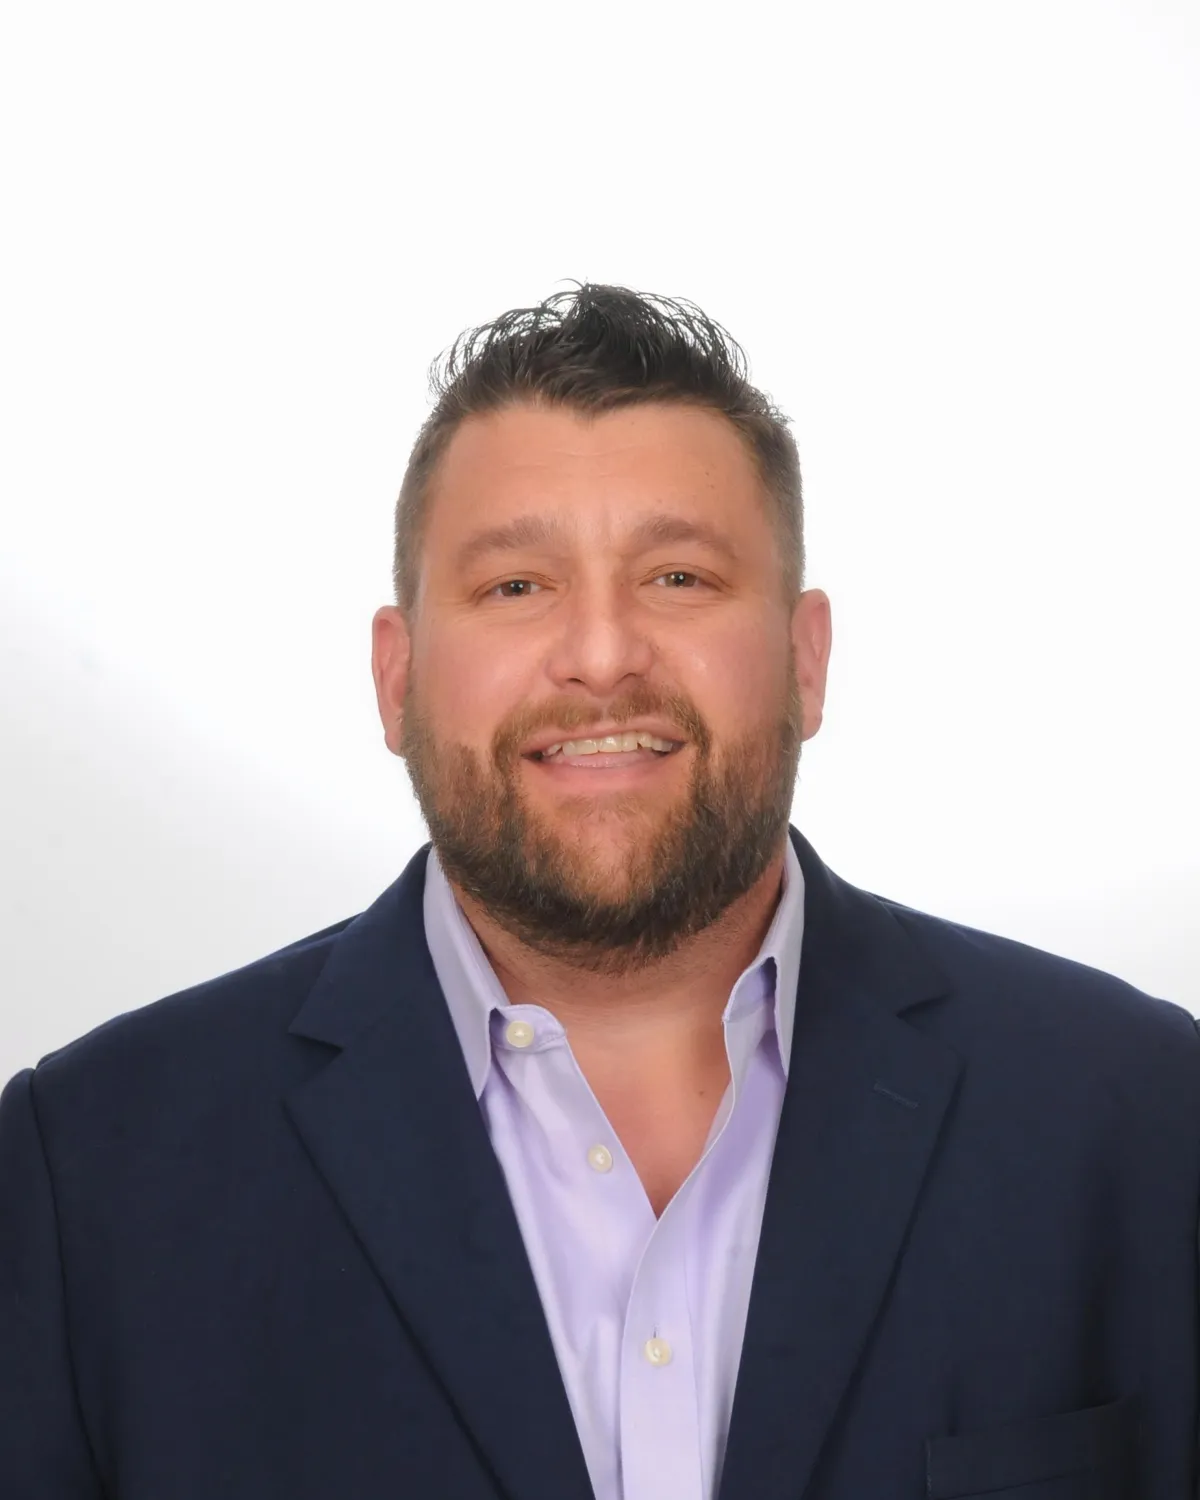
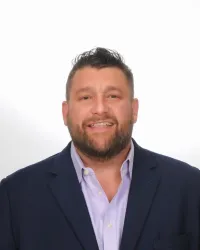
Meet Bill Rapp
NMLS ID # NMLS # 228246
Bill Rapp, CCIM is a Houston-based Capital Advisor at Medallion Funds, specializing in commercial real estate finance and strategic lending solutions. With over two decades of experience across brokerage and capital markets, Bill has worked with leading firms including eXp Commercial, NEXA Mortgage, Viking Enterprise LLC, and Sun Realty Houston.
A graduate of Texas A&M University with a BBA in Finance, Bill brings a disciplined, underwriting-first approach to every deal. His expertise spans commercial and residential financing, including asset-based lending, FHA financing, reverse mortgages, REO properties, and investment strategies for both single-family and commercial assets.
Known for his focus on structure over rate, Bill helps investors, business owners, and developers navigate complex transactions with clarity, precision, and a long-term wealth-building mindset.
The Client Experience
Great experience purchasing our first home! Bill was easy to reach and always able to answer any questions or concerns.

Loan Programs Available
Blogs
The Top 5 Mortgage Mistakes to Avoid
Buying your first home can be both exciting and nerve-wracking at the same time. With so many things to consider and....
Mortgage Do and
Do not list
Mortgages can be tricky, and it's easy to make mistakes that can end up costing you dearly. That's why we've put together this list....
Tips On How To Improve Your Credit Score
Let's talk about some ways you can improve your credit score! Your credit score is actually a big deal, and it can affect...
🌉 When Should You Use a Commercial Real Estate Bridge Loan? 7 Smart Strategies for Investors 🏢
🌉 When Should You Use a Commercial Real Estate Bridge Loan? 7 Smart Strategies for Investors 🏢
🏢 Commercial Bridge Loans Explained: When Short-Term Financing Makes Sense (and When It Doesn't) 💰
_______________________________________________________________________________
When Should You Use a Commercial Real Estate Bridge Loan? 7 Smart Strategies for Investors
Commercial real estate opportunities don't always wait for traditional bank financing. Whether you're acquiring an underperforming multifamily property, renovating a vacant retail center, or refinancing a commercial mortgage that's approaching maturity, timing can make or break a deal.
That's where a commercial real estate bridge loan can play an important role.
Bridge financing provides short-term capital to help investors and business owners navigate the period between an immediate financing need and a longer-term solution.
But bridge loans aren't appropriate for every transaction. They generally carry higher borrowing costs, shorter repayment periods, and greater refinancing risk than conventional commercial mortgages.
The key is understanding when to use a commercial bridge loan, how lenders evaluate these transactions, and how to establish a realistic exit strategy.
Let's examine seven situations where bridge financing may make sense.
What Is a Commercial Real Estate Bridge Loan?
A commercial real estate bridge loan is a short-term financing solution designed to provide capital until a property can qualify for permanent financing, be sold, or otherwise repay the loan.
Unlike traditional commercial mortgages, which generally emphasize stabilized cash flow and long-term debt service, bridge lenders may focus more heavily on current collateral value, projected improvements, sponsor experience, available liquidity, and the feasibility of the business plan.
Typical commercial bridge loan characteristics include:
Loan term: Often 6–36 months, depending on the lender and transaction.
Interest rate: Generally higher than comparable permanent financing.
Loan structure: Frequently interest-only during the initial term.
Leverage: Based on loan-to-value (LTV), loan-to-cost (LTC), and lender-specific risk limits.
Collateral: Commercial property, with guarantees or additional security depending on the transaction.
Repayment: Usually through a refinance, sale, or another documented source of capital.
Some bridge lenders offer extension options, future renovation advances, and flexible prepayment provisions. These features are not universal and should be negotiated before closing.
1. Acquiring a Property That Doesn't Qualify for Conventional Financing
One of the most common reasons to use a commercial bridge loan is purchasing a property that doesn't currently meet conventional lending standards.
For example, consider a 30-unit apartment building with 55% occupancy.
A conventional lender may be reluctant to finance the acquisition because the property doesn't generate sufficient net operating income to support permanent debt.
However, an experienced investor may recognize an opportunity to renovate units, improve management, increase occupancy, and stabilize rental income.
A bridge loan can potentially finance the acquisition while the investor executes that business plan.
Once the property achieves sustainable occupancy and cash flow, the investor may refinance into a conventional bank, agency, or other permanent commercial mortgage.
Best fit: Properties with identifiable operational problems, a credible improvement plan, and sufficient capital to complete stabilization.
2. Financing Commercial Property Renovations and Value-Add Projects
Bridge financing is particularly useful for value-add commercial real estate investments.
These projects may involve:
Renovating older apartment buildings.
Repositioning outdated office properties.
Improving neighborhood retail centers.
Converting underutilized industrial space.
Addressing deferred maintenance.
Completing tenant improvements and leasing vacant suites.
Traditional lenders often underwrite properties using current income rather than projected income after renovation.
Bridge lenders may be willing to consider a property's future stabilized value, subject to conservative underwriting and verification.
For example, an investor purchasing a retail center for $2 million might plan $400,000 in improvements to attract new tenants and increase net operating income.
A bridge lender could potentially structure financing around acquisition costs, eligible renovation expenses, and the project's projected value.
However, investors must budget for construction overruns, leasing commissions, carrying costs, and debt service throughout the improvement period.
Important: Future value doesn't guarantee future loan proceeds. The permanent refinancing lender will independently evaluate the stabilized property.
3. Closing Quickly on a Time-Sensitive Acquisition
Commercial real estate transactions sometimes require faster execution than traditional bank financing can accommodate.
Examples include:
A discounted off-market acquisition.
A seller requiring a shortened closing period.
A commercial property auction.
A distressed asset sale.
A purchase with limited due diligence or financing contingencies.
A bridge lender with an established underwriting process may close more quickly than a conventional lender, although actual timelines depend on appraisal, title, environmental review, borrower documentation, and transaction complexity.
Speed can create a competitive advantage, but it should never replace proper due diligence.
Before committing to bridge financing, investors should calculate whether the acquisition discount justifies the higher financing costs.
Best fit: Time-sensitive transactions where the value of closing quickly outweighs the additional cost and risk of short-term debt.
4. Refinancing a Maturing Commercial Mortgage
Commercial loan maturities are another major reason borrowers consider bridge financing.
Many commercial mortgages have balloon payments requiring borrowers to refinance or repay the remaining principal at maturity.
Unfortunately, the property may not qualify for permanent refinancing when the loan comes due.
Potential reasons include:
Higher prevailing interest rates.
Reduced property valuations.
Lower debt service coverage ratios.
Declining occupancy.
Pending lease expirations.
Deferred maintenance.
Tighter lender underwriting.
A commercial bridge refinance may provide additional time to improve property performance, contribute equity, complete leasing, or prepare for a sale.
However, a bridge loan does not automatically solve a capital shortfall.
If the existing mortgage payoff exceeds the amount a bridge lender is willing to advance, the borrower may need to contribute additional cash or negotiate with the current lender.
Best fit: Properties with a temporary refinancing obstacle and a realistic plan to resolve it.
5. Stabilizing a Property Before Permanent Financing
A property's income may improve substantially after acquisition, but permanent lenders generally need evidence that the improvement is sustainable.
Consider an investor who purchases a partially vacant industrial property.
After completing improvements and securing additional tenants, the property may eventually generate enough net operating income to support long-term financing.
Bridge financing can provide time to:
1.Complete capital improvements.
2.Lease available space.
3.Establish consistent rental collections.
4.Document operating performance.
5.Qualify for permanent financing.
This strategy is sometimes called bridge-to-permanent financing.
The objective is to replace short-term debt with financing that offers a more appropriate long-term capital structure.
Investors should verify the permanent lender's occupancy, seasoning, DSCR, and property-condition requirements before taking out the bridge loan.
6. Resolving Temporary Property or Documentation Issues
Sometimes an otherwise attractive commercial property cannot qualify for conventional financing because of a temporary issue.
Examples include unresolved property repairs, incomplete financial records, pending certificates of occupancy, lease documentation gaps, or an operational transition.
A bridge lender may be willing to evaluate the transaction while those issues are corrected.
However, bridge financing is not a substitute for legal compliance, insurable title, acceptable environmental conditions, or a property that can safely support the proposed use.
The borrower must establish a clear timeline, budget, and process for resolving the problem.
Best fit: Correctable issues with a defined solution, rather than fundamental problems with the property's economics or marketability.
7. Financing a Commercial Property Repositioning Strategy
Commercial real estate investors increasingly encounter properties that need to adapt to changing tenant demand.
An older office building might require new layouts, updated common areas, and a revised leasing strategy.
A vacant retail property might need substantial improvements before attracting replacement tenants.
Bridge financing can support the repositioning period when conventional lenders are unwilling to rely on speculative future income.
The investor's success depends on more than obtaining financing. It also depends on understanding tenant demand, renovation costs, lease-up timing, and the property's competitive position.
A lender will want to see a credible business plan supported by market evidence.
Commercial Bridge Loan Example: Multifamily Value-Add Acquisition
Let's examine a hypothetical investment.
An investor identifies a 24-unit apartment building with below-market rents and deferred maintenance.
Investment Component | Amount |
Acquisition price | $2,000,000 |
Renovation budget | $300,000 |
Total project cost | $2,300,000 |
Hypothetical bridge loan | $1,725,000 |
Initial equity requirement | $575,000 |
Projected stabilized value | $3,000,000 |
The proposed bridge loan represents 75% of total project cost, assuming all stated costs are eligible.
Suppose the bridge loan carries a hypothetical 10% annual interest rate, with interest-only payments.
Monthly interest expense on the fully funded loan:
$1,725,000 × 10% ÷ 12 = $14,375
Over 18 months, that equals approximately $258,750 in interest if the entire principal is outstanding throughout the period.
Actual interest could be lower if renovation funds are advanced gradually, or higher if rates change or the loan is extended. Origination fees, legal expenses, appraisal costs, construction administration, reserves, and closing costs would be additional.
Now assume the investor successfully completes renovations and achieves a stabilized value of $3 million.
A hypothetical permanent refinance at 70% LTV could produce:
$3,000,000 × 70% = $2,100,000
After paying off the $1,725,000 bridge principal, the difference would be $375,000 before refinancing costs, accrued interest, reserves, and other obligations.
Here's the critical point: That $2.1 million refinance is not guaranteed.
The permanent lender must also approve the property's cash flow, DSCR, borrower qualifications, appraisal, and other underwriting requirements.
If the property stabilizes at only $2.5 million, a 70% LTV refinance would generate $1.75 million—leaving very little margin after the bridge loan payoff.
This is why successful bridge financing requires more than an optimistic future appraisal.
What Do Commercial Bridge Loan Lenders Look For?
Bridge lenders generally evaluate five major factors.
1. Property value and collateral quality
The lender will evaluate the current property's value, physical condition, marketability, and location. Some lenders also consider an as-stabilized value.
2. Borrower experience
An investor with a documented history of completing renovations and leasing commercial properties may be more attractive to lenders.
3. Liquidity and equity
Borrowers often need sufficient cash for the down payment, closing costs, debt service, capital improvements, and unexpected expenses.
4. Business plan
The lender needs to understand how the borrower will improve the property's financial position.
5. Exit strategy
The most important question is often: How will this bridge loan be repaid when it matures?
A credible exit should be supported by realistic valuation, cash flow, financing assumptions, and market conditions.
Bridge Loan vs. Conventional Commercial Mortgage
Feature | Bridge Loan | Conventional Loan |
Primary purpose | Transitional financing | Long-term ownership |
Typical term | 6–36 months | Often 5–10 years to maturity, sometimes longer |
Pricing | Generally higher | Generally lower for comparable risk |
Payment structure | Often interest-only | Often amortizing |
Property condition | Can accommodate transitional assets | Usually favors stabilized assets |
Underwriting emphasis | Collateral, sponsor, business plan, exit | Cash flow, DSCR, collateral, sponsor |
Main risk | Maturity and exit risk | Rate resets, balloon maturities, ongoing debt service |
Terms vary significantly by lender and property type.
When Should You Avoid a Commercial Bridge Loan?
A bridge loan may be the wrong financing solution when:
The property already qualifies for competitively priced permanent financing.
The business plan depends on unrealistic rent growth or appreciation.
The borrower lacks sufficient liquidity.
The projected renovation schedule is uncertain.
There is no reliable refinance or sale strategy.
The investment cannot support the cost of short-term financing.
Extension fees or maturity risk could erase the anticipated return.
Bridge financing should solve a temporary problem—not conceal a permanent weakness.
Five Questions to Ask Before Accepting Bridge Financing
Before signing a commercial bridge loan commitment, ask:
1.What is my total borrowing cost? Include interest, origination fees, exit fees, extension fees, and third-party costs.
2.How much capital must I contribute? Determine equity, reserves, and potential cash shortfalls.
3.What happens if renovations or leasing take longer than expected? Understand extension rights and costs.
4.Will the projected property qualify for permanent refinancing? Stress-test LTV, DSCR, and appraisal assumptions.
5.What is my backup exit strategy? Evaluate a sale, equity contribution, lender extension, or other feasible alternative.
These questions can reveal risks that aren't apparent from the quoted interest rate alone.
How the CommLoan Empower Program Can Help
Commercial real estate financing is not one-size-fits-all.
Different lenders specialize in different asset classes, loan sizes, leverage structures, and risk profiles.
Through the CommLoan Empower Program, I help commercial real estate investors and business owners evaluate financing options using a marketplace approach rather than relying exclusively on a single bank.
Whether you're acquiring a value-add multifamily property, repositioning a retail center, financing an industrial acquisition, or addressing a commercial loan maturity, the goal is to identify a financing structure that fits the property's current condition and your long-term investment objectives.
The bottom line: A commercial bridge loan can be a powerful tool when the opportunity is sound, the business plan is executable, and the exit strategy is realistic.
Ready to Explore Commercial Bridge Financing?
I'm Bill Rapp, CCIM, and I work with commercial real estate investors and business owners through the CommLoan Empower Program.
If you're considering a commercial bridge loan, let's review your transaction, financing needs, and exit strategy.
Explore your commercial financing options:
Top of Form
Bottom of Form
Bill Rapp, CCIM
Director | CommLoan
📞 281-222-0433
📧 [email protected]
🌐 https://billrapp.commloan.com/
🌐 https://HoustonCommercialMortgage.com/
Commercial Real Estate Financing Nationwide
https://billrapp.commloan.com/
https://author.billrapponline.com/
https://www.amazon.com/dp/B0F32Z5BH2
https://veed.cello.so/FOmzTty6oi9
https://buymeacoffee.com/vikingente3
https://creplaybookseries.billrapponline.com
https://creplaybook.billrapponline.com/
©Bill Rapp, CCIM - Director - CommLoan
10 Tips for First-Time Homebuyers
Buying your first home can be both exciting and nerve-wracking at the same time. With so many things to consider and....
How To Choose the Right Lender for You
Lorem Ipsum is simply dummy text of the printing and typesetting industry. Lorem Ipsum has been the industry's standard dummy
Refinancing youe loan and when to do it
Lorem Ipsum is simply dummy text of the printing and typesetting industry. Lorem Ipsum has been the industry's standard dummy
Copyright ©2021 | Mortgage Viking Team
Licensed to Do Business | NMLS # 228246
This is not an offer to enter into an agreement. Not all customers will qualify. Information, rates and programs are subject to change without notice. All products are subject to credit and property approval. Other restrictions and limitations may apply. Copyright © 2021 | Medallion Funds
Corporate | NMLS ID NMLS # 1825831
Corporate Address : 2651 N. Green Valley Pkwy STE. 101 Henderson, NV 89014
Corporate NMLS NMLS # 1825831 | Company Website: https://medallionfunds.com/bill-rapp/
Copyright ©2021 | Mortgage Viking Team Licensed to Do Business | NMLS # 228246
This is not an offer to enter into an agreement. Not all customers will qualify. Information, rates and programs are subject to change without notice. All products are subject to credit and property approval. Other restrictions and limitations may apply
Corporate | NMLS ID NMLS # 1825831
Corporate Address : 2651 N. Green Valley Pkwy STE. 101 Henderson, NV 89014 https://medallionfunds.com/bill-rapp/
Facebook
Instagram
X
LinkedIn
Youtube
TikTok