Low Rates.
Our rates are low, our application is quick and easy! We can get you clear to close in as little as 10 days!
Trusted By Agents With
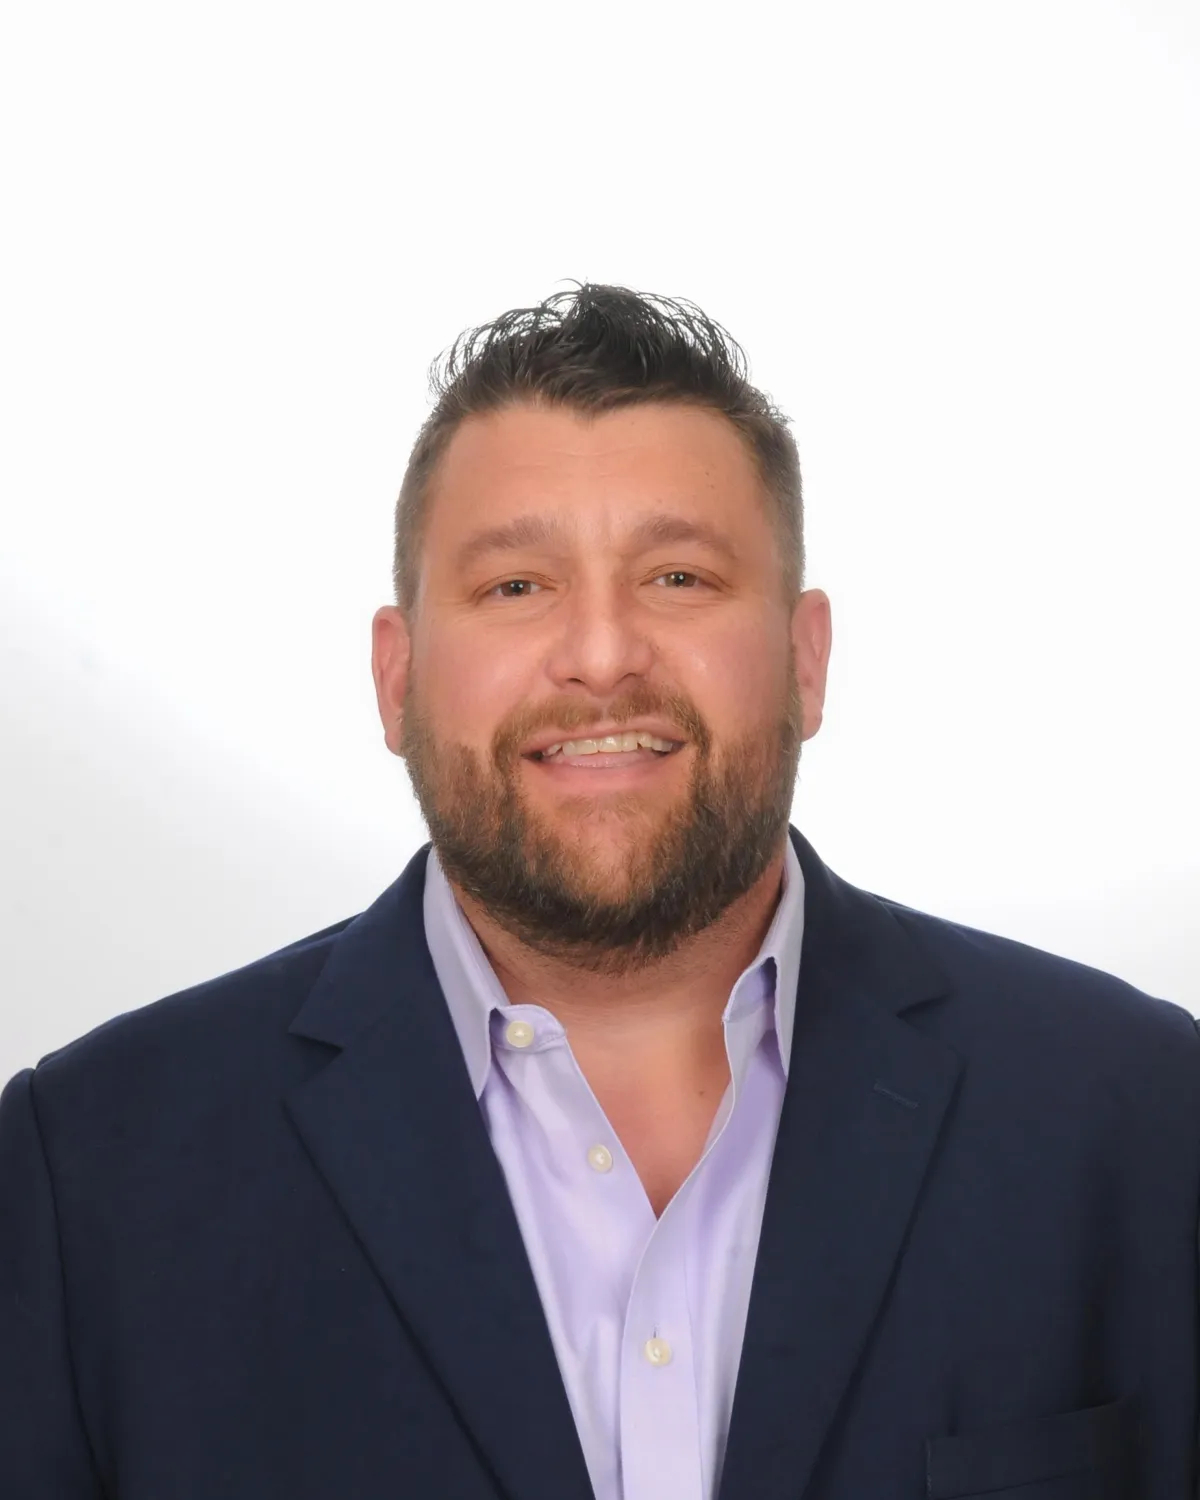
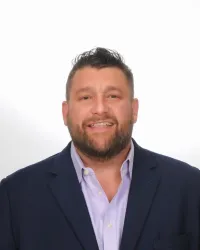
Meet Bill Rapp
NMLS ID # NMLS # 228246
Bill Rapp, CCIM is a Houston-based Capital Advisor at Medallion Funds, specializing in commercial real estate finance and strategic lending solutions. With over two decades of experience across brokerage and capital markets, Bill has worked with leading firms including eXp Commercial, NEXA Mortgage, Viking Enterprise LLC, and Sun Realty Houston.
A graduate of Texas A&M University with a BBA in Finance, Bill brings a disciplined, underwriting-first approach to every deal. His expertise spans commercial and residential financing, including asset-based lending, FHA financing, reverse mortgages, REO properties, and investment strategies for both single-family and commercial assets.
Known for his focus on structure over rate, Bill helps investors, business owners, and developers navigate complex transactions with clarity, precision, and a long-term wealth-building mindset.
The Client Experience
Great experience purchasing our first home! Bill was easy to reach and always able to answer any questions or concerns.

Loan Programs Available


Blogs
The Top 5 Mortgage Mistakes to Avoid
Buying your first home can be both exciting and nerve-wracking at the same time. With so many things to consider and....
Mortgage Do and
Do not list
Mortgages can be tricky, and it's easy to make mistakes that can end up costing you dearly. That's why we've put together this list....
Tips On How To Improve Your Credit Score
Let's talk about some ways you can improve your credit score! Your credit score is actually a big deal, and it can affect...
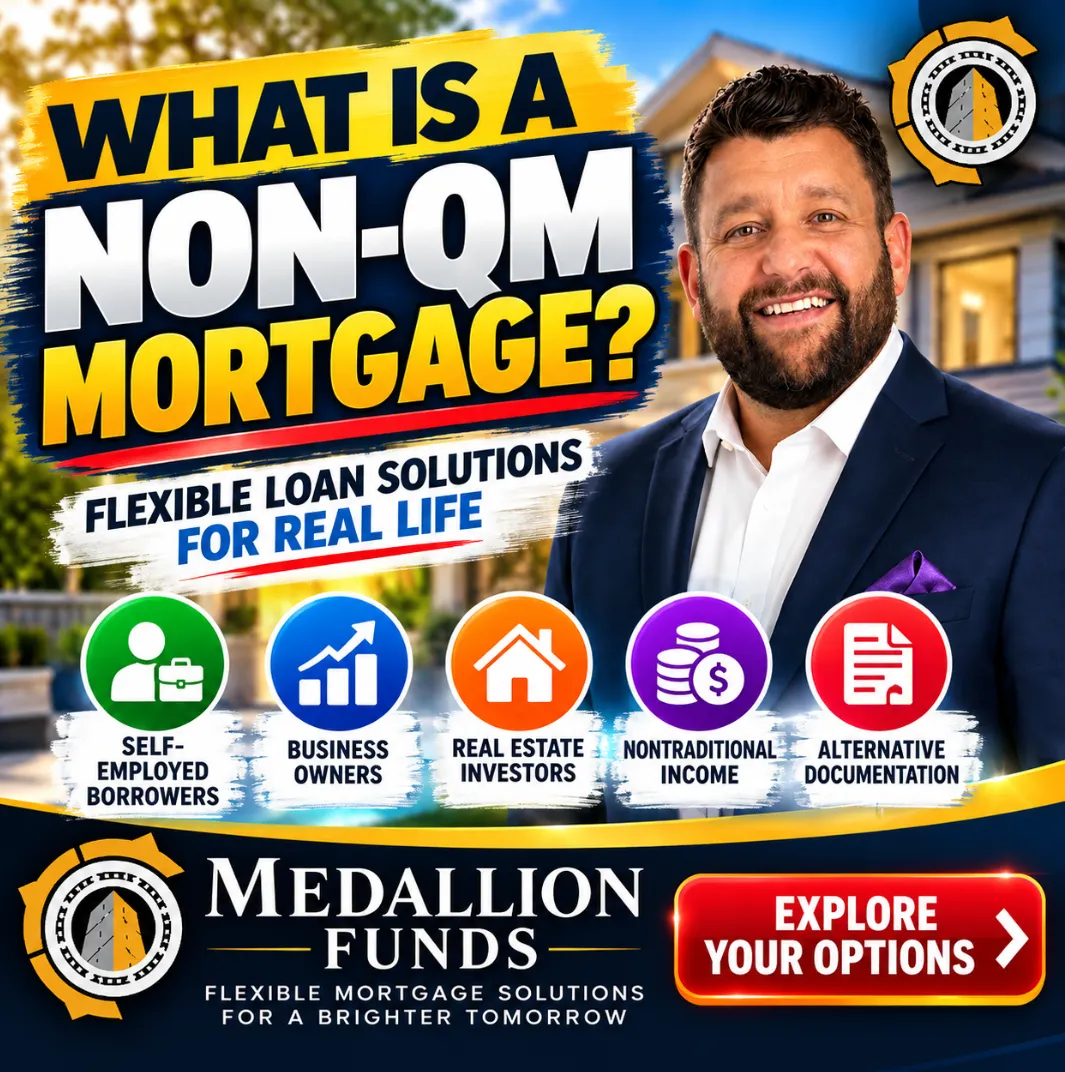
🏠 What Is a Non-QM Mortgage? A Complete Guide for Self-Employed & Nontraditional Borrowers 🔑
🏠 What Is a Non-QM Mortgage? A Complete Guide for Self-Employed & Nontraditional Borrowers 🔑
💰 Non-QM Mortgages Explained: Flexible Home Loan Options Beyond Conventional Financing 🏡
________________________________________________________________________________
What Is a Non-QM Mortgage?
Getting approved for a mortgage is not always as simple as having good credit, sufficient income, and money for a down payment.
For self-employed borrowers, real estate investors, business owners, retirees, and borrowers with nontraditional income, the bigger challenge may be documenting income in the way traditional mortgage programs expect.
That is where a Non-QM mortgage may provide another path to financing.
At Medallion Funds, we help borrowers evaluate traditional and alternative mortgage programs to identify financing that fits their income, property, and overall financial profile.
What Does Non-QM Mean?
Non-QM stands for Non-Qualified Mortgage.
A Non-QM mortgage is a loan that does not meet all of the criteria required for a Qualified Mortgage under federal regulations. That does not automatically mean the loan is unsafe, unregulated, or designed for borrowers with poor credit.
Instead, Non-QM lenders may use alternative underwriting approaches for borrowers whose financial circumstances do not fit neatly into traditional agency mortgage guidelines.
The key distinction is often how the borrower demonstrates the ability to repay the mortgage.
Who May Benefit From a Non-QM Mortgage?
Non-QM loans can be particularly useful when a borrower has strong financial capacity but traditional documentation does not accurately represent that person's finances.
Potential candidates include:
·Self-employed borrowers
·Business owners
·Independent contractors
·Gig workers
·Real estate investors
·Borrowers with substantial assets
·Borrowers with irregular or multiple income streams
·Borrowers who recently experienced a credit event
·Foreign nationals or other borrowers requiring specialized financing
Every program has different eligibility requirements, so being in one of these categories does not automatically qualify someone for a Non-QM loan.
Bank Statement Loans for Self-Employed Borrowers
One of the best-known Non-QM products is the bank statement mortgage.
Traditional mortgage underwriting frequently relies heavily on tax returns, W-2 income, and other conventional income documentation. This can create challenges for business owners whose taxable income is substantially different from their actual business cash flow.
Depending on the program, a bank statement loan may analyze a specified period of personal or business bank statements to determine qualifying income.
This can make bank statement mortgages worth exploring for entrepreneurs and self-employed professionals.
DSCR Loans for Real Estate Investors
Another popular segment of Non-QM financing is the Debt Service Coverage Ratio, or DSCR, loan.
Instead of relying primarily on the investor's personal employment income, qualifying may focus heavily on the investment property's rental income relative to its required debt service.
For real estate investors building rental portfolios, this can provide an alternative to repeatedly qualifying based on personal income.
DSCR requirements, property eligibility, reserves, credit standards, leverage, and other underwriting criteria vary by lender and program.
Asset-Based and Asset-Utilization Mortgages
Some borrowers have significant wealth but relatively little traditional monthly income.
Consider a retiree or entrepreneur with substantial investment assets who reports comparatively low taxable income. Traditional underwriting may not fully capture that borrower's financial strength.
Certain Non-QM programs may allow eligible assets to be incorporated into the income qualification methodology.
These programs can be especially relevant for high-net-worth borrowers whose financial profiles are asset-rich but income-light.
Are Non-QM Loans the Same as Subprime Mortgages?
No.
Although the terms are sometimes incorrectly used interchangeably, Non-QM does not simply mean subprime.
A borrower might have excellent credit, substantial reserves, significant assets, and a large down payment yet still need a Non-QM mortgage because of the way their income is earned or documented.
The issue may not be financial weakness. It may simply be that the borrower does not fit the standardized documentation framework of a traditional mortgage.
What Are the Potential Downsides?
The additional flexibility offered by Non-QM financing can come at a cost.
Depending on the borrower and program, Non-QM mortgages may have:
·Higher interest rates
·Larger down-payment requirements
·Greater reserve requirements
·Different credit-score standards
·Additional documentation requirements
·Different prepayment provisions on certain investment-property loans
·Higher lender fees or pricing adjustments
This is why borrowers should compare the entire loan structure, not simply the interest rate.
Non-QM vs. Conventional Mortgage
A conventional mortgage may be preferable when the borrower comfortably meets traditional underwriting standards and the program accomplishes the borrower's objectives.
But Non-QM financing can provide alternatives when conventional guidelines create unnecessary obstacles.
For example, imagine a successful business owner with strong cash flow, excellent credit, substantial reserves, and a meaningful down payment. Aggressive but legitimate business deductions could result in tax returns showing insufficient qualifying income for a conventional mortgage.
A Non-QM lender may have alternative methods for analyzing that borrower.
That does not necessarily make Non-QM better. It simply makes it another financing tool.
How a Mortgage Broker Can Help
Non-QM lending is not a single mortgage program.
Different wholesale lenders can have materially different guidelines for bank statements, DSCR calculations, asset utilization, credit history, property types, reserves, loan amounts, and other underwriting considerations.
Working with a mortgage broker can help you compare potential solutions rather than assuming one lender's guidelines represent the entire market.
At Medallion Funds, our objective is to understand the borrower's complete financial picture before determining which lending options warrant consideration.
Is a Non-QM Mortgage Right for You?
A Non-QM mortgage may be worth evaluating if you have the financial capacity to purchase or refinance real estate but have difficulty qualifying under conventional income-documentation standards.
The question is not simply:
“Can I qualify for a Non-QM loan?”
A better question is:
“Which mortgage structure provides the best combination of qualification, payment, cash requirement, flexibility, and long-term cost for my situation?”
That is the conversation borrowers should have before choosing a mortgage.
Medallion Funds | Flexible Mortgage Solutions
Bill Rapp
Partner & Director of Capital Advisory | Medallion Funds
Commercial Lending Nationwide
Residential Lending in AL, CA, CO, NV & TXBottom of Form
https://www.billrapponline.com/
https://findamortgagebroker.com/Profile/WilliamRappJr28883
https://billrapp.commloan.com/
https://billrapponline.com/financingfuturescre-houston-katy
https://houstoncommercialmortgage.com/
https://author.billrapponline.com
https://doctorvideo.billrapponline.com/
https://veteransvideo.billrapponline.com/
https://mortgageviking.billrapponline.com/
https://fha203h.billrapponline.com/
https://renovationvideo.billrapponline.com
https://medallionfunds.com/bill-rapp/
https://www.amazon.com/dp/B0F32Z5BH2
https://veed.cello.so/FOmzTty6oi9
https://buymeacoffee.com/vikingente3
https://creplaybookseries.billrapponline.com
https://creplaybook.billrapponline.com/
© Bill Rapp, Medallion Funds LLC, Director of Capital Advisory
10 Tips for First-Time Homebuyers
Buying your first home can be both exciting and nerve-wracking at the same time. With so many things to consider and....
How To Choose the Right Lender for You
Lorem Ipsum is simply dummy text of the printing and typesetting industry. Lorem Ipsum has been the industry's standard dummy
Refinancing youe loan and when to do it
Lorem Ipsum is simply dummy text of the printing and typesetting industry. Lorem Ipsum has been the industry's standard dummy
Copyright ©2021 | Mortgage Viking Team
Licensed to Do Business | NMLS # 228246
This is not an offer to enter into an agreement. Not all customers will qualify. Information, rates and programs are subject to change without notice. All products are subject to credit and property approval. Other restrictions and limitations may apply. Copyright © 2021 | Medallion Funds
Corporate | NMLS ID NMLS # 1825831
Corporate Address : 2651 N. Green Valley Pkwy STE. 101 Henderson, NV 89014
Corporate NMLS NMLS # 1825831 | Company Website: https://medallionfunds.com/bill-rapp/
Copyright ©2021 | Mortgage Viking Team Licensed to Do Business | NMLS # 228246
This is not an offer to enter into an agreement. Not all customers will qualify. Information, rates and programs are subject to change without notice. All products are subject to credit and property approval. Other restrictions and limitations may apply
Corporate | NMLS ID NMLS # 1825831
Corporate Address : 2651 N. Green Valley Pkwy STE. 101 Henderson, NV 89014 https://medallionfunds.com/bill-rapp/
Facebook
Instagram
X
LinkedIn
Youtube
TikTok