Low Rates.
Our rates are low, our application is quick and easy! We can get you clear to close in as little as 10 days!
Trusted By Agents With
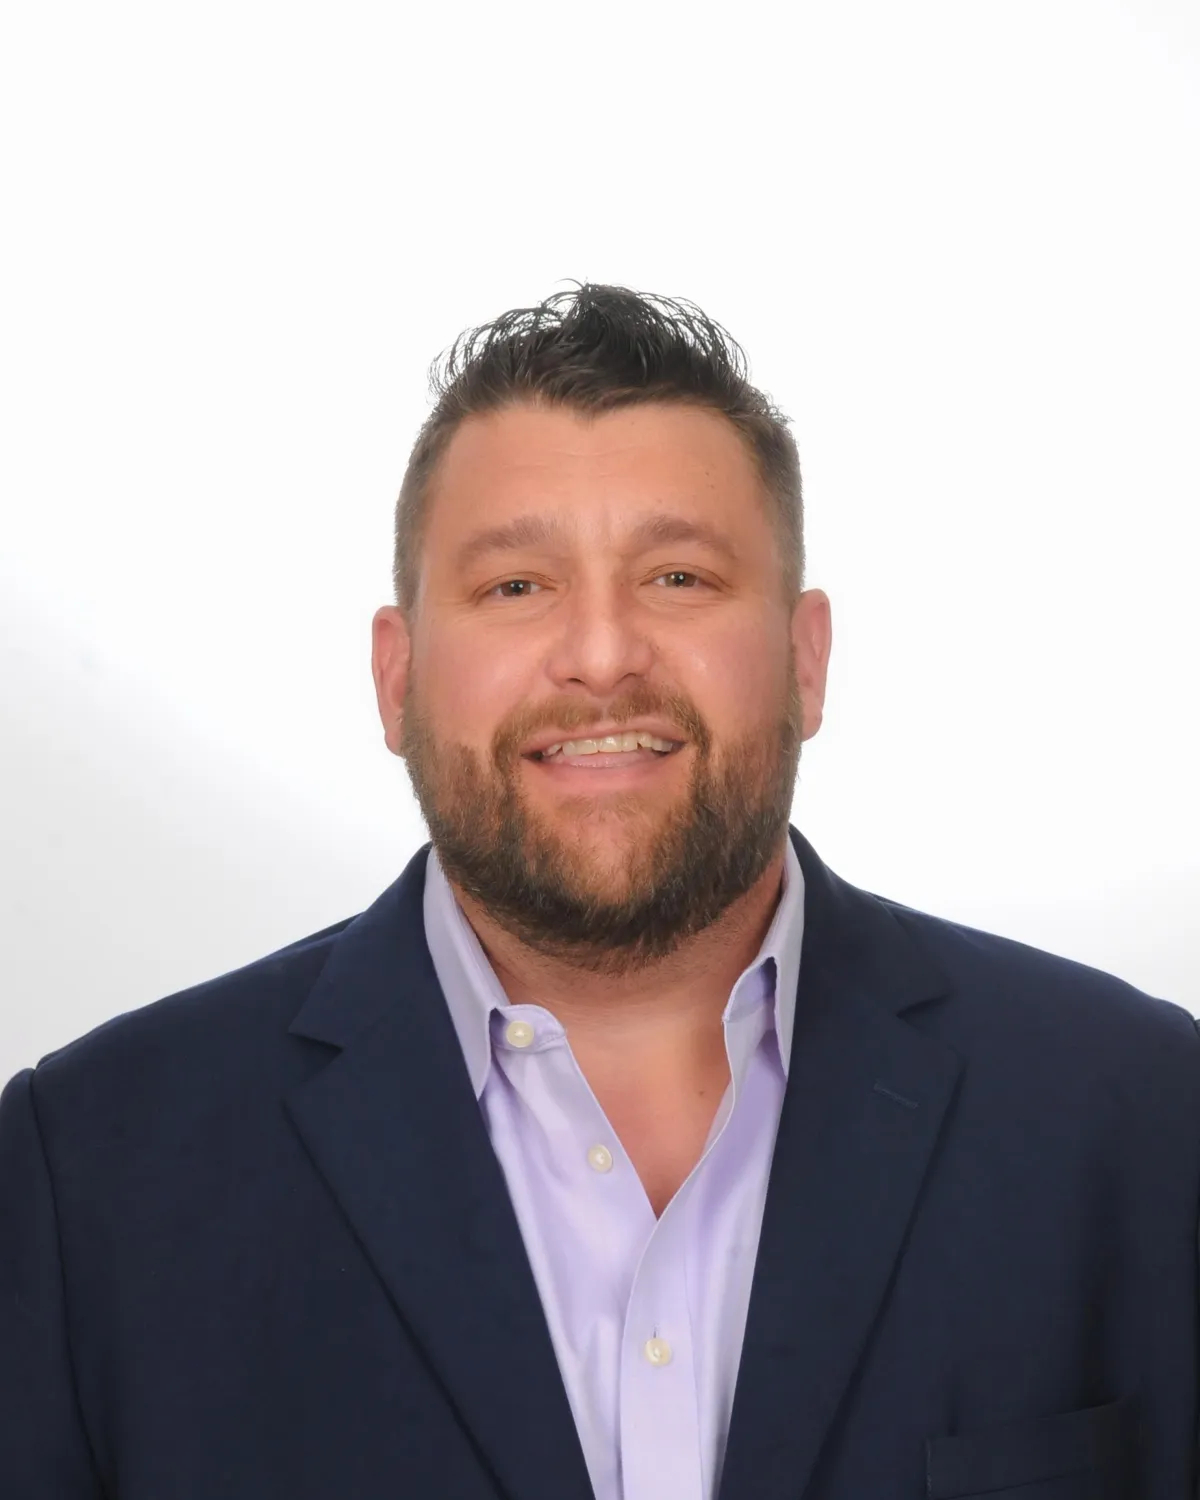
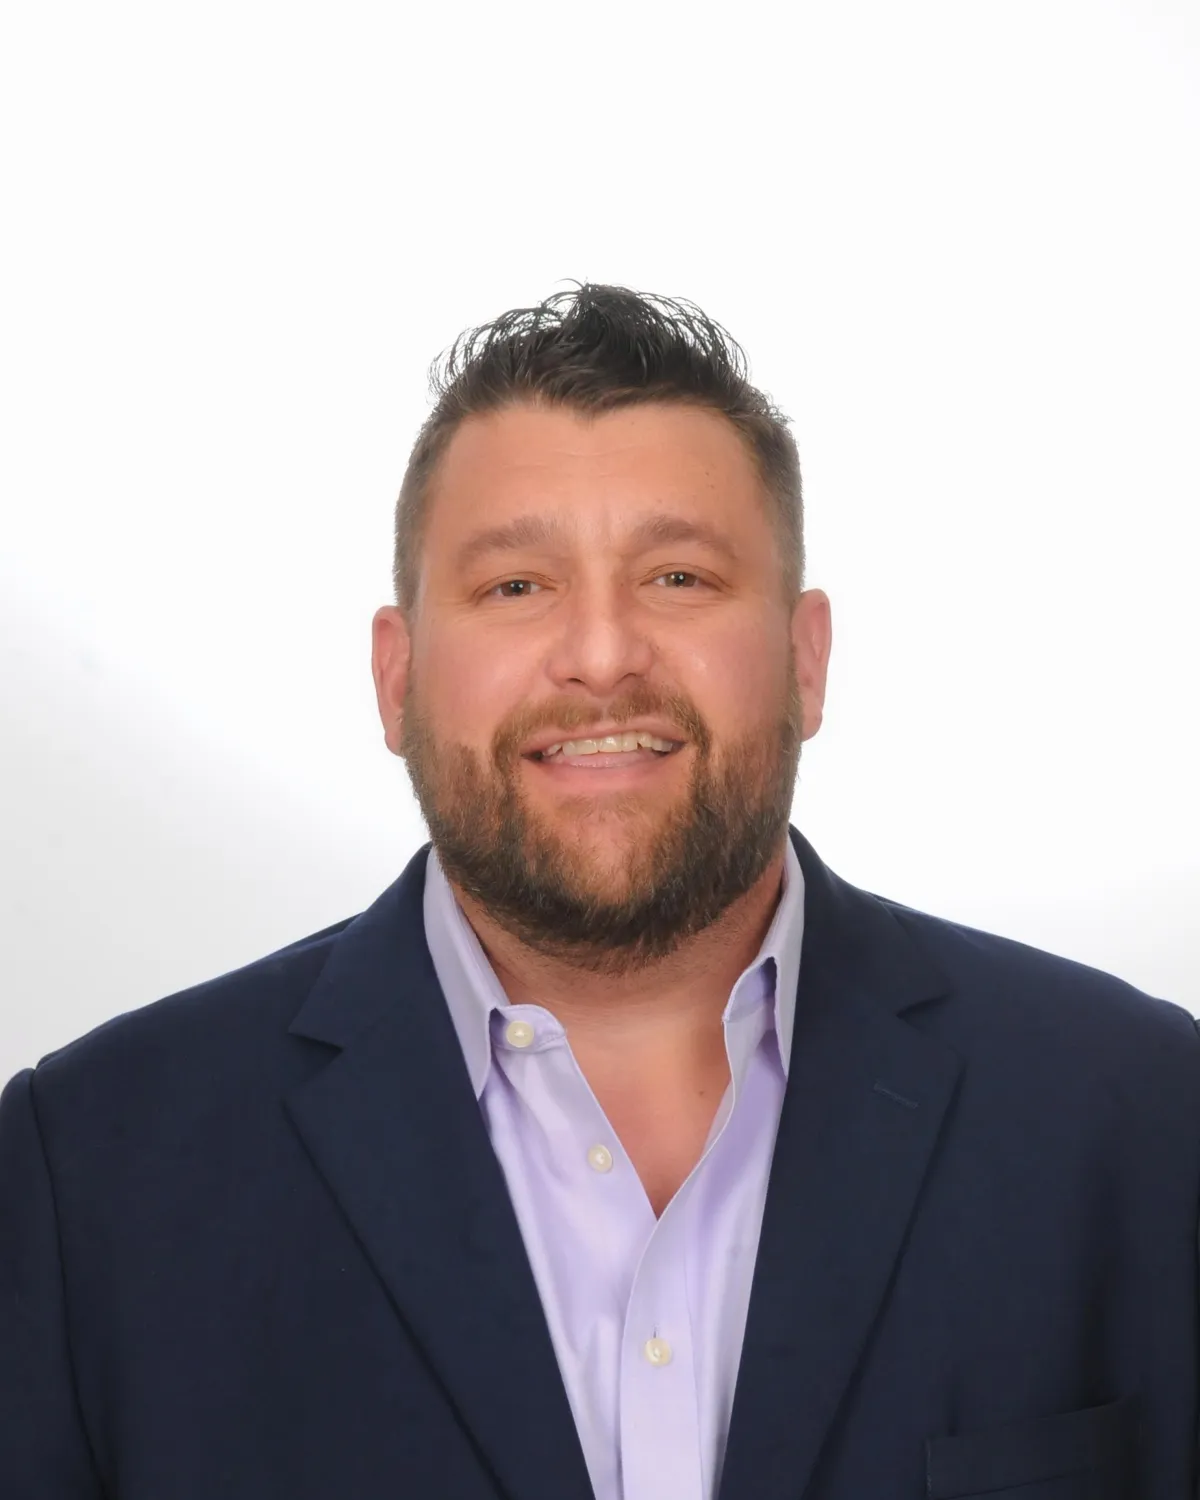
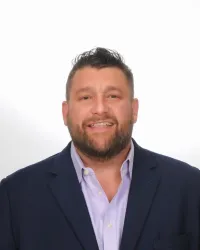
Meet Bill Rapp
NMLS ID # NMLS # 228246
Bill Rapp, CCIM is a Houston-based Capital Advisor at Medallion Funds, specializing in commercial real estate finance and strategic lending solutions. With over two decades of experience across brokerage and capital markets, Bill has worked with leading firms including eXp Commercial, NEXA Mortgage, Viking Enterprise LLC, and Sun Realty Houston.
A graduate of Texas A&M University with a BBA in Finance, Bill brings a disciplined, underwriting-first approach to every deal. His expertise spans commercial and residential financing, including asset-based lending, FHA financing, reverse mortgages, REO properties, and investment strategies for both single-family and commercial assets.
Known for his focus on structure over rate, Bill helps investors, business owners, and developers navigate complex transactions with clarity, precision, and a long-term wealth-building mindset.
The Client Experience
Great experience purchasing our first home! Bill was easy to reach and always able to answer any questions or concerns.

Loan Programs Available


Blogs
The Top 5 Mortgage Mistakes to Avoid
Buying your first home can be both exciting and nerve-wracking at the same time. With so many things to consider and....
Mortgage Do and
Do not list
Mortgages can be tricky, and it's easy to make mistakes that can end up costing you dearly. That's why we've put together this list....
Tips On How To Improve Your Credit Score
Let's talk about some ways you can improve your credit score! Your credit score is actually a big deal, and it can affect...
🏭 Warehouse Financing: What Banks Really Want 💰
🏭 Warehouse Financing: What Banks Really Want 💰
🏦 Industrial Property Loans: Warehouse & Flex Space 🔑
________________________________________________________________________________
🏭 Warehouse Financing: What Banks Really Want 💰
Industrial Property Financing: Warehouse and Flex Space Loans
Banks love some warehouses—and avoid others. Two industrial buildings can have nearly identical square footage, similar locations, and comparable purchase prices, yet receive dramatically different financing offers.
Why?
Because commercial lenders evaluate much more than the building's value.
They examine the property's functionality, tenant quality, cash flow, environmental exposure, borrower financial strength, and potential resale market.
Whether you're purchasing a distribution warehouse, investing in a multi-tenant flex property, or acquiring an industrial building for your own business, understanding how warehouse financing works can help you avoid expensive mistakes.
Let's examine what commercial lenders really want.
What Is Warehouse Financing?
Warehouse financing refers to commercial real estate loans used to purchase, refinance, construct, or improve warehouse and industrial properties.
These loans commonly finance:
Distribution centers and logistics facilities
Small-bay industrial warehouses
Flex warehouse and office properties
Manufacturing facilities
Contractor warehouses and service facilities
Cold-storage and specialized industrial buildings
Owner-occupied industrial properties
Multi-tenant industrial investment properties
Unlike residential mortgages, industrial property loans are underwritten based on the property's income potential, collateral characteristics, and the borrower's ability to repay.
A lender financing a 20,000-square-foot distribution warehouse may approach the transaction differently than a lender financing a 20,000-square-foot manufacturing facility with specialized equipment and limited alternative uses.
The type of industrial building matters just as much as its size.
Why Banks Love Some Warehouses and Avoid Others
Not every warehouse represents the same lending risk.
1. Building Functionality and Marketability
Lenders prefer industrial properties that can attract multiple potential occupants.
Important characteristics include:
Clear ceiling height
Dock-high and grade-level loading
Truck circulation and trailer access
Adequate parking
Functional office-to-warehouse ratios
Electrical service and three-phase power
Building condition and roof age
Fire protection and sprinkler systems
Zoning and permitted industrial uses
A modern distribution warehouse with efficient loading, sufficient clear height, and flexible interior space may be attractive to numerous tenants.
An older manufacturing facility with unusual layouts, obsolete systems, or highly specialized improvements may have fewer potential users.
That smaller buyer and tenant pool can affect the property's appraised value and lender appetite.
2. Tenant Quality and Lease Structure
For investment properties, lenders analyze the income supporting the loan.
A warehouse leased to a financially strong tenant under a long-term agreement may receive more favorable consideration than a similar property with short-term tenants and inconsistent collections.
Lenders typically review:
Tenant creditworthiness
Lease expiration dates
Rent rolls and payment histories
Vacancy and rollover risk
Tenant concentration
Market rental rates
Operating expenses and recoveries
Historical and projected net operating income
For multi-tenant industrial buildings, tenant diversification can reduce reliance on one business, although frequent turnover and management expenses may increase underwriting risk.
3. Debt Service Coverage Ratio
One of the most important metrics in warehouse financing is the debt service coverage ratio, or DSCR.
DSCR = Net Operating Income ÷ Annual Debt Service
For example:
Annual net operating income: $240,000
Annual principal and interest payments: $180,000
DSCR: 1.33x
This means the property generates approximately $1.33 in net operating income for every $1.00 of annual debt service.
Many commercial lenders target a DSCR of approximately 1.20x–1.30x or higher, depending on the property, borrower, loan program, and prevailing credit conditions.
Some lenders may require stronger coverage for specialized or higher-risk properties.
For owner-occupied warehouses, lenders generally place greater emphasis on business cash flow and global repayment capacity rather than relying solely on property-level NOI.
Warehouse Financing Options for Investors and Business Owners
Different industrial properties require different capital structures.
Conventional Bank and Credit Union Loans
Traditional commercial lenders frequently finance stabilized warehouses and owner-occupied industrial buildings.
Typical characteristics may include:
Approximately 65%–80% loan-to-value
Five- to ten-year loan terms
Amortization schedules often extending 20–25 years
Fixed or floating interest rates
Possible balloon payments at maturity
Borrower liquidity and guaranty requirements
Actual leverage and terms depend on underwriting, bank policy, collateral, and borrower strength.
Conventional financing can work particularly well for established businesses and properties with stable occupancy.
SBA 504 Loans
The SBA 504 program can be attractive for eligible owner-occupied warehouse purchases and major fixed-asset projects.
A common structure is:
50% from a third-party lender
40% from a Certified Development Company-backed SBA debenture
10% borrower contribution
The borrower contribution may be higher for startups or special-purpose properties.
For existing buildings, the operating business generally must occupy at least 51% of the property to meet SBA owner-occupancy requirements.
SBA 504 financing is generally intended for eligible business-use fixed assets, not passive investment properties.
SBA 7(a) Loans
SBA 7(a) financing may also help qualifying businesses acquire warehouse property, particularly when the transaction includes eligible working capital, equipment, or other business financing needs.
Potential advantages include:
Lower equity requirements for some transactions
Longer repayment periods for real estate
Financing flexibility
Combined real estate and eligible business-purpose funding
SBA 7(a) real estate loans may have terms up to 25 years, subject to program requirements.
Bridge and Private Money Loans
Bridge financing may be appropriate when a warehouse does not qualify for permanent financing immediately.
Common scenarios include:
Significant vacancy
Deferred maintenance
Lease-up projects
Property repositioning
Time-sensitive acquisitions
Renovations before refinancing
Bridge loans generally carry higher borrowing costs and shorter terms than stabilized conventional loans.
A borrower should establish a credible exit strategy before accepting bridge financing.
Construction and Development Loans
Ground-up industrial development requires additional underwriting.
Lenders evaluate land costs, entitlements, construction budgets, contractor qualifications, leasing assumptions, market demand, and the developer's experience.
Speculative warehouse development may require greater equity and stronger financial support than a preleased or owner-occupied project.
Warehouse vs. Flex Space Financing: What's Different?
Warehouse and flex properties may appear similar, but their operating characteristics can be very different.
Traditional warehouses are primarily used for storage, distribution, or industrial operations.
Flex properties combine warehouse space with office, showroom, service, or light manufacturing areas.
A flex building with 20% office space and 80% warehouse space may attract a broad range of users.
A property with 70% office space and only 30% warehouse area may be evaluated differently, especially when local office demand is weak.
Lenders may consider:
Office-to-warehouse ratios
Tenant improvement costs
Tenant mix and lease rollover
Functional loading access
Local demand for small-bay industrial space
Ability to convert suites for future occupants
The more adaptable the property, the more options the owner may have if a tenant vacates.
Real-World Example: Two $4 Million Warehouses
Consider two hypothetical industrial acquisitions.
Warehouse A: Stabilized Distribution Facility
Purchase price: $4,000,000
Occupancy: 100%
Annual NOI: $300,000
Loan request: $2,800,000
Loan-to-value: 70%
Long-term lease with a financially established tenant
Functional loading and building layout
At a hypothetical 7.00% interest rate and 25-year amortization, annual debt service would be approximately $237,000.
That produces a DSCR of approximately 1.27x.
Warehouse A may fit the underwriting criteria of multiple conventional lenders.
Warehouse B: Vacant Manufacturing Facility
Purchase price: $4,000,000
Occupancy: 0%
Historical manufacturing use
Specialized building improvements
Significant deferred maintenance
No current property income
Potential environmental investigation required
Although the purchase prices are identical, Warehouse B presents substantially greater underwriting uncertainty.
A conventional investment-property lender may decline the transaction or require more equity.
A bridge lender might consider the property if the borrower has sufficient financial strength, an appropriate business plan, and a credible repayment or refinancing strategy.
If the buyer plans to occupy the property with an eligible operating business, conventional owner-user financing or an SBA program may offer another path.
The lesson: property price does not determine loan eligibility. Repayment capacity, building utility, and the borrower's business plan do.
Five Mistakes to Avoid When Financing Industrial Real Estate
Mistake 1: Assuming Every Warehouse Qualifies for the Same Loan
A stabilized distribution center and a vacant industrial redevelopment project may require completely different lenders.
Mistake 2: Ignoring Environmental Due Diligence
Previous industrial uses can create contamination concerns.
Lenders may require a Phase I Environmental Site Assessment and, when warranted, additional investigation.
Environmental problems can delay closing, increase costs, or prevent financing.
Mistake 3: Overlooking Electrical and Building Infrastructure
Three-phase power, adequate electrical capacity, loading access, roof condition, and fire protection can materially affect industrial property value.
A building wired for three-phase service does not necessarily mean the utility service is energized or sufficient for a proposed operation.
Confirm actual capacity and availability with qualified professionals.
Mistake 4: Focusing Only on the Interest Rate
Borrowers should compare loan-to-value, amortization, balloon maturity, prepayment penalties, recourse, reserves, and total financing costs.
A lower interest rate does not automatically make a loan the better choice.
Mistake 5: Waiting Until Closing to Evaluate Financing
Before entering a purchase agreement, investors should understand potential lender requirements.
Early financing analysis can identify issues involving occupancy, cash flow, appraisals, environmental assessments, and borrower liquidity.
How CommLoan Helps With Warehouse Financing
Industrial property financing is not a one-size-fits-all process.
At CommLoan, we use the CUPID™ commercial lending platform to evaluate financing opportunities across a broad network of lending sources.
Rather than approaching banks one by one, borrowers can explore financing structures that better align with their property type, business objectives, and financial profile.
As a commercial real estate professional and CCIM designee, I understand that the right financing strategy starts with understanding the real estate itself.
That includes analyzing property functionality, cash flow, tenant exposure, leverage, and the borrower's exit strategy.
Whether you're buying a warehouse, refinancing an industrial property, or financing a flex-space acquisition, getting the capital structure right can make a meaningful difference.
Frequently Asked Questions About Warehouse Financing
How much down payment do I need for a warehouse?
Many conventional investment-property loans require approximately 20%–35% equity, although requirements vary. Eligible SBA owner-occupied transactions may allow lower borrower contributions.
Can I finance a vacant warehouse?
Yes. Financing may be available through owner-occupied commercial programs, SBA loans, bridge lenders, or other sources, depending on the buyer's intended use and repayment capacity.
Can an LLC obtain a warehouse loan?
Yes. Commercial property loans are frequently made to LLCs or other entities, although lenders may require guarantees from individual owners or sponsors.
What credit score is needed for an industrial property loan?
There is no universal minimum across all commercial lenders. Credit history, financial strength, cash flow, experience, and the loan program all affect eligibility.
Can I finance a multi-tenant flex warehouse?
Yes. Lenders generally analyze occupancy, tenant quality, lease expirations, NOI, building functionality, and borrower strength.
Are warehouse loans typically fixed-rate?
Fixed-rate and floating-rate structures are both available. Some commercial loans have shorter terms than their amortization schedules, creating a balloon balance at maturity.
Final Thoughts: Finance the Property, Not Just the Purchase Price
Warehouse financing requires more than finding a lender willing to quote an interest rate.
The strongest financing strategy considers property condition, functional utility, tenant quality, repayment capacity, loan structure, and long-term investment objectives.
Two warehouses may look equally attractive on paper, but their financing outcomes can be very different.
Before you buy, refinance, or develop industrial real estate, understand how lenders will evaluate the property.
Ready to Explore Your Warehouse Financing Options?
I'm Bill Rapp, CCIM, Director at CommLoan.
Let me help you evaluate commercial financing options for your next warehouse, flex-space, or industrial real estate transaction.
Top of Form
Bottom of Form
Bill Rapp, CCIM
Director | CommLoan
📞 281-222-0433
📧 [email protected]
🌐 https://billrapp.commloan.com/
🌐 https://HoustonCommercialMortgage.com/
Commercial Real Estate Financing Nationwide
https://billrapp.commloan.com/
https://author.billrapponline.com/
https://www.amazon.com/dp/B0F32Z5BH2
https://veed.cello.so/FOmzTty6oi9
https://buymeacoffee.com/vikingente3
https://creplaybookseries.billrapponline.com
https://creplaybook.billrapponline.com/
©Bill Rapp, CCIM - Director - CommLoan
10 Tips for First-Time Homebuyers
Buying your first home can be both exciting and nerve-wracking at the same time. With so many things to consider and....
How To Choose the Right Lender for You
Lorem Ipsum is simply dummy text of the printing and typesetting industry. Lorem Ipsum has been the industry's standard dummy
Refinancing youe loan and when to do it
Lorem Ipsum is simply dummy text of the printing and typesetting industry. Lorem Ipsum has been the industry's standard dummy
Copyright ©2021 | Mortgage Viking Team
Licensed to Do Business | NMLS # 228246
This is not an offer to enter into an agreement. Not all customers will qualify. Information, rates and programs are subject to change without notice. All products are subject to credit and property approval. Other restrictions and limitations may apply. Copyright © 2021 | Medallion Funds
Corporate | NMLS ID NMLS # 1825831
Corporate Address : 2651 N. Green Valley Pkwy STE. 101 Henderson, NV 89014
Corporate NMLS NMLS # 1825831 | Company Website: https://medallionfunds.com/bill-rapp/
Copyright ©2021 | Mortgage Viking Team Licensed to Do Business | NMLS # 228246
This is not an offer to enter into an agreement. Not all customers will qualify. Information, rates and programs are subject to change without notice. All products are subject to credit and property approval. Other restrictions and limitations may apply
Corporate | NMLS ID NMLS # 1825831
Corporate Address : 2651 N. Green Valley Pkwy STE. 101 Henderson, NV 89014 https://medallionfunds.com/bill-rapp/
Facebook
Instagram
X
LinkedIn
Youtube
TikTok