Low Rates.
Our rates are low, our application is quick and easy! We can get you clear to close in as little as 10 days!
Trusted By Agents With
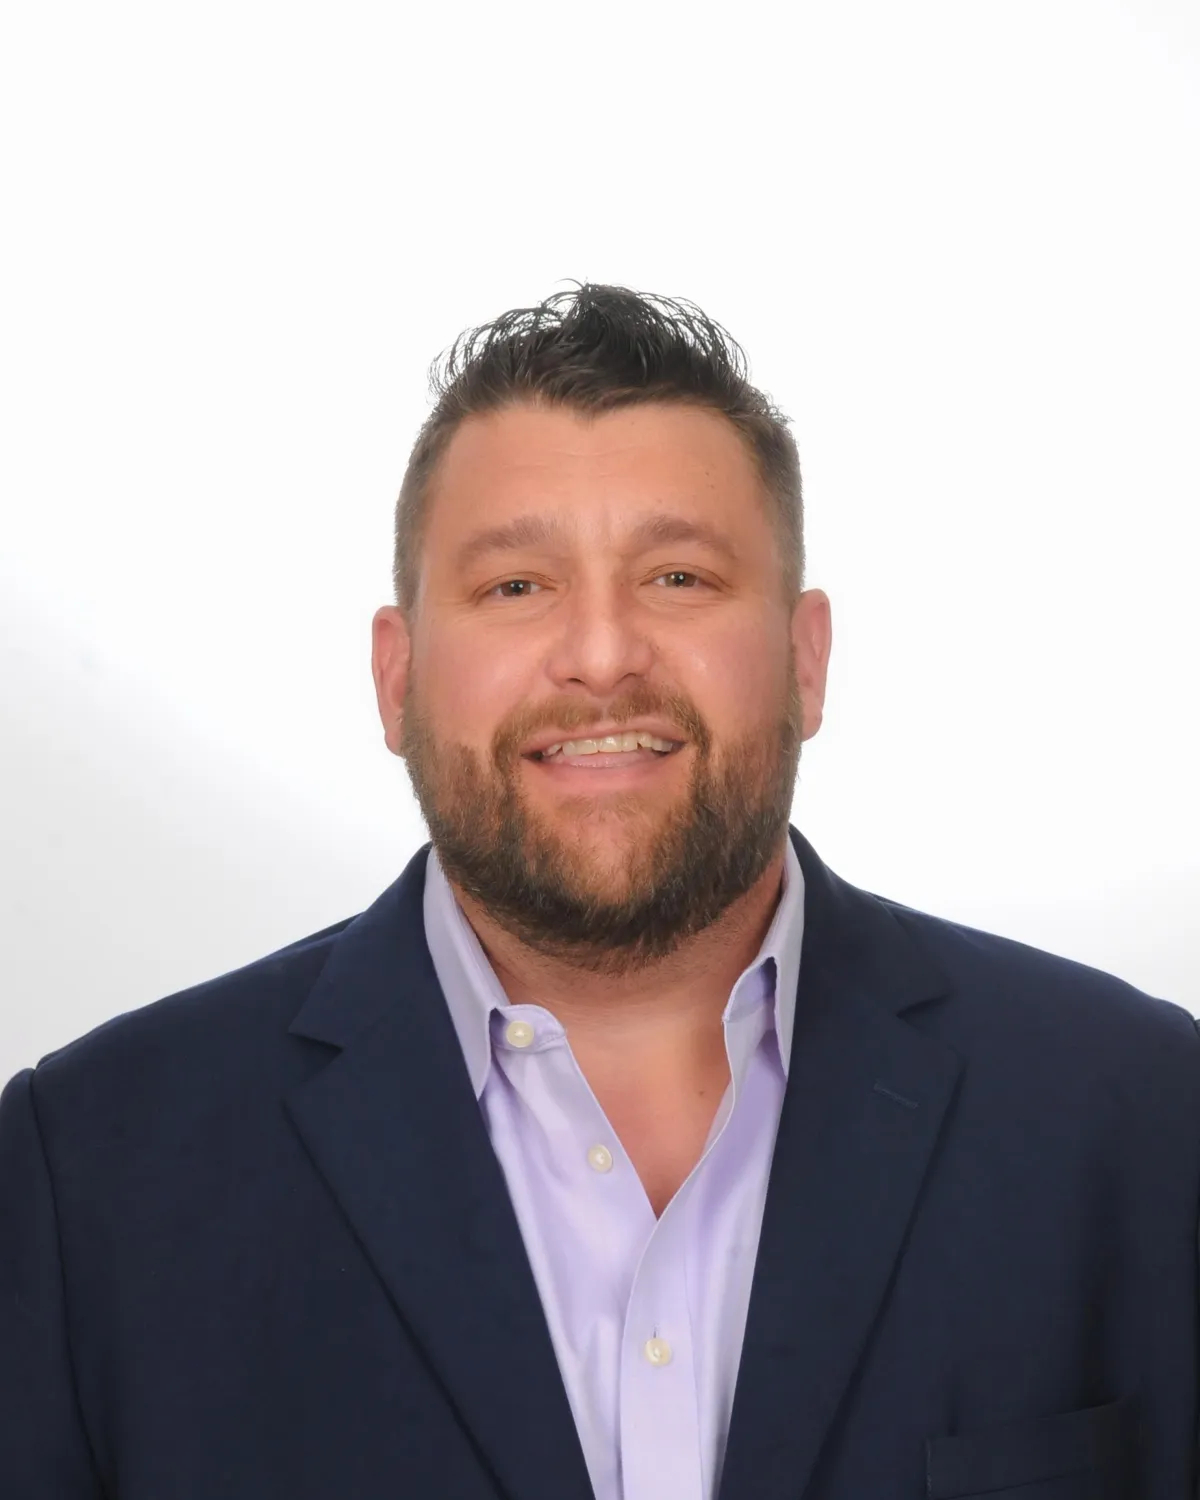
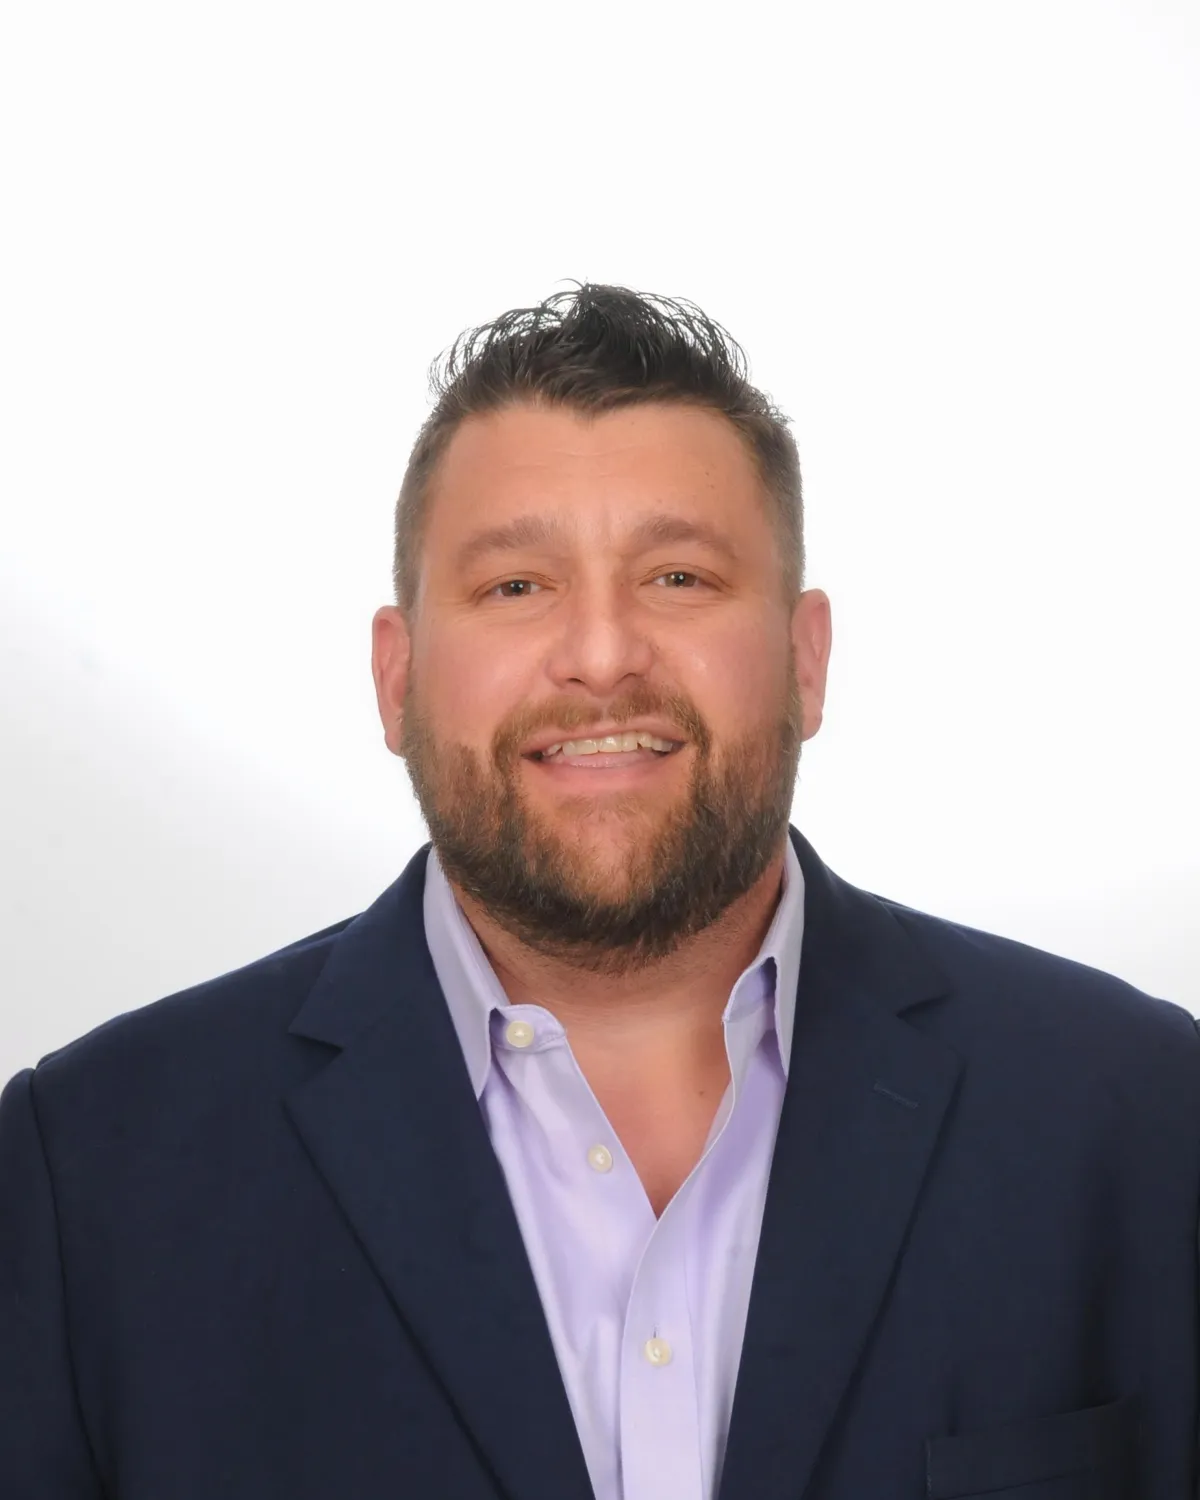
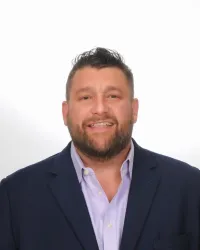
Meet Bill Rapp
NMLS ID # NMLS # 228246
Bill Rapp, CCIM is a Houston-based Capital Advisor at Medallion Funds, specializing in commercial real estate finance and strategic lending solutions. With over two decades of experience across brokerage and capital markets, Bill has worked with leading firms including eXp Commercial, NEXA Mortgage, Viking Enterprise LLC, and Sun Realty Houston.
A graduate of Texas A&M University with a BBA in Finance, Bill brings a disciplined, underwriting-first approach to every deal. His expertise spans commercial and residential financing, including asset-based lending, FHA financing, reverse mortgages, REO properties, and investment strategies for both single-family and commercial assets.
Known for his focus on structure over rate, Bill helps investors, business owners, and developers navigate complex transactions with clarity, precision, and a long-term wealth-building mindset.
The Client Experience
Great experience purchasing our first home! Bill was easy to reach and always able to answer any questions or concerns.

Loan Programs Available


Blogs
The Top 5 Mortgage Mistakes to Avoid
Buying your first home can be both exciting and nerve-wracking at the same time. With so many things to consider and....
Mortgage Do and
Do not list
Mortgages can be tricky, and it's easy to make mistakes that can end up costing you dearly. That's why we've put together this list....
Tips On How To Improve Your Credit Score
Let's talk about some ways you can improve your credit score! Your credit score is actually a big deal, and it can affect...
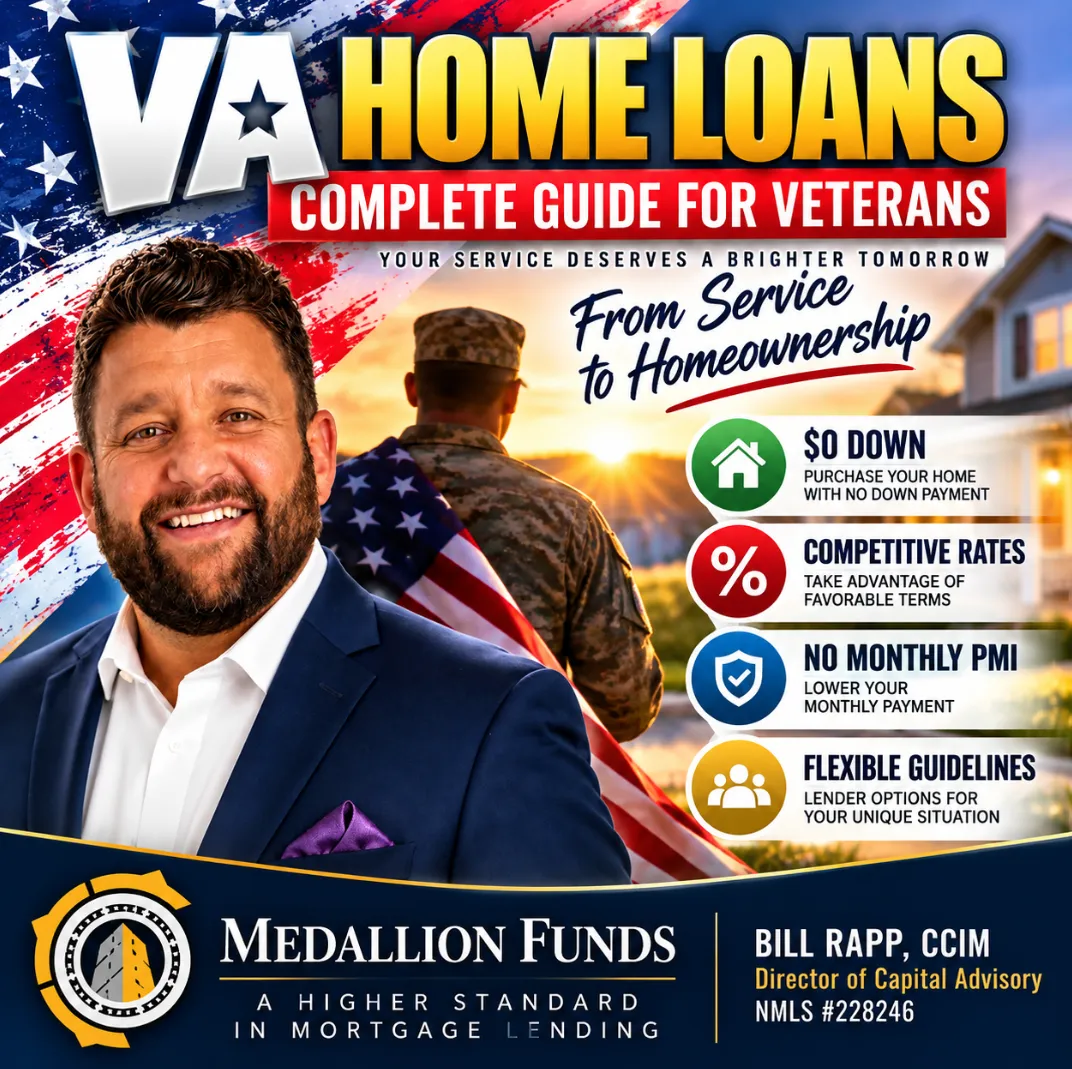
🏠 VA Loans Explained: How Veterans Can Buy a Home With No Down Payment and Save Thousands 🇺🇸
🏠 VA Loans Explained: How Veterans Can Buy a Home With No Down Payment and Save Thousands 🇺🇸
VA Home Loans: The Complete Guide to Benefits, Eligibility & Buying a Home With $0 Down 🏡
________________________________________________________________________________
VA Home Loans: The Complete Guide to Benefits, Eligibility & Buying a Home With $0 Down 🏡
For millions of veterans, active-duty military members, and eligible surviving spouses, homeownership may be more affordable than they realize.
One of the most valuable benefits earned through military service is access to the VA home loan program, which can make purchasing or refinancing a home significantly easier.
Imagine buying a home without saving tens of thousands of dollars for a down payment. For eligible borrowers, that opportunity may already exist.
But how do VA home loans work? Who qualifies? What are the closing costs? And are VA loans really better than conventional or FHA mortgages?
At Medallion Funds, we help borrowers understand their mortgage options, compare financing programs, and navigate the lending process with confidence.
This guide explains what veterans and military families should know before applying for a VA mortgage.
What Is a VA Home Loan?
A VA home loan is a mortgage made by an approved private lender and backed by a guaranty from the U.S. Department of Veterans Affairs.
The program was established to help eligible military service members, veterans, and certain surviving spouses purchase, build, improve, or refinance homes.
Unlike many traditional mortgage programs, VA loans offer substantial financial advantages, including the possibility of purchasing a home with no down payment.
The VA generally does not directly lend the money for a VA purchase mortgage. Instead, private lenders originate the loans, while the VA guaranty helps reduce the lender's risk.
This structure can provide borrowers with favorable mortgage terms.
7 Major Benefits of VA Home Loans
1. Buy a Home With No Down Payment
One of the most attractive features of VA financing is the opportunity to purchase a home with 0% down.
For qualified borrowers with full VA entitlement, no down payment is generally required when the purchase price does not exceed the appraised value and lender requirements are satisfied.
Consider the following example:
Illustrative $350,000 home purchase
VA loan — 0% down
$0
Conventional — 5% down
$17,500
This example excludes closing costs, prepaid expenses, and any VA funding fee. Actual cash-to-close depends on the transaction.
For many veterans, eliminating the down payment requirement can make the difference between purchasing a home now and waiting several additional years.
2. No Monthly Private Mortgage Insurance (PMI)
Conventional loans with less than 20% down often require private mortgage insurance.
VA loans do not require monthly PMI, even when the borrower finances 100% of the home's eligible value.
That can substantially reduce the monthly payment compared with a conventional loan that requires mortgage insurance.
However, many VA borrowers pay a one-time VA funding fee, which we will explain later.
3. Competitive Mortgage Interest Rates
VA loans frequently offer competitive interest rates compared with conventional mortgage financing.
Because the Department of Veterans Affairs guarantees a portion of the loan, lenders may be able to offer attractive terms.
Your actual interest rate depends on factors such as credit profile, loan structure, lender pricing, discount points, and market conditions.
Important: VA loans do not have one universal interest rate. Comparing multiple lenders can make a meaningful difference.
4. Flexible Credit Qualification
The VA does not establish a universal minimum credit score for its home loan guaranty program.
Individual lenders, however, may establish their own minimum credit standards.
This distinction is important.
A veteran who is declined by one lender may still qualify through another lender with different underwriting requirements.
At Medallion Funds, our role as a mortgage brokerage is to help borrowers evaluate available lending programs rather than assuming one lender's requirements represent the entire market.
5. Limits on Certain Closing Costs
VA loans include consumer protections governing certain fees that borrowers can be charged.
Some fees are prohibited, and others are subject to restrictions depending on how the lender structures its charges.
Sellers may also contribute toward allowable closing costs, subject to applicable VA requirements.
This can help eligible veterans manage the upfront cost of purchasing a home.
6. VA Loan Benefits Can Be Used More Than Once
One of the most misunderstood aspects of VA financing is the belief that veterans can use their benefits only once.
That is incorrect.
Eligible borrowers may use their VA home loan benefits multiple times.
For example, a veteran may purchase a home with VA financing, sell the property, pay off the mortgage, and potentially restore their entitlement for a future purchase.
Some borrowers may even have sufficient remaining entitlement to obtain another VA loan while retaining an existing VA-financed property.
Entitlement, occupancy, and lender requirements must be evaluated individually.
7. No Prepayment Penalty
VA loans do not permit prepayment penalties.
This means eligible borrowers can generally make additional principal payments or pay off their mortgage early without a prepayment penalty.
For homeowners planning to refinance or accelerate mortgage repayment, this provides valuable flexibility.
Who Qualifies for a VA Home Loan?
VA loan eligibility is based primarily on military service history and applicable federal requirements.
Potentially eligible borrowers include:
·Veterans who meet qualifying service requirements.
·Active-duty military personnel who meet service requirements.
·Certain National Guard and Reserve members.
·Eligible surviving spouses of deceased service members or veterans.
Eligibility depends on factors including service dates, length and character of service, and discharge status.
What Is a Certificate of Eligibility (COE)?
A Certificate of Eligibility confirms that an applicant meets the military-service eligibility requirements for the VA home loan benefit.
Borrowers can request a COE through the VA, and participating lenders can often retrieve it electronically.
A COE establishes eligibility for the benefit, but it does not guarantee mortgage approval.
Borrowers must still satisfy lender requirements involving income, credit, debts, and other underwriting factors.
How Much House Can You Buy With a VA Loan?
There is a common misconception that VA loans have a universal maximum loan amount.
For eligible borrowers with full entitlement, the VA generally does not impose a county-based loan limit on the amount that can be borrowed.
However, that does not mean a borrower can purchase a home at any price.
Lenders still evaluate the borrower's financial qualifications and the property's value.
For borrowers with partial entitlement, VA loan limits may affect the amount that can be financed without a down payment.
VA Jumbo Loans
VA financing may also be available for higher-priced properties.
For example, an eligible veteran purchasing a $750,000 home may be able to obtain VA financing without a down payment, depending on entitlement, appraisal, and lender underwriting.
The critical distinction is that VA entitlement and actual mortgage qualification are not the same thing.
Understanding the VA Funding Fee
Although VA loans do not require monthly PMI, many borrowers must pay a one-time VA funding fee.
The fee helps support the VA home loan program and varies depending on the transaction and borrower circumstances.
For VA purchase loans with less than 5% down, the standard funding fee for a non-exempt borrower is generally:
Borrower situation | VA funding fee |
First use | 2.15% |
Subsequent use | 3.30% |
Down payment of 5% to less than 10% | 1.50% |
Down payment of 10% or more | 1.25% |
These percentages apply under the current VA purchase-loan fee schedule, subject to applicable rules and exemptions.
Who Is Exempt From the VA Funding Fee?
Certain borrowers may qualify for a funding fee exemption, including veterans receiving VA compensation for service-connected disabilities and certain other eligible categories.
For qualifying veterans, this exemption can represent thousands of dollars in savings.
For example, a 2.15% funding fee on a $350,000 loan equals $7,525.
An eligible exempt borrower would avoid that fee entirely.
Funding fee exemptions should be verified through the appropriate VA eligibility documentation.
VA Loans vs. FHA Loans vs. Conventional Mortgages
Choosing the right mortgage involves more than comparing advertised interest rates.
Here is how these common financing programs generally compare.
Feature | VA | FHA | Conventional |
Minimum down payment | 0% for eligible borrowers | 3.5% for qualifying borrowers | As low as 3% for eligible borrowers |
Monthly mortgage insurance | None | Generally required | Usually required below 20% down |
Credit requirements | Lender-specific | FHA and lender standards | Program and lender standards |
Upfront program fee | VA funding fee, unless exempt | Upfront mortgage insurance premium | Generally no comparable government program fee |
Military eligibility | Required | Not required | Not required |
Repeat use | Yes | Yes | Yes |
A VA loan is often an attractive option for eligible veterans, but the best financing structure depends on individual circumstances.
For example, a veteran with substantial available cash might compare a VA mortgage against a conventional loan with 20% down.
The comparison should account for total closing costs, interest rate, mortgage insurance, the funding fee, and long-term borrowing costs.
Can You Use a VA Loan to Buy an Investment Property?
VA loans are primarily intended to finance homes that eligible borrowers will occupy as their primary residence.
They are not designed for purchasing a property solely as an investment.
However, there is an important opportunity for veterans interested in real estate investing.
VA House Hacking: Buy a Duplex, Triplex, or Fourplex
Eligible veterans may use VA financing to purchase qualifying residential properties containing up to four units, provided they satisfy the applicable owner-occupancy requirements.
For example, a veteran could purchase a duplex, occupy one unit, and rent the other.
Rental income may help offset the monthly mortgage payment, and some rental income may be considered for qualification when VA and lender requirements are met.
This strategy can provide a path toward building long-term wealth through real estate.
How Does the VA Evaluate Debt-to-Income Ratio?
Debt-to-income ratio, or DTI, compares a borrower's monthly debt obligations against qualifying monthly income.
VA underwriting also places particular importance on residual income.
Residual income measures how much money remains after accounting for major monthly obligations, including housing costs, debts, and certain other expenses.
Although 41% is an important VA DTI benchmark, it is not an absolute maximum for every borrower.
Applicants with higher DTI ratios may still qualify when the overall file satisfies VA and lender underwriting standards.
This is another reason working with a mortgage professional familiar with VA financing can be beneficial.
VA Home Loan Closing Costs: What Should Veterans Expect?
A zero-down-payment mortgage does not necessarily mean a zero-cash-to-close mortgage.
Depending on the transaction, borrowers may still be responsible for costs such as appraisal fees, title charges, prepaid homeowners insurance, initial escrow deposits, and allowable lender fees.
The actual amount varies based on the purchase price, property location, financing structure, and negotiated seller or lender credits.
Can the Seller Pay Closing Costs?
Yes. VA rules permit sellers to pay certain allowable closing costs, and they also permit seller concessions subject to specific restrictions.
The commonly referenced 4% VA seller-concession limit does not apply to every seller-paid closing cost.
Understanding this distinction can be valuable when negotiating a purchase contract.
How to Apply for a VA Home Loan: Step-by-Step
Step 1: Confirm VA eligibility
Obtain your Certificate of Eligibility and verify your available entitlement.
Step 2: Review your financial position
Evaluate credit, qualifying income, monthly debts, available assets, and desired housing payment.
Step 3: Obtain mortgage pre-approval
Have a lender review the necessary financial documentation before making an offer.
Step 4: Find a qualifying property
Work with your real estate agent to identify a home that meets your needs and applicable VA requirements.
Step 5: Complete appraisal and underwriting
The lender reviews the appraisal, property eligibility, and your complete mortgage application.
Step 6: Close on your new home
Review your final closing documents, complete funding requirements, and receive the keys.
Common VA Loan Myths
Myth 1: VA loans take longer to close.
VA loans do not inherently require longer closing timelines. Processing speed depends on the lender, borrower documentation, appraisal, and transaction complexity.
Myth 2: You can only use your VA benefit once.
Eligible veterans can potentially reuse their VA home loan benefits.
Myth 3: VA loans always require perfect credit.
The VA does not establish a universal minimum credit score, although lenders apply their own credit standards.
Myth 4: Every veteran must pay a VA funding fee.
Some eligible borrowers are exempt.
Myth 5: VA loans are only for first-time homebuyers.
VA loans are available to eligible first-time and repeat homebuyers.
Can You Refinance a VA Home Loan?
Yes. VA borrowers may have access to several refinancing strategies.
VA Interest Rate Reduction Refinance Loan (IRRRL)
Often called a VA streamline refinance, an IRRRL allows eligible borrowers with existing VA loans to refinance under applicable VA requirements.
It is generally intended to provide a qualifying financial benefit, such as reducing the interest rate or moving from an adjustable-rate mortgage to a fixed-rate mortgage.
VA Cash-Out Refinance
A VA cash-out refinance may allow eligible homeowners to refinance an existing mortgage and potentially access available equity.
This option is subject to VA eligibility, appraisal, loan-to-value, net tangible benefit, and lender requirements.
Borrowers should compare the new payment, closing costs, and long-term interest expense before refinancing.
Why Work With a Mortgage Broker for Your VA Home Loan?
Not all mortgage lenders have identical pricing, underwriting requirements, or loan programs.
Working with a mortgage brokerage can provide an opportunity to compare available options across participating lenders.
At Medallion Funds, our objective is to help eligible borrowers understand the financing alternatives available to them and select a mortgage structure that fits their goals.
Whether you are purchasing your first home, relocating after military service, buying a multi-unit residence, or considering refinancing, understanding your options is the first step.
Frequently Asked Questions About VA Home Loans
Can I get a VA loan with a 580 credit score?
Potentially. The VA does not establish a universal minimum credit score, but lender overlays and other underwriting requirements apply.
Can I purchase a $600,000 home with no down payment?
Potentially, if you have full entitlement, qualify with the lender, and meet the applicable appraisal and property requirements.
Can a surviving spouse qualify for a VA loan?
Certain surviving spouses are eligible, subject to VA requirements.
Can I use a VA loan to buy land?
VA financing may be available for eligible construction-related transactions, but purchasing vacant land alone without a qualifying construction plan generally does not fit the standard VA home loan program.
Can I use a VA loan in Texas?
Yes. VA home loans are available in Texas and throughout the United States through participating lenders.
Can I use a VA loan to buy a fourplex?
Potentially. Qualifying properties with up to four residential units may be eligible when the borrower meets owner-occupancy and underwriting requirements.
Final Thoughts: Make the Most of Your VA Home Loan Benefits
Military service can provide access to one of the most powerful mortgage benefits available to American homebuyers.
With potential zero-down financing, no monthly PMI, competitive mortgage rates, and opportunities to reuse your entitlement, VA home loans deserve serious consideration.
However, the best mortgage decision requires more than simply choosing a loan program.
It requires understanding your eligibility, monthly payment, total financing costs, and long-term financial objectives.
At Medallion Funds, we believe informed borrowers make better mortgage decisions.
Ready to Explore Your VA Home Loan Options?
Bill Rapp, CCIM
Director of Capital Advisory | Medallion Funds
Bill Rapp
Partner & Director of Capital Advisory | Medallion Funds
Commercial Lending Nationwide
Residential Lending in AL, CA, CO, NV & TXBottom of Form
https://www.billrapponline.com/
https://findamortgagebroker.com/Profile/WilliamRappJr28883
https://billrapp.commloan.com/
https://billrapponline.com/financingfuturescre-houston-katy
https://houstoncommercialmortgage.com/
https://author.billrapponline.com
https://doctorvideo.billrapponline.com/
https://veteransvideo.billrapponline.com/
https://mortgageviking.billrapponline.com/
https://fha203h.billrapponline.com/
https://renovationvideo.billrapponline.com
https://medallionfunds.com/bill-rapp/
https://www.amazon.com/dp/B0F32Z5BH2
https://veed.cello.so/FOmzTty6oi9
https://buymeacoffee.com/vikingente3
https://creplaybookseries.billrapponline.com
https://creplaybook.billrapponline.com/
© Bill Rapp, Medallion Funds LLC, Director of Capital Advisory
10 Tips for First-Time Homebuyers
Buying your first home can be both exciting and nerve-wracking at the same time. With so many things to consider and....
How To Choose the Right Lender for You
Lorem Ipsum is simply dummy text of the printing and typesetting industry. Lorem Ipsum has been the industry's standard dummy
Refinancing youe loan and when to do it
Lorem Ipsum is simply dummy text of the printing and typesetting industry. Lorem Ipsum has been the industry's standard dummy
Copyright ©2021 | Mortgage Viking Team
Licensed to Do Business | NMLS # 228246
This is not an offer to enter into an agreement. Not all customers will qualify. Information, rates and programs are subject to change without notice. All products are subject to credit and property approval. Other restrictions and limitations may apply. Copyright © 2021 | Medallion Funds
Corporate | NMLS ID NMLS # 1825831
Corporate Address : 2651 N. Green Valley Pkwy STE. 101 Henderson, NV 89014
Corporate NMLS NMLS # 1825831 | Company Website: https://medallionfunds.com/bill-rapp/
Copyright ©2021 | Mortgage Viking Team Licensed to Do Business | NMLS # 228246
This is not an offer to enter into an agreement. Not all customers will qualify. Information, rates and programs are subject to change without notice. All products are subject to credit and property approval. Other restrictions and limitations may apply
Corporate | NMLS ID NMLS # 1825831
Corporate Address : 2651 N. Green Valley Pkwy STE. 101 Henderson, NV 89014 https://medallionfunds.com/bill-rapp/
Facebook
Instagram
X
LinkedIn
Youtube
TikTok