Low Rates.
Our rates are low, our application is quick and easy! We can get you clear to close in as little as 10 days!
Trusted By Agents With
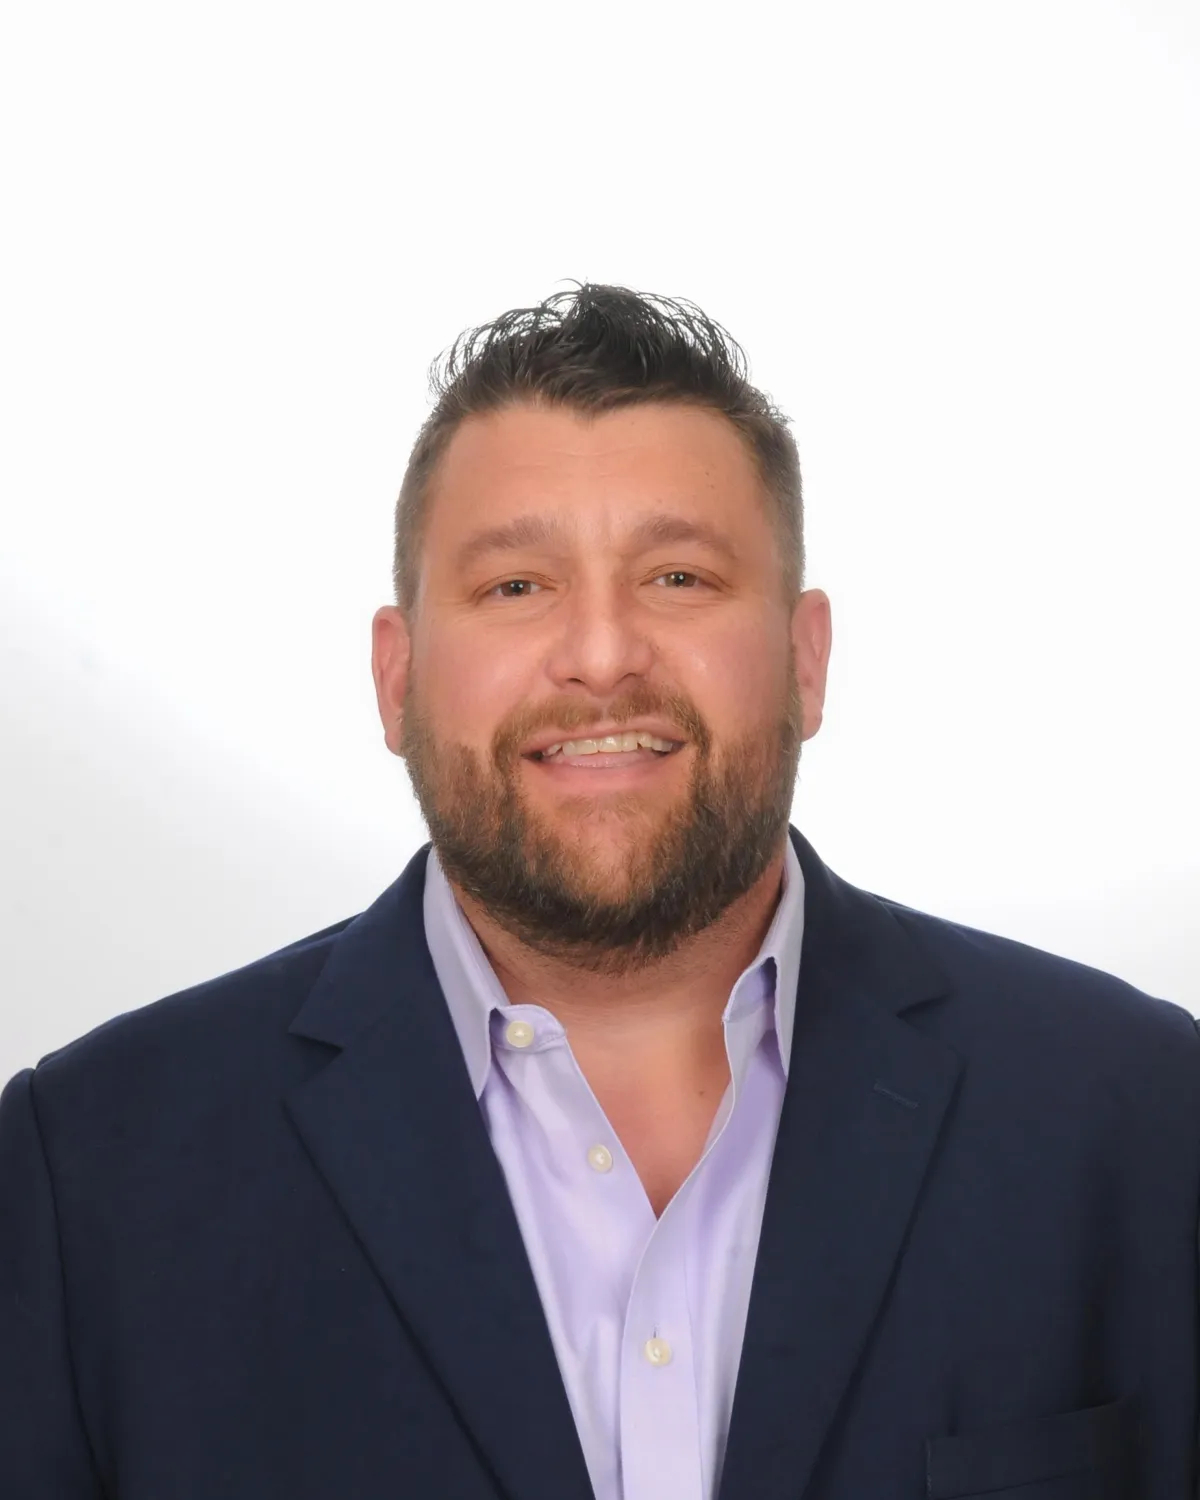
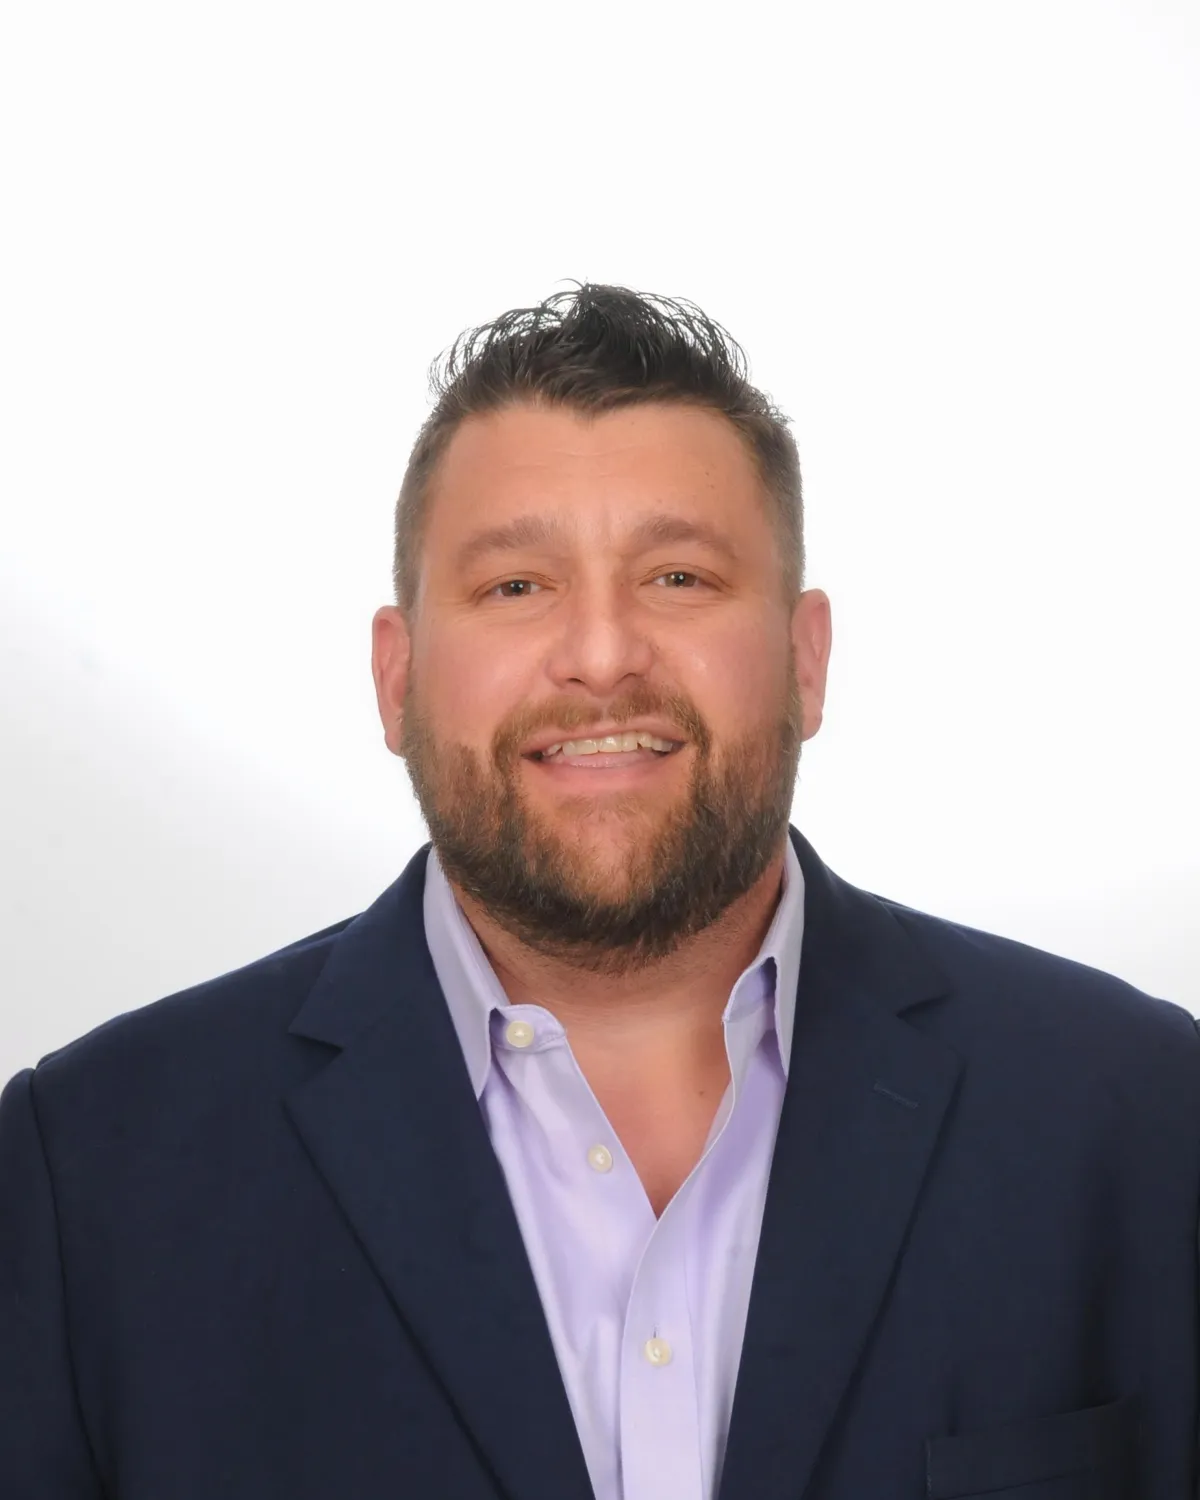
Meet Bill Rapp
NMLS ID # NMLS # 228246
Bill Rapp, CCIM is a Houston-based Capital Advisor at Medallion Funds, specializing in commercial real estate finance and strategic lending solutions. With over two decades of experience across brokerage and capital markets, Bill has worked with leading firms including eXp Commercial, NEXA Mortgage, Viking Enterprise LLC, and Sun Realty Houston.
A graduate of Texas A&M University with a BBA in Finance, Bill brings a disciplined, underwriting-first approach to every deal. His expertise spans commercial and residential financing, including asset-based lending, FHA financing, reverse mortgages, REO properties, and investment strategies for both single-family and commercial assets.
Known for his focus on structure over rate, Bill helps investors, business owners, and developers navigate complex transactions with clarity, precision, and a long-term wealth-building mindset.
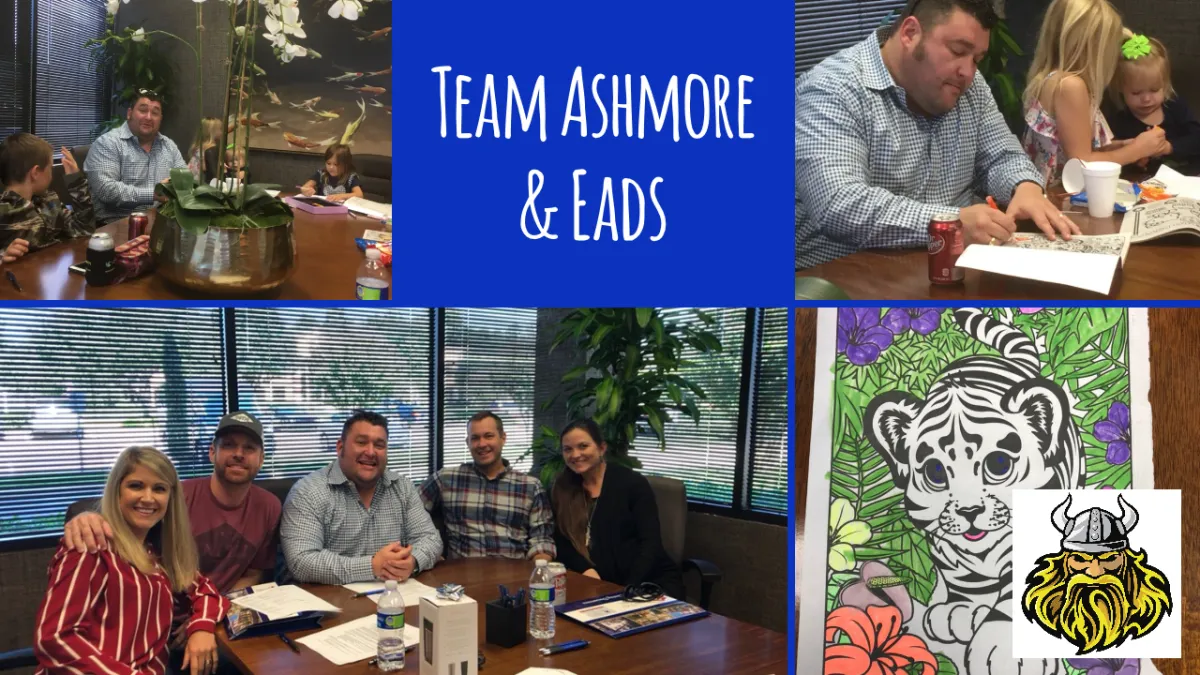
The Client Experience
Great experience purchasing our first home! Bill was easy to reach and always able to answer any questions or concerns.
Loan Programs Available


Blogs
The Top 5 Mortgage Mistakes to Avoid
Buying your first home can be both exciting and nerve-wracking at the same time. With so many things to consider and....
Mortgage Do and
Do not list
Mortgages can be tricky, and it's easy to make mistakes that can end up costing you dearly. That's why we've put together this list....
Tips On How To Improve Your Credit Score
Let's talk about some ways you can improve your credit score! Your credit score is actually a big deal, and it can affect...
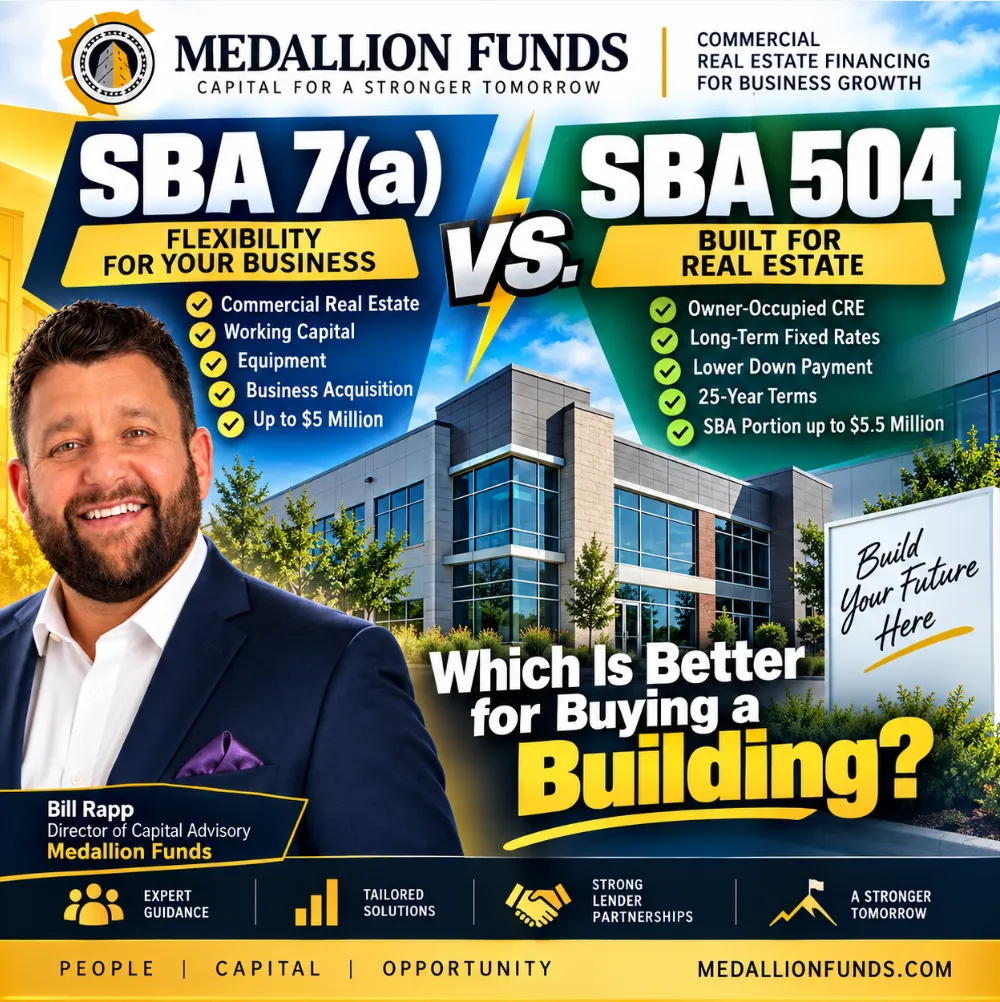
🏢 SBA 7(a) vs. SBA 504 Loans: Which Is Better for Buying Your Business Building? 💰
🏢 SBA 7(a) vs. SBA 504 Loans: Which Is Better for Buying Your Business Building? 💰
🔑 Buying Commercial Real Estate? How to Choose Between an SBA 7(a) and SBA 504 Loan 🏦
SBA 7(a) vs. SBA 504: Which Is Better for Buying a Building?
For many business owners, buying the building their company occupies can be a major step toward controlling occupancy costs, building equity, and creating a long-term real estate asset.
But once you decide to buy, another important decision follows:
Should you finance the property with an SBA 7(a) loan or an SBA 504 loan?
Both programs can finance owner-occupied commercial real estate, but they are designed differently. The better structure depends on the property, total project cost, working-capital requirements, equipment needs, and your broader business objectives.
As of September 2026, SBA 7(a) loans generally offer up to $5 million, while the SBA 504 program provides long-term fixed-asset financing with an SBA/CDC loan component of up to $5.5 million.
Understanding the difference before you make an offer on a building can help you structure the transaction around the financing rather than trying to force the financing around the deal.
What Is an SBA 7(a) Loan?
The SBA 7(a) program is the SBA's primary business loan program. It can finance the acquisition, refinancing, or improvement of commercial real estate, but its usefulness extends well beyond the building itself.
Eligible uses can include working capital, equipment, furniture and fixtures, certain debt refinancing, and complete or partial business acquisitions. A 7(a) loan can therefore be particularly useful when a transaction involves both real estate and other business needs.
For real-estate financing, SBA rules allow terms of up to 25 years, including extensions. Interest rates are negotiated with the lender but remain subject to SBA maximums.
Example: Suppose you're buying a building for your operating company, but you also need funds for renovations, equipment, furniture and working capital. A 7(a) structure may allow you to address several of those needs through a more comprehensive financing package, subject to eligibility and underwriting.
What Is an SBA 504 Loan?
The SBA 504 program is more specifically designed for major fixed assets, including owner-occupied commercial real estate and qualifying long-term equipment.
A typical 504 transaction involves three pieces: a private-sector lender providing a senior loan covering up to approximately 50% of project cost, a CDC/SBA-backed junior loan covering up to approximately 40%, and at least a 10% borrower equity contribution. Actual equity requirements can vary depending on the project and borrower circumstances.
The SBA portion offers long-term, fixed-rate financing, and 25-year maturities are available for real estate.
That combination can make the 504 program particularly attractive when the primary objective is purchasing, constructing, renovating, or expanding an owner-occupied commercial property.
However, there is an important limitation: 504 proceeds cannot be used for working capital or inventory.
SBA 7(a) vs. SBA 504 at a Glance
Feature | SBA 7(a) | SBA 504 |
Primary focus | Flexible business financing | Major fixed assets |
Real estate | Yes | Yes |
Working capital | Yes | No |
Business acquisition | Yes | Generally not the program's purpose |
Equipment | Yes | Qualifying long-term equipment |
Maximum | Generally $5M | SBA/CDC component up to $5.5M |
Real-estate term | Up to 25 years | 25-year option |
Rate structure | Negotiated, subject to SBA limits | SBA/CDC portion is fixed |
Structure | Primarily lender + SBA guaranty | Typically bank + CDC/SBA + borrower |
Best use case | Multi-purpose financing | Fixed-asset-heavy project |
SBA's current program comparison confirms these fundamental differences.
When SBA 7(a) May Make More Sense
Consider 7(a) when the building is only one part of the transaction.
For example, you might purchase a $1.5 million building but also need substantial improvements, equipment, furniture and working capital to move your company into the new location.
Rather than looking only at the real estate, the financing strategy should consider the entire capital requirement.
This flexibility is one of the principal advantages of 7(a).
When SBA 504 May Make More Sense
Now consider a business buying a larger facility where most of the project's capital is going directly into the real estate.
If preserving cash is important and the transaction qualifies for the typical 50/40/10 structure, a 504 loan deserves serious consideration.
The program was specifically designed to provide long-term financing for major fixed assets and may be particularly relevant for office buildings, medical and dental practices, warehouses, manufacturing facilities and other owner-occupied properties.
Don't Assume 10% Down Is Automatic
One of the most common mistakes is seeing an advertisement for "SBA financing with 10% down" and assuming every borrower and property will qualify for that structure.
The typical 504 framework includes at least 10% borrower equity, but actual requirements depend on the transaction.
Similarly, a 7(a) transaction needs to be underwritten based on the business, borrower, collateral, cash flow and lender requirements.
Low down payment is a potential SBA advantage—not a substitute for underwriting.
A Major SBA Change in 2026
Business owners planning larger capital projects should also know about an important recent change.
Effective July 4, 2026, SBA changed its rules so qualified borrowers can potentially access up to $5 million through 7(a) and up to $5 million through 504, for as much as $10 million in combined SBA-backed financing.
That can be especially relevant for capital-intensive businesses that need fixed-asset financing and additional capital for operating or expansion needs.
It does not mean every borrower automatically qualifies for $10 million. Eligibility, underwriting, program requirements and lender approval still apply.
So, Which SBA Loan Is Better for Buying a Building?
The question shouldn't simply be:
"Which SBA loan has the lowest rate?"
Instead, ask:
"Which capital structure best accomplishes what my business is trying to do?"
If you primarily need to acquire a major fixed asset, the 504 structure may deserve closer consideration.
If you need to combine the real estate purchase with working capital, equipment, a business acquisition or other eligible business expenses, 7(a)'s flexibility may be valuable.
And with the 2026 rule changes, some qualified borrowers may even benefit from strategically combining the programs.
Start With the Project, Not the Loan Product
Before choosing 7(a), 504 or conventional commercial financing, determine your complete sources and uses:
Purchase price, renovations, equipment, furniture and fixtures, closing costs, working capital, borrower equity, reserves and future expansion needs should all be considered.
That gives a commercial mortgage advisor the information needed to compare structures instead of simply quoting a loan.
At Medallion Funds, we help business owners evaluate commercial real estate financing based on the entire transaction and long-term objective.
Financing is subject to lender and SBA eligibility, underwriting, program requirements, credit approval and availability. Program terms can change.
Official SBA 7(a) program information
Official SBA 504 program information
Bill Rapp
Partner & Director of Capital Advisory | Medallion Funds
Commercial Lending Nationwide
Residential Lending in AL, CA, CO, NV & TXBottom of Form
https://www.billrapponline.com/
https://findamortgagebroker.com/Profile/WilliamRappJr28883
https://billrapp.commloan.com/
https://billrapponline.com/financingfuturescre-houston-katy
https://houstoncommercialmortgage.com/
https://author.billrapponline.com
https://doctorvideo.billrapponline.com/
https://veteransvideo.billrapponline.com/
https://mortgageviking.billrapponline.com/
https://fha203h.billrapponline.com/
https://renovationvideo.billrapponline.com
https://medallionfunds.com/bill-rapp/
https://www.amazon.com/dp/B0F32Z5BH2
https://veed.cello.so/FOmzTty6oi9
https://buymeacoffee.com/vikingente3
https://creplaybookseries.billrapponline.com
https://creplaybook.billrapponline.com/
© Bill Rapp, Medallion Funds LLC, Director of Capital Advisory
10 Tips for First-Time Homebuyers
Buying your first home can be both exciting and nerve-wracking at the same time. With so many things to consider and....
How To Choose the Right Lender for You
Lorem Ipsum is simply dummy text of the printing and typesetting industry. Lorem Ipsum has been the industry's standard dummy
Refinancing youe loan and when to do it
Lorem Ipsum is simply dummy text of the printing and typesetting industry. Lorem Ipsum has been the industry's standard dummy
Copyright ©2021 | Mortgage Viking Team
Licensed to Do Business | NMLS # 228246
This is not an offer to enter into an agreement. Not all customers will qualify. Information, rates and programs are subject to change without notice. All products are subject to credit and property approval. Other restrictions and limitations may apply. Copyright © 2021 | Medallion Funds
Corporate | NMLS ID NMLS # 1825831
Corporate Address : 2651 N. Green Valley Pkwy STE. 101 Henderson, NV 89014
Corporate NMLS NMLS # 1825831 | Company Website: https://medallionfunds.com/bill-rapp/
Copyright ©2021 | Mortgage Viking Team Licensed to Do Business | NMLS # 228246
This is not an offer to enter into an agreement. Not all customers will qualify. Information, rates and programs are subject to change without notice. All products are subject to credit and property approval. Other restrictions and limitations may apply
Corporate | NMLS ID NMLS # 1825831
Corporate Address : 2651 N. Green Valley Pkwy STE. 101 Henderson, NV 89014 https://medallionfunds.com/bill-rapp/
Facebook
Instagram
X
LinkedIn
Youtube
TikTok