Low Rates.
Our rates are low, our application is quick and easy! We can get you clear to close in as little as 10 days!
Trusted By Agents With
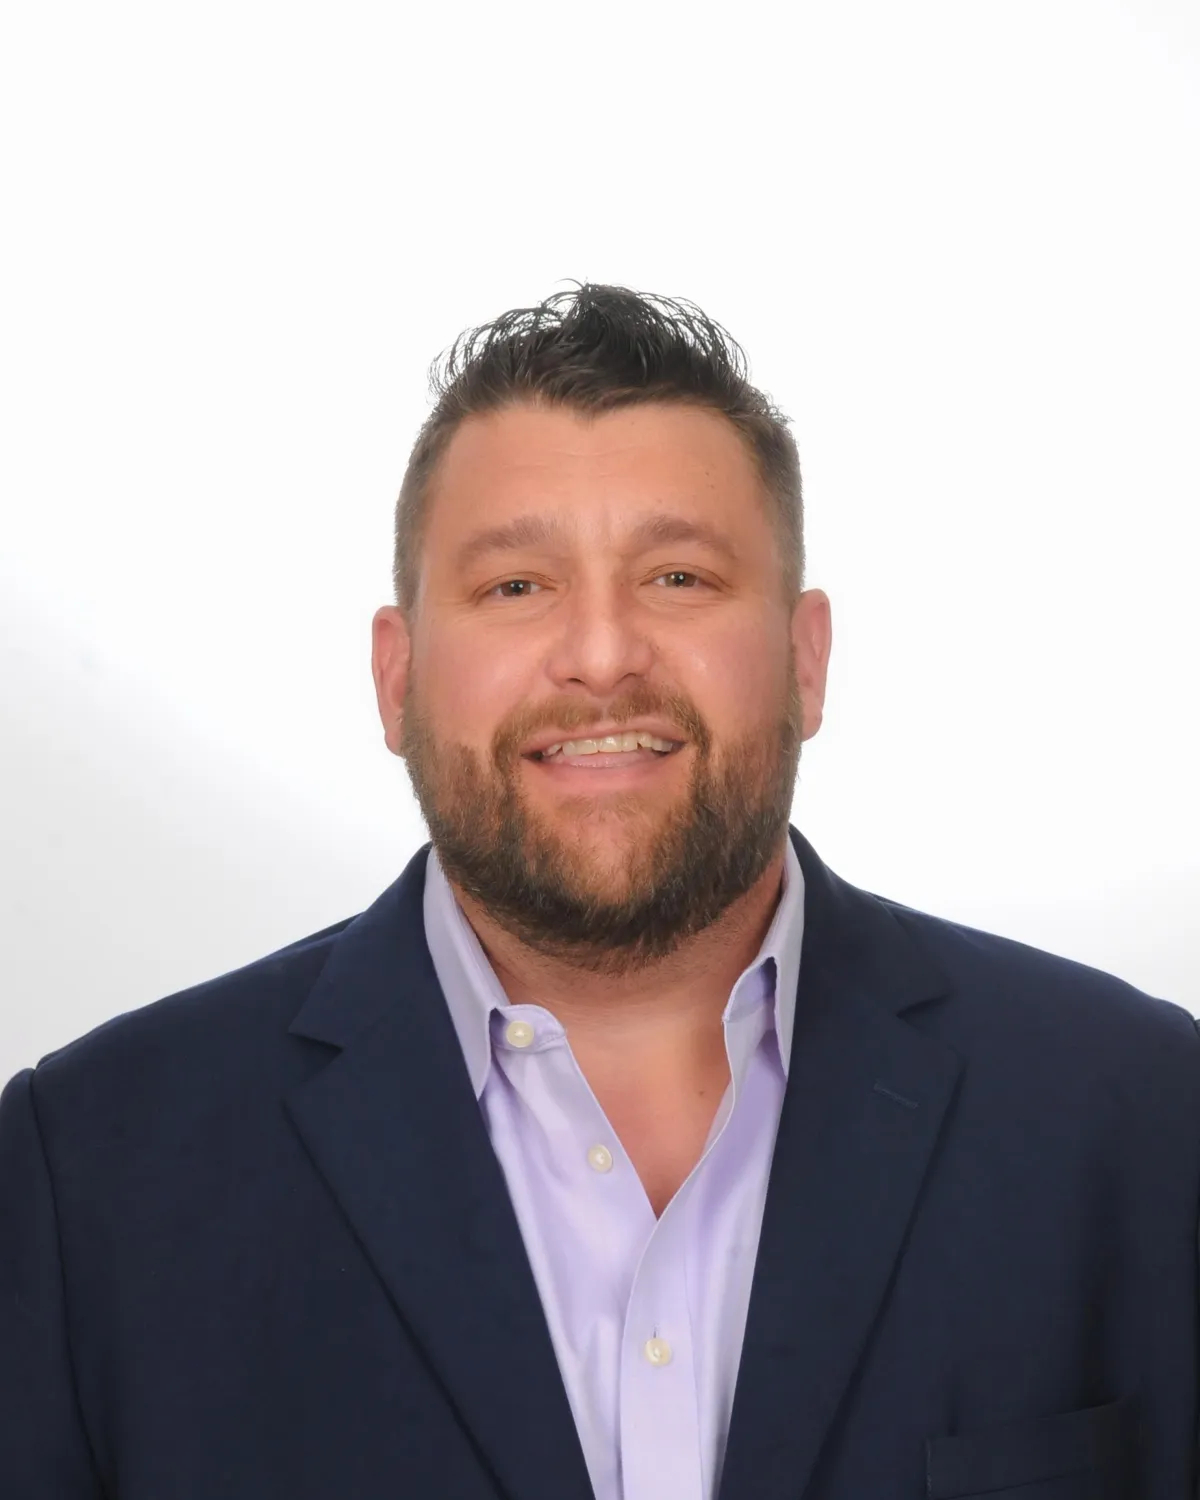
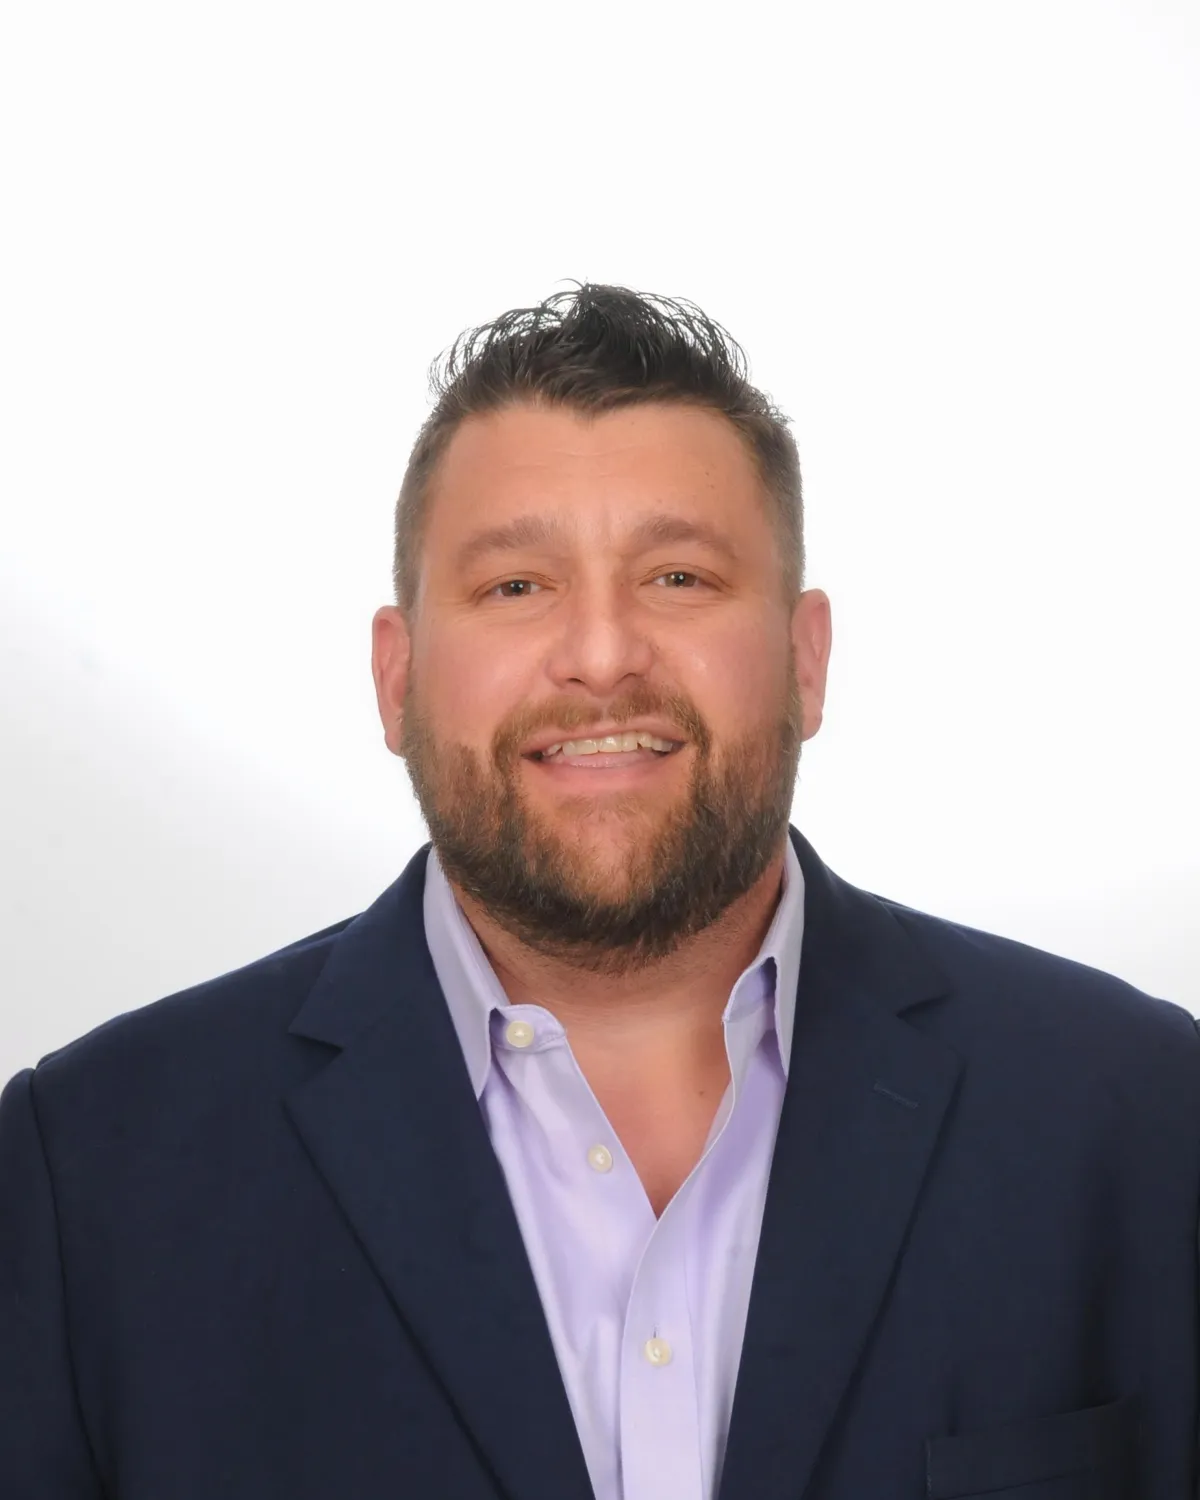
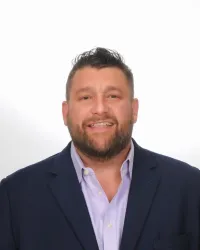
Meet Bill Rapp
NMLS ID # NMLS # 228246
Bill Rapp, CCIM is a Houston-based Capital Advisor at Medallion Funds, specializing in commercial real estate finance and strategic lending solutions. With over two decades of experience across brokerage and capital markets, Bill has worked with leading firms including eXp Commercial, NEXA Mortgage, Viking Enterprise LLC, and Sun Realty Houston.
A graduate of Texas A&M University with a BBA in Finance, Bill brings a disciplined, underwriting-first approach to every deal. His expertise spans commercial and residential financing, including asset-based lending, FHA financing, reverse mortgages, REO properties, and investment strategies for both single-family and commercial assets.
Known for his focus on structure over rate, Bill helps investors, business owners, and developers navigate complex transactions with clarity, precision, and a long-term wealth-building mindset.
The Client Experience
Great experience purchasing our first home! Bill was easy to reach and always able to answer any questions or concerns.

Loan Programs Available


Blogs
The Top 5 Mortgage Mistakes to Avoid
Buying your first home can be both exciting and nerve-wracking at the same time. With so many things to consider and....
Mortgage Do and
Do not list
Mortgages can be tricky, and it's easy to make mistakes that can end up costing you dearly. That's why we've put together this list....
Tips On How To Improve Your Credit Score
Let's talk about some ways you can improve your credit score! Your credit score is actually a big deal, and it can affect...
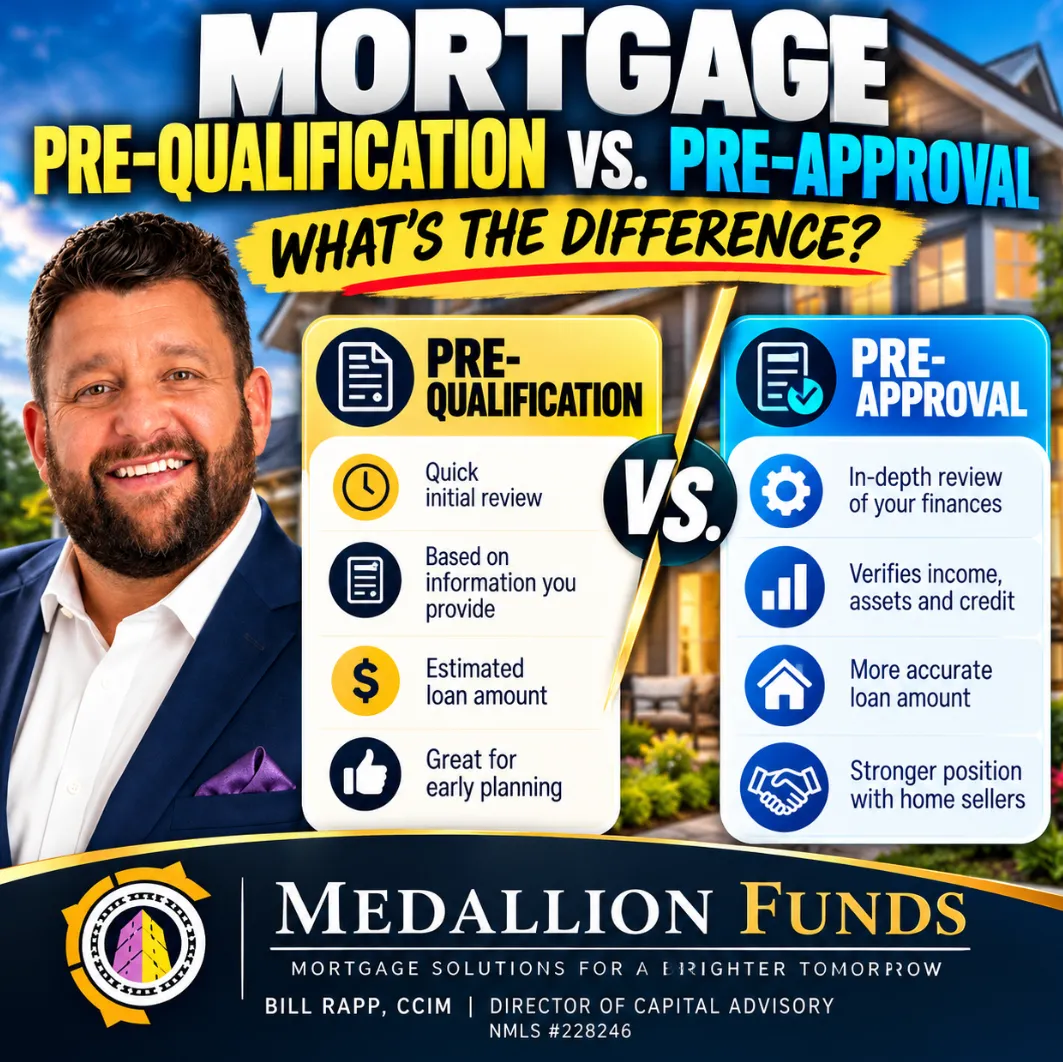
🏡 Mortgage Pre-Qualification vs. Pre-Approval: 7 Key Differences Every Homebuyer Should Know! 🔑
🏡 Mortgage Pre-Qualification vs. Pre-Approval: 7 Key Differences Every Homebuyer Should Know! 🔑
🚨 Pre-Qualified or Pre-Approved? Don't Make an Offer on a Home Until You Know the Difference! 🏠
________________________________________________________________________________
Mortgage Pre-Qualification vs. Pre-Approval: What's the Difference?
Meta Description: Learn the difference between mortgage pre-qualification and pre-approval, what lenders verify, and how to prepare to buy a home with confidence.
By Bill Rapp, CCIM | Director of Capital Advisory | Medallion Funds
Buying a home is one of the largest financial decisions most people will ever make. Before you start touring properties, however, there's an important question you need to answer:
Are you mortgage pre-qualified, or are you actually pre-approved?
These two terms are frequently used interchangeably, but they can represent very different levels of financial review.
Understanding the difference between mortgage pre-qualification and pre-approval can help you establish a realistic budget, avoid unnecessary delays, and potentially strengthen your offer when you find the right property.
At Medallion Funds, we help homebuyers evaluate mortgage options and prepare for the financing process so they can make informed decisions.
What Is Mortgage Pre-Qualification?
Mortgage pre-qualification is typically an initial assessment of how much money you may be able to borrow based on information you provide to a lender or mortgage broker.
The process often involves discussing:
·Your estimated annual income
·Your monthly debt obligations
·Your approximate credit profile
·Available savings and other assets
·Your anticipated down payment
·Your target home purchase price
Depending on the lender, pre-qualification may involve a soft credit inquiry, a more detailed credit review, or no credit check at all.
Advantages of Mortgage Pre-Qualification
1. Quick initial assessment
Pre-qualification can provide an early estimate of your borrowing capacity.
2. Helps establish a preliminary budget
Understanding your estimated purchasing power can help narrow your property search.
3. Identifies potential financing obstacles
A mortgage professional may identify issues involving income, credit, debt, or available funds before you begin making offers.
4. Useful for early financial planning
If you're considering purchasing a home several months from now, pre-qualification can help you develop a financing strategy.
Limitations of Pre-Qualification
Because pre-qualification may rely primarily on self-reported information, it does not necessarily confirm that you satisfy a lender's underwriting requirements.
Your actual mortgage eligibility could change once your financial documentation and credit history are reviewed.
Bottom line: Pre-qualification is a useful starting point, but it should not automatically be treated as a verified lending decision.
What Is Mortgage Pre-Approval?
Mortgage pre-approval generally involves a more detailed assessment of your financial qualifications.
During this process, a mortgage lender or broker typically reviews supporting information such as:
·Credit history and credit scores
·Employment and income documentation
·Bank statements and available assets
·Existing debts and financial obligations
·Down payment and closing cost funds
·Applicable mortgage program requirements
Some lenders also provide pre-approvals involving automated underwriting or an initial underwriter review.
However, the depth of verification varies by lender.
A pre-approval letter usually indicates that, based on the information reviewed, you appear eligible for financing up to a specified amount, subject to applicable conditions.
Why Mortgage Pre-Approval Matters
1. Greater confidence in your purchasing budget
A more comprehensive financial review can help identify the mortgage amount and loan structure that may fit your circumstances.
2. Stronger positioning with home sellers
A seller may view an offer accompanied by a credible pre-approval letter more favorably than an offer without evidence of financing preparation.
3. Earlier identification of underwriting issues
Income documentation, credit concerns, and asset requirements can sometimes be addressed before you're under contract.
4. Potentially smoother mortgage processing
Completing important verification steps early may reduce delays later, although it does not guarantee a faster closing.
5. Better loan program evaluation
Pre-approval provides an opportunity to assess conventional, FHA, VA, jumbo, and other applicable mortgage options.
Mortgage Pre-Qualification vs. Pre-Approval: Side-by-Side Comparison
Feature | Pre-Qualification | Pre-Approval |
Purpose | Preliminary borrowing estimate | More detailed financing assessment |
Income review | Often self-reported | Typically documented or verified |
Credit review | Varies by lender | Usually includes credit review |
Asset verification | Often limited | Typically more extensive |
Processing time | Often relatively quick | Depends on lender and documentation |
Seller confidence | Generally lower | Generally stronger |
Loan commitment | No | No |
Best use | Early planning | Preparing to make an offer |
Important: Neither pre-qualification nor pre-approval guarantees final mortgage approval.
7 Key Differences Every Homebuyer Should Understand
1. The Level of Financial Verification
Pre-qualification commonly begins with estimates. Pre-approval typically involves a more detailed review of your actual financial documentation.
2. Credit Review Requirements
Some pre-qualification processes use soft credit inquiries, while pre-approval commonly requires a hard credit inquiry.
A hard inquiry may have a temporary effect on your credit score. Ask your mortgage professional what type of inquiry will be performed.
3. Accuracy of Your Estimated Loan Amount
A pre-qualification estimate may change significantly when a lender verifies your income, debts, assets, and credit history.
Pre-approval generally provides a better-supported estimate, although it remains conditional.
4. Strength of Your Purchase Offer
In a competitive housing market, sellers may prefer buyers who have already completed a more substantial financing review.
A pre-approval letter can help demonstrate that you're taking the purchase seriously.
5. Mortgage Program Selection
Pre-qualification may identify potential financing options.
Pre-approval can provide a more detailed assessment of whether you appear to meet specific loan program requirements.
6. Potential Closing Delays
A more thorough review before making an offer may identify issues that otherwise would not surface until after the purchase contract is signed.
7. Readiness to Purchase
Pre-qualification is often appropriate when you're exploring the market.
Pre-approval is generally the better choice when you're preparing to make an offer.
How Much House Can You Afford?
One of the biggest mistakes homebuyers make is confusing the maximum mortgage amount they might qualify for with the amount they should comfortably spend.
Consider this hypothetical example:
A borrower receives a pre-approval indicating potential eligibility for a $450,000 home purchase.
However, after reviewing projected property taxes, homeowners insurance, mortgage insurance, and other expenses, the borrower determines that a $375,000 home better supports their financial goals.
The right purchase price isn't necessarily the highest amount a lender will approve.
At Medallion Funds, our objective is to help borrowers evaluate financing options within the context of their broader financial circumstances.
What Documents Do You Need for Mortgage Pre-Approval?
Although requirements vary by lender and loan program, many borrowers should be prepared to provide:
·Recent pay stubs
·W-2 forms from the previous two years
·Federal tax returns, when required
·Recent bank statements
·Documentation of additional income
·Information about existing mortgage obligations
·Identification and employment details
·Documentation of gift funds, when applicable
What About Self-Employed Borrowers?
Self-employed borrowers may need additional documentation, including business tax returns, profit-and-loss statements, or business bank statements.
Certain alternative-documentation mortgage programs may be available for qualified borrowers who do not fit traditional income-verification requirements.
A mortgage broker can help assess which options may be appropriate.
Does Mortgage Pre-Approval Guarantee Final Approval?
No.
Even after receiving a mortgage pre-approval letter, several items may still need to be completed.
These can include:
·Property appraisal
·Title review
·Property insurance verification
·Final income and employment verification
·Updated asset documentation
·Final underwriting approval
·Satisfaction of lender conditions
Significant financial changes between pre-approval and closing can affect eligibility.
For example, opening new credit accounts, financing a vehicle, changing employment, or taking on additional debt could create complications.
Avoid major financial changes during the mortgage process without first consulting your mortgage professional.
How Long Does Mortgage Pre-Approval Last?
Many mortgage pre-approval letters are issued with validity periods of approximately 30 to 90 days.
However, the exact period depends on the lender, loan program, credit report requirements, and supporting documentation.
If your home search extends beyond the expiration date, updated documentation or a new credit review may be required.
Should You Get Pre-Qualified or Pre-Approved First?
The best approach depends on your timeline.
If you're six months away from buying:
A preliminary pre-qualification may help you evaluate affordability, identify potential issues, and create a financial preparation plan.
If you're planning to purchase within the next 30 to 90 days:
A more comprehensive pre-approval is generally preferable.
If you're actively making offers:
You should strongly consider obtaining a current pre-approval letter before submitting an offer.
Why Work With a Mortgage Broker Instead of Going Directly to One Bank?
A traditional bank generally evaluates mortgage applications using the loan products and lending guidelines available through that institution.
A mortgage broker can help borrowers explore financing options from multiple wholesale lending sources.
This may be especially useful for borrowers with:
·Nontraditional income
·Self-employment earnings
·Significant student loan debt
·Jumbo mortgage requirements
·Investment property financing needs
·Unique credit or asset circumstances
At Medallion Funds, we focus on understanding the borrower's complete financial picture before evaluating available mortgage structures.
The objective isn't simply to obtain a pre-approval letter. It's to identify financing that aligns with your purchase and financial goals.
Frequently Asked Questions
Can I get pre-approved without finding a house?
Yes. Many borrowers obtain mortgage pre-approval before identifying a specific property. Final approval will still depend on the property and other outstanding conditions.
Does mortgage pre-qualification hurt my credit score?
Not necessarily. Some lenders use a soft inquiry or do not check credit during preliminary pre-qualification. Ask about the inquiry type before proceeding.
Can I get pre-approved with a low credit score?
Possibly. Eligibility depends on the loan program, credit history, income, debts, available assets, and other underwriting factors.
Can I obtain pre-approval from more than one lender?
Yes. Comparing mortgage options can help borrowers evaluate rates, fees, programs, and service levels. Credit scoring models may treat multiple mortgage-shopping inquiries within an applicable window as a single inquiry, although the rules vary by model.
Is a pre-approval letter a guarantee that my loan will close?
No. Final mortgage approval remains subject to underwriting, property review, and satisfaction of lender conditions.
How early should I get mortgage pre-approved?
For borrowers actively preparing to purchase, beginning the pre-approval process before touring homes or making offers is often beneficial.
Final Thoughts: Preparation Creates Better Homebuying Decisions
Understanding the difference between mortgage pre-qualification and pre-approval can help you avoid confusion and prepare for the homebuying process.
Pre-qualification is a valuable initial planning tool.
Pre-approval typically provides a more substantial assessment of your financing eligibility and can help position you as a better-prepared buyer.
Before you fall in love with a home, make sure you understand your financing options.
Ready to Discuss Your Mortgage Options?
I'm Bill Rapp, CCIM, Director of Capital Advisory with Medallion Funds.
Whether you're purchasing your first home, upgrading to a larger property, or evaluating alternative mortgage programs, we can help you explore available financing solutions.
Website: https://billrapponline.com/
YouTube: https://www.youtube.com/@billrapp-medallion-funds
NMLS #228246
Bill Rapp
Partner & Director of Capital Advisory | Medallion Funds
Commercial Lending Nationwide
Residential Lending in AL, CA, CO, NV & TXBottom of Form
https://www.billrapponline.com/
https://findamortgagebroker.com/Profile/WilliamRappJr28883
https://billrapp.commloan.com/
https://billrapponline.com/financingfuturescre-houston-katy
https://houstoncommercialmortgage.com/
https://author.billrapponline.com
https://doctorvideo.billrapponline.com/
https://veteransvideo.billrapponline.com/
https://mortgageviking.billrapponline.com/
https://fha203h.billrapponline.com/
https://renovationvideo.billrapponline.com
https://medallionfunds.com/bill-rapp/
https://www.amazon.com/dp/B0F32Z5BH2
https://veed.cello.so/FOmzTty6oi9
https://buymeacoffee.com/vikingente3
https://creplaybookseries.billrapponline.com
https://creplaybook.billrapponline.com/
© Bill Rapp, Medallion Funds LLC, Director of Capital Advisory
10 Tips for First-Time Homebuyers
Buying your first home can be both exciting and nerve-wracking at the same time. With so many things to consider and....
How To Choose the Right Lender for You
Lorem Ipsum is simply dummy text of the printing and typesetting industry. Lorem Ipsum has been the industry's standard dummy
Refinancing youe loan and when to do it
Lorem Ipsum is simply dummy text of the printing and typesetting industry. Lorem Ipsum has been the industry's standard dummy
Copyright ©2021 | Mortgage Viking Team
Licensed to Do Business | NMLS # 228246
This is not an offer to enter into an agreement. Not all customers will qualify. Information, rates and programs are subject to change without notice. All products are subject to credit and property approval. Other restrictions and limitations may apply. Copyright © 2021 | Medallion Funds
Corporate | NMLS ID NMLS # 1825831
Corporate Address : 2651 N. Green Valley Pkwy STE. 101 Henderson, NV 89014
Corporate NMLS NMLS # 1825831 | Company Website: https://medallionfunds.com/bill-rapp/
Copyright ©2021 | Mortgage Viking Team Licensed to Do Business | NMLS # 228246
This is not an offer to enter into an agreement. Not all customers will qualify. Information, rates and programs are subject to change without notice. All products are subject to credit and property approval. Other restrictions and limitations may apply
Corporate | NMLS ID NMLS # 1825831
Corporate Address : 2651 N. Green Valley Pkwy STE. 101 Henderson, NV 89014 https://medallionfunds.com/bill-rapp/
Facebook
Instagram
X
LinkedIn
Youtube
TikTok