Low Rates.
Our rates are low, our application is quick and easy! We can get you clear to close in as little as 10 days!
Trusted By Agents With
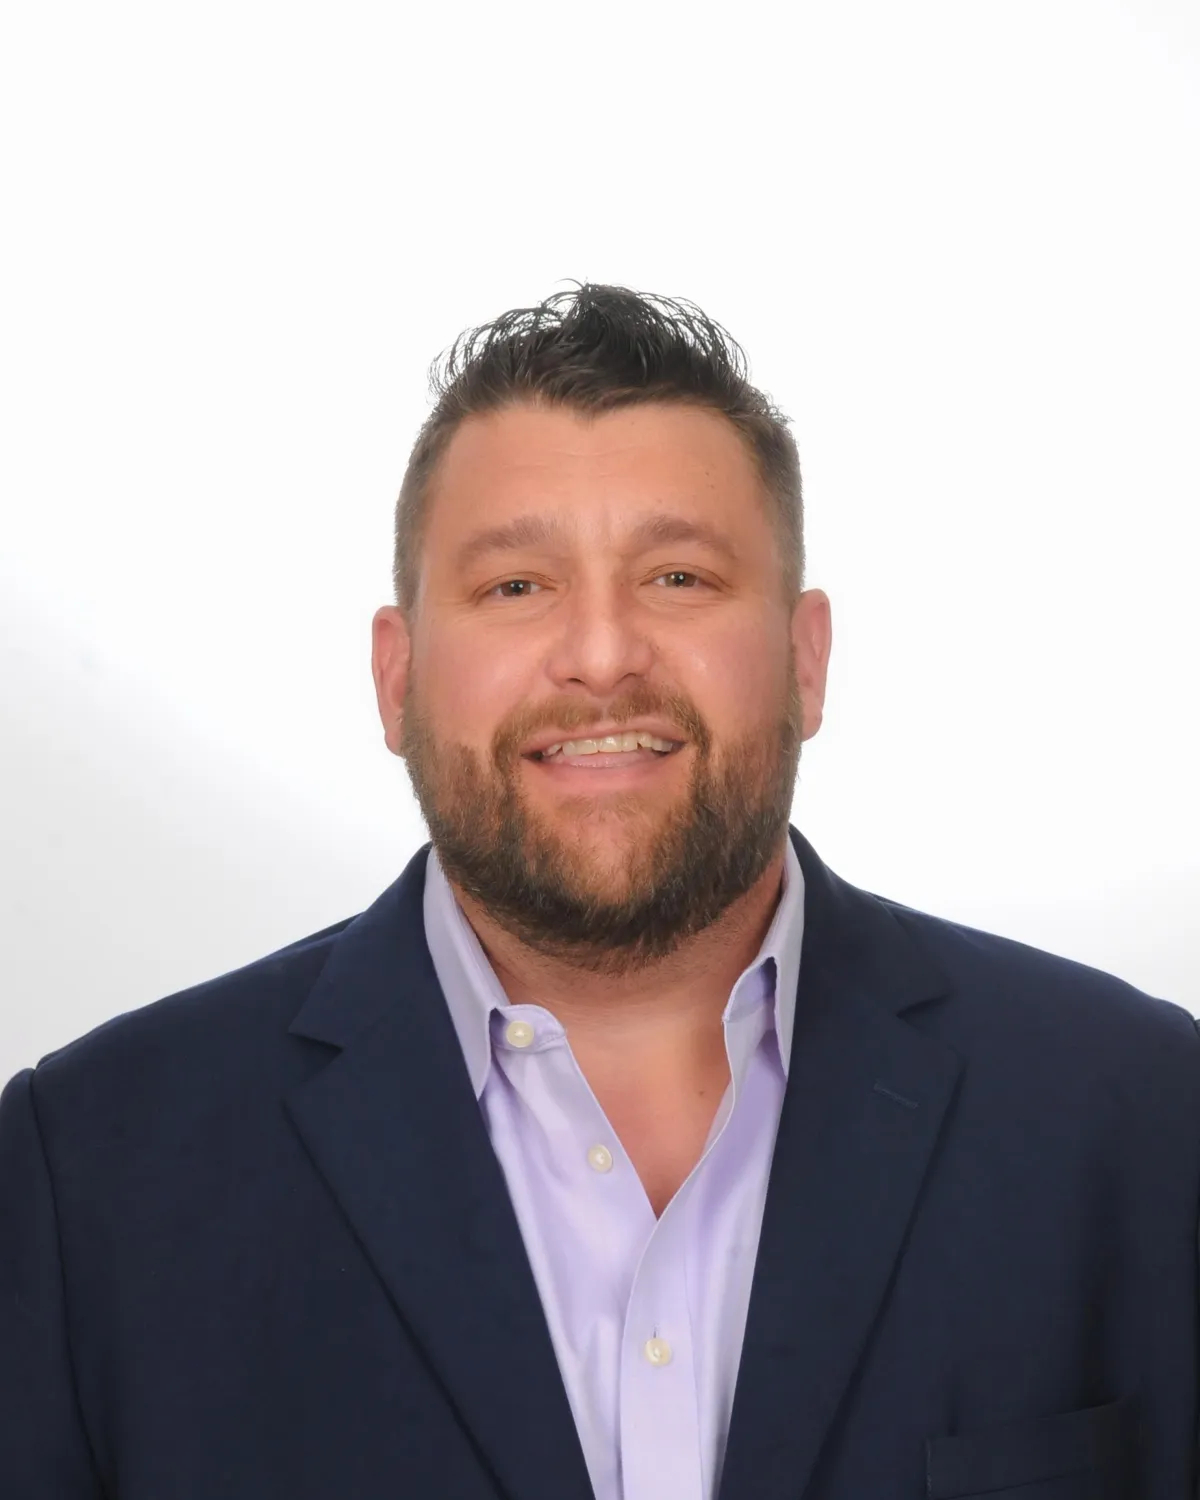
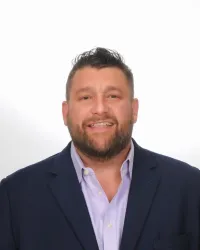
Meet Bill Rapp
NMLS ID # NMLS # 228246
Bill Rapp, CCIM is a Houston-based Capital Advisor at Medallion Funds, specializing in commercial real estate finance and strategic lending solutions. With over two decades of experience across brokerage and capital markets, Bill has worked with leading firms including eXp Commercial, NEXA Mortgage, Viking Enterprise LLC, and Sun Realty Houston.
A graduate of Texas A&M University with a BBA in Finance, Bill brings a disciplined, underwriting-first approach to every deal. His expertise spans commercial and residential financing, including asset-based lending, FHA financing, reverse mortgages, REO properties, and investment strategies for both single-family and commercial assets.
Known for his focus on structure over rate, Bill helps investors, business owners, and developers navigate complex transactions with clarity, precision, and a long-term wealth-building mindset.
The Client Experience
Great experience purchasing our first home! Bill was easy to reach and always able to answer any questions or concerns.

Loan Programs Available


Blogs
The Top 5 Mortgage Mistakes to Avoid
Buying your first home can be both exciting and nerve-wracking at the same time. With so many things to consider and....
Mortgage Do and
Do not list
Mortgages can be tricky, and it's easy to make mistakes that can end up costing you dearly. That's why we've put together this list....
Tips On How To Improve Your Credit Score
Let's talk about some ways you can improve your credit score! Your credit score is actually a big deal, and it can affect...
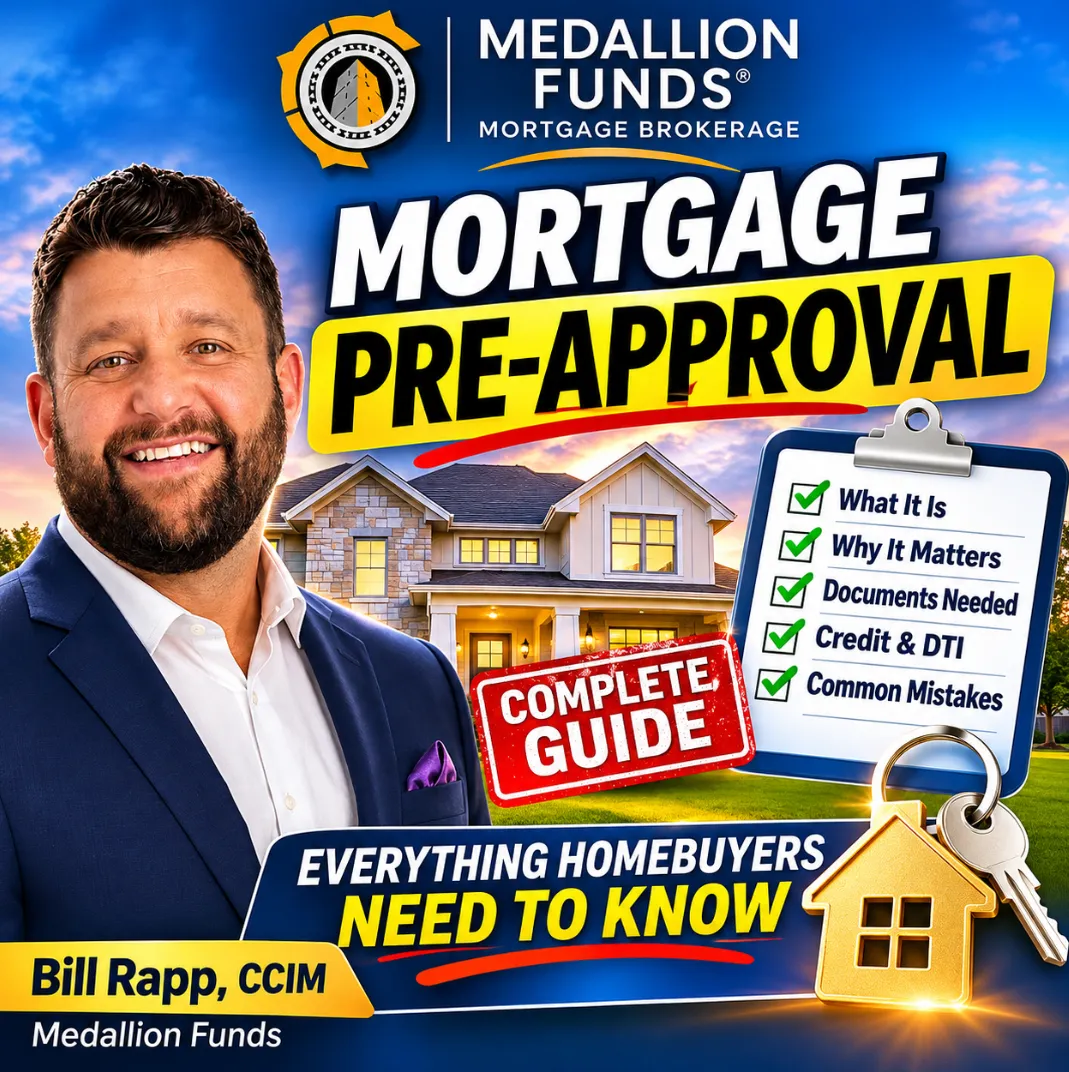
🏡 Mortgage Pre-Approval: Your Complete Guide 🔑
🏡 Mortgage Pre-Approval: Your Complete Guide 🔑
Get Mortgage Pre-Approved Before Buying a Home! 🏠
_______________________________________________________________________
🏡 Mortgage Pre-Approval: Everything Homebuyers Need to Know
Before you start shopping for your dream home, there's one important step that could save you time, money, and frustration: getting mortgage pre-approved.
Whether you're a first-time homebuyer, relocating to Texas, purchasing a larger home, or buying an investment property, understanding the mortgage pre-approval process can help you make smarter financial decisions.
A mortgage pre-approval gives you an early assessment of how much financing you may qualify for, what loan programs may be available, and what potential obstacles you should address before making an offer.
I'm Bill Rapp, CCIM, with Medallion Funds, and in this guide, I'll explain how mortgage pre-approval works, what lenders look for, which documents you'll need, and how to position yourself for a smoother home purchase.
What Is Mortgage Pre-Approval?
Mortgage pre-approval is a lender's preliminary assessment of your ability to qualify for a home loan.
During the pre-approval process, a lender or mortgage broker evaluates your financial information, which may include:
·Credit history and credit scores
·Employment and income
·Monthly debt obligations
·Bank accounts and available assets
·Down payment funds
·Proposed loan amount and mortgage program
Depending on the lender, pre-approval may involve verifying financial documents and reviewing automated underwriting findings.
Once the initial review is completed, you may receive a mortgage pre-approval letter outlining a proposed financing amount and applicable conditions.
Important: A mortgage pre-approval is not a guaranteed mortgage commitment. Final approval generally depends on underwriting, updated documentation, acceptable property conditions, appraisal requirements, title review, and other lender conditions.
Mortgage Pre-Approval vs. Pre-Qualification: What's the Difference?
Although the terms are sometimes used interchangeably, pre-qualification and pre-approval can involve different levels of financial review.
Mortgage pre-qualification is generally an early estimate based on information you provide. It may involve limited documentation or verification.
Mortgage pre-approval typically involves a more detailed assessment of your income, assets, debts, and credit.
For example, a buyer might receive a preliminary estimate that they could afford a $400,000 home.
After reviewing verified income, outstanding debts, and available funds, the lender may determine that a lower or higher purchase price is more appropriate.
The actual level of verification varies by lender, so ask what your pre-approval includes.
My recommendation: Whenever possible, obtain a documented mortgage pre-approval before making an offer on a home.
Why Mortgage Pre-Approval Matters Before House Hunting
1. Understand Your Buying Power
Mortgage pre-approval helps you estimate how much you may be able to borrow.
However, your maximum qualifying loan amount isn't necessarily your ideal borrowing amount.
Your actual housing budget should account for:
·Principal and interest
·Property taxes
·Homeowners insurance
·Mortgage insurance, when applicable
·HOA dues
·Maintenance and repairs
This is especially important for buyers in Katy, Fulshear, Houston, and other Texas communities where property taxes and insurance can materially affect monthly housing costs.
2. Strengthen Your Purchase Offer
A seller wants confidence that a buyer can complete the transaction.
A well-supported pre-approval letter may make your offer more credible because it demonstrates that you've already begun the mortgage qualification process.
In competitive housing markets, this preparation can help you move quickly when the right property becomes available.
3. Identify Financing Problems Early
Your lender may discover issues involving:
·Credit report inaccuracies
·High debt-to-income ratios
·Inconsistent income documentation
·Insufficient verified funds
·Recent employment changes
·Large unexplained bank deposits
Addressing these issues before entering a purchase contract may help prevent avoidable delays.
4. Compare Mortgage Programs
Getting pre-approved also creates an opportunity to explore financing options.
At Medallion Funds, we help eligible borrowers evaluate conventional, FHA, VA, jumbo, doctor loan, and other mortgage solutions.
Program eligibility, pricing, and requirements vary.
What Documents Do You Need for Mortgage Pre-Approval?
Preparing your documentation before applying can make the process more efficient.
For W-2 employees:
·Recent pay stubs
·W-2 forms, commonly covering the previous two years
·Recent bank statements
·Government-issued identification
·Employment history
·Tax returns when required
For self-employed borrowers:
·Personal and business tax returns, when required
·Business financial statements
·Bank statements
·Business ownership documentation
·Additional income verification requested by underwriting
Some borrowers may qualify for alternative-documentation mortgage programs, including certain bank statement loans.
These programs have their own eligibility standards, pricing, and documentation requirements.
For veterans and active-duty military borrowers:
VA mortgage applicants may also need a Certificate of Eligibility, which establishes whether they meet applicable military service eligibility requirements.
Your mortgage professional can help identify which documents apply to your specific situation.
What Credit Score Do You Need for Mortgage Pre-Approval?
There is no single minimum credit score that applies to every mortgage program.
Credit requirements vary by loan type, lender, and overall borrower profile.
For example:
Conventional loans: Many lenders use a 620 benchmark, although some automated underwriting paths and lenders may have different requirements.
FHA loans: FHA policy generally permits qualifying borrowers with credit scores of at least 580 to access maximum financing, subject to lender standards. Certain borrowers with scores between 500 and 579 may be eligible with at least 10% down, although many lenders impose higher minimums.
VA loans: The VA does not establish a universal minimum credit score, but individual lenders may apply their own requirements.
Jumbo loans: Credit requirements are often more restrictive, although they vary considerably.
A stronger credit profile may improve your financing options and potentially reduce borrowing costs.
Before applying, avoid opening unnecessary new credit accounts or taking on substantial additional debt.
How Does Debt-to-Income Ratio Affect Pre-Approval?
Your debt-to-income ratio (DTI) compares your monthly debt payments with your gross monthly income.
The formula is:
DTI = Total Monthly Debt Payments ÷ Gross Monthly Income × 100
For example:
·Gross monthly income: $10,000
·Existing monthly debt payments: $1,000
·Proposed monthly housing payment: $2,500
·Total monthly obligations: $3,500
Your estimated DTI would be:
$3,500 ÷ $10,000 = 35%
A 35% DTI may be acceptable for many mortgage programs, depending on other underwriting factors.
However, lenders consider more than just your DTI. Credit history, assets, reserves, loan-to-value ratio, and program guidelines also matter.
How Long Does Mortgage Pre-Approval Take?
Some straightforward mortgage pre-approvals can be completed the same day or within one to three business days after the lender receives the necessary information.
More complicated applications may take longer.
Common reasons for additional review include:
·Self-employment income
·Multiple properties
·Variable compensation
·Recent job changes
·Complex asset documentation
·Credit issues
Submitting complete, accurate documentation early can help streamline the process.
How Long Does a Mortgage Pre-Approval Last?
Many mortgage pre-approval letters are valid for approximately 60 to 90 days, although lender policies differ.
Credit reports and supporting financial documents also have their own age requirements.
If your pre-approval expires, your mortgage professional may request updated documents or credit information.
You should also request a new review if your financial circumstances change significantly.
Does Mortgage Pre-Approval Hurt Your Credit?
A mortgage pre-approval may involve a hard credit inquiry, which can temporarily affect your credit score.
However, credit scoring models generally provide a shopping window during which multiple mortgage inquiries may be treated as one inquiry for scoring purposes.
The applicable window varies by scoring model, commonly ranging from 14 to 45 days.
Shopping for mortgage financing within a concentrated period can help limit the scoring impact.
How Much Should You Get Pre-Approved For?
Suppose a lender determines that you may qualify for a $500,000 purchase price.
That doesn't mean you should automatically shop at $500,000.
You may prefer a $425,000 home because it leaves additional room for:
·Emergency savings
·Retirement contributions
·Childcare and education
·Home improvements
·Travel and lifestyle expenses
The best mortgage isn't always the largest mortgage you qualify for. It's the mortgage that fits your financial goals.
Real-World Example: Buying a Home in Katy, Texas
Imagine a couple purchasing a $400,000 home in Katy.
They plan to use a conventional mortgage with 5% down.
Their preliminary financing structure might look like this:
Item | Amount |
Purchase price | $400,000 |
Down payment (5%) | $20,000 |
Estimated loan amount | $380,000 |
Illustrative interest rate | 6.50% |
Loan term | 30 years |
Principal and interest | Approximately $2,402/month |
The 6.50% interest rate is hypothetical and is not a current rate quote.
The monthly principal and interest payment does not include property taxes, homeowners insurance, mortgage insurance, or HOA dues.
The lender must consider those additional housing expenses when evaluating affordability and qualification.
By getting pre-approved first, these buyers can better understand their estimated payment, required funds, and potential financing limitations before submitting an offer.
Common Mortgage Pre-Approval Mistakes to Avoid
Mistake #1: Waiting until you find a house.
Starting the financing process early gives you more time to address problems.
Mistake #2: Making large purchases before closing.
Financing a vehicle, furniture, or appliances may increase your DTI and affect qualification.
Mistake #3: Changing jobs without discussing it with your lender.
Employment changes can require additional income verification.
Mistake #4: Moving money between accounts without documentation.
Large transfers and deposits may create additional underwriting questions.
Mistake #5: Confusing pre-approval with final approval.
A pre-approval does not eliminate property-specific underwriting requirements.
Mistake #6: Focusing only on the interest rate.
Closing costs, mortgage insurance, lender fees, discount points, and loan structure all affect your total financing costs.
Why Work With a Mortgage Broker for Pre-Approval?
A mortgage broker can help you evaluate loan programs from different wholesale lenders rather than relying exclusively on one institution's offerings.
At Medallion Funds, we focus on matching borrowers with financing solutions suited to their financial circumstances and long-term goals.
We work with a variety of borrower profiles, including:
·First-time homebuyers
·Veterans and military families
·Doctors and dentists
·Self-employed professionals
·Real estate investors
·Buyers seeking jumbo financing
·Borrowers exploring construction or renovation loans
Not every lender offers every program, and not every borrower qualifies for every option.
The value of working with a knowledgeable mortgage professional is understanding your alternatives before committing to a financing strategy.
Frequently Asked Questions About Mortgage Pre-Approval
Can I get pre-approved before finding a home?
Yes. In fact, getting pre-approved before shopping is generally advisable.
Do I need a down payment to get pre-approved?
Not necessarily. Eligible borrowers may qualify for VA or USDA loans with no required down payment. Other programs may offer low-down-payment options. Closing costs and other cash requirements may still apply.
Can self-employed borrowers get pre-approved?
Yes. Self-employed borrowers may qualify using traditional income documentation or certain alternative-documentation programs, depending on eligibility.
Can I get pre-approved with student loans?
Yes. Student loans are generally considered when calculating qualifying debt obligations, but the treatment of payments varies by program.
Can I get pre-approved by more than one lender?
Yes. Comparing multiple mortgage options can help you evaluate rates, fees, and loan terms.
Is pre-approval a guarantee that my mortgage will close?
No. Final approval depends on satisfying all applicable lender and property requirements.
Ready to Get Mortgage Pre-Approved?
Buying a home is a major financial decision, and preparation matters.
Before touring homes, take time to understand your credit, income, debt obligations, available funds, and mortgage options.
A properly structured mortgage pre-approval can help you shop confidently, make more informed offers, and avoid unnecessary surprises.
I'm Bill Rapp, CCIM, with Medallion Funds. If you're considering purchasing a home, let's evaluate your financing options before you start shopping.
Bill Rapp
Partner & Director of Capital Advisory | Medallion Funds
Commercial Lending Nationwide
Residential Lending in AL, CA, CO, NV & TXBottom of Form
📞 Call or Text: 281-222-0433
🌐 Website: https://billrapponline.com
🎥 Subscribe to Mortgage Viking: https://www.youtube.com/@billrapp-medallion-funds
https://www.billrapponline.com/
https://findamortgagebroker.com/Profile/WilliamRappJr28883
https://billrapp.commloan.com/
https://billrapponline.com/financingfuturescre-houston-katy
https://houstoncommercialmortgage.com/
https://author.billrapponline.com
https://doctorvideo.billrapponline.com/
https://veteransvideo.billrapponline.com/
https://mortgageviking.billrapponline.com/
https://fha203h.billrapponline.com/
https://renovationvideo.billrapponline.com
https://medallionfunds.com/bill-rapp/
https://www.amazon.com/dp/B0F32Z5BH2
https://veed.cello.so/FOmzTty6oi9
https://buymeacoffee.com/vikingente3
https://creplaybookseries.billrapponline.com
https://creplaybook.billrapponline.com/
© Bill Rapp, Medallion Funds LLC, Director of Capital Advisory
10 Tips for First-Time Homebuyers
Buying your first home can be both exciting and nerve-wracking at the same time. With so many things to consider and....
How To Choose the Right Lender for You
Lorem Ipsum is simply dummy text of the printing and typesetting industry. Lorem Ipsum has been the industry's standard dummy
Refinancing youe loan and when to do it
Lorem Ipsum is simply dummy text of the printing and typesetting industry. Lorem Ipsum has been the industry's standard dummy
Copyright ©2021 | Mortgage Viking Team
Licensed to Do Business | NMLS # 228246
This is not an offer to enter into an agreement. Not all customers will qualify. Information, rates and programs are subject to change without notice. All products are subject to credit and property approval. Other restrictions and limitations may apply. Copyright © 2021 | Medallion Funds
Corporate | NMLS ID NMLS # 1825831
Corporate Address : 2651 N. Green Valley Pkwy STE. 101 Henderson, NV 89014
Corporate NMLS NMLS # 1825831 | Company Website: https://medallionfunds.com/bill-rapp/
Copyright ©2021 | Mortgage Viking Team Licensed to Do Business | NMLS # 228246
This is not an offer to enter into an agreement. Not all customers will qualify. Information, rates and programs are subject to change without notice. All products are subject to credit and property approval. Other restrictions and limitations may apply
Corporate | NMLS ID NMLS # 1825831
Corporate Address : 2651 N. Green Valley Pkwy STE. 101 Henderson, NV 89014 https://medallionfunds.com/bill-rapp/
Facebook
Instagram
X
LinkedIn
Youtube
TikTok