Low Rates.
Our rates are low, our application is quick and easy! We can get you clear to close in as little as 10 days!
Trusted By Agents With
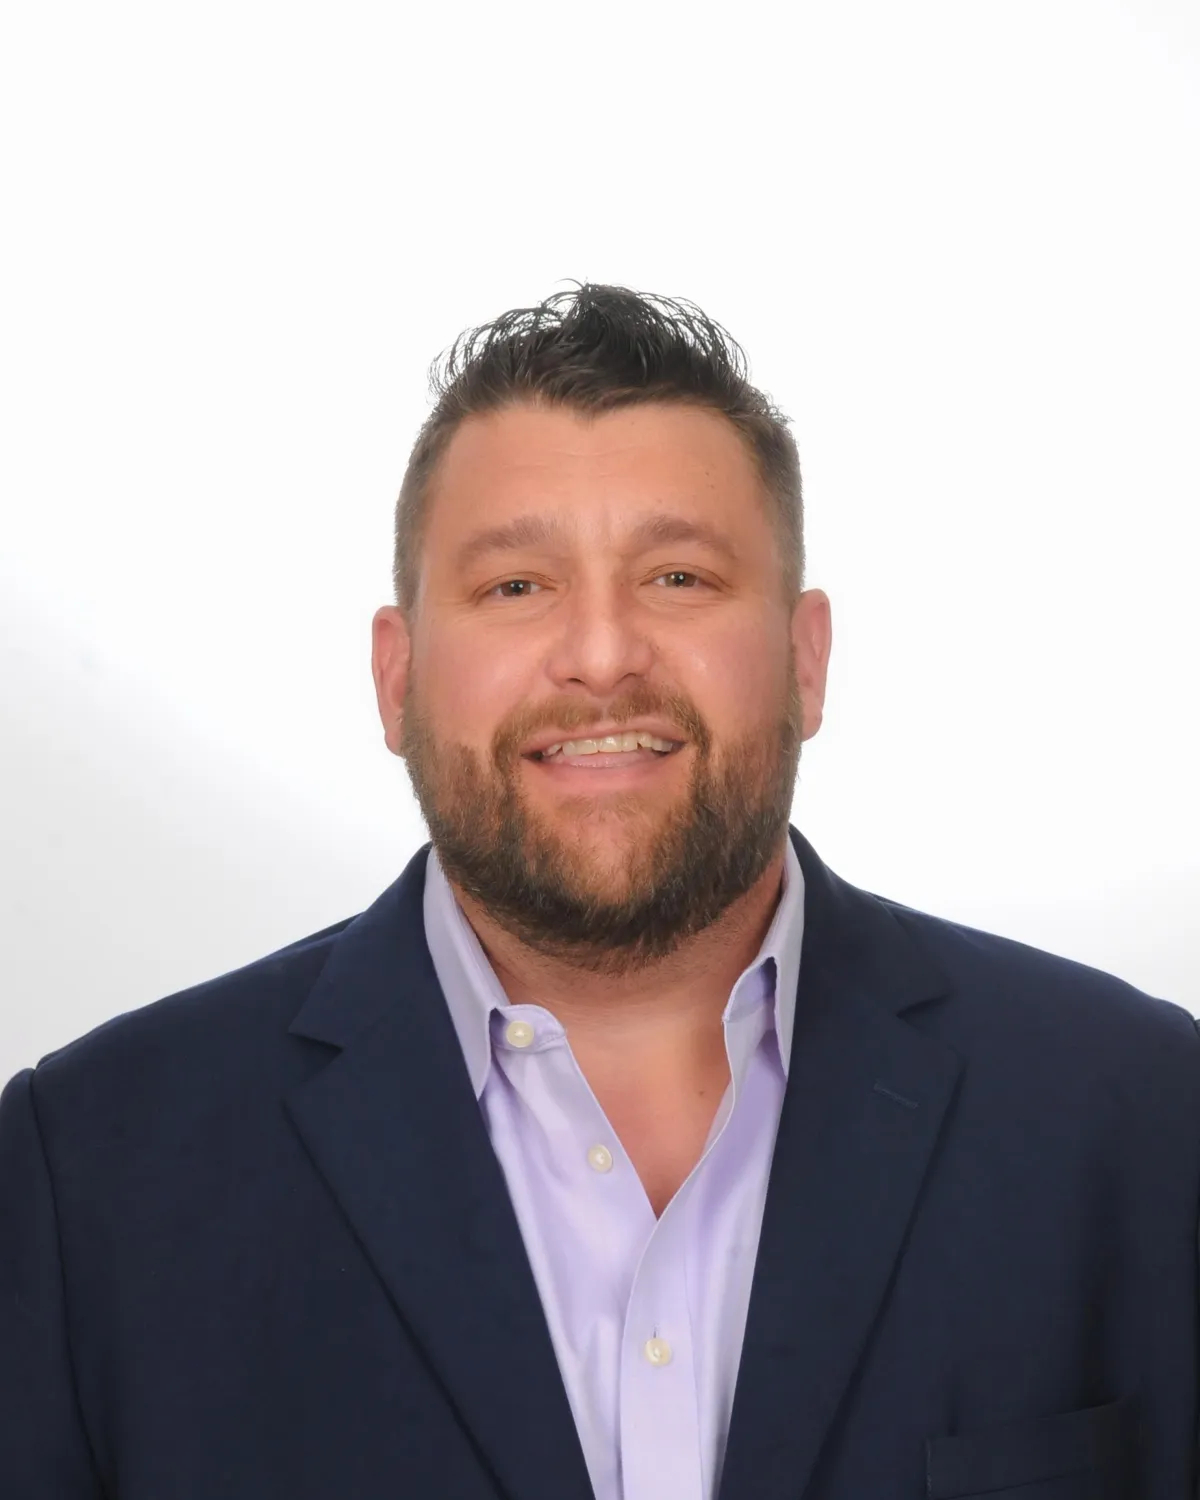
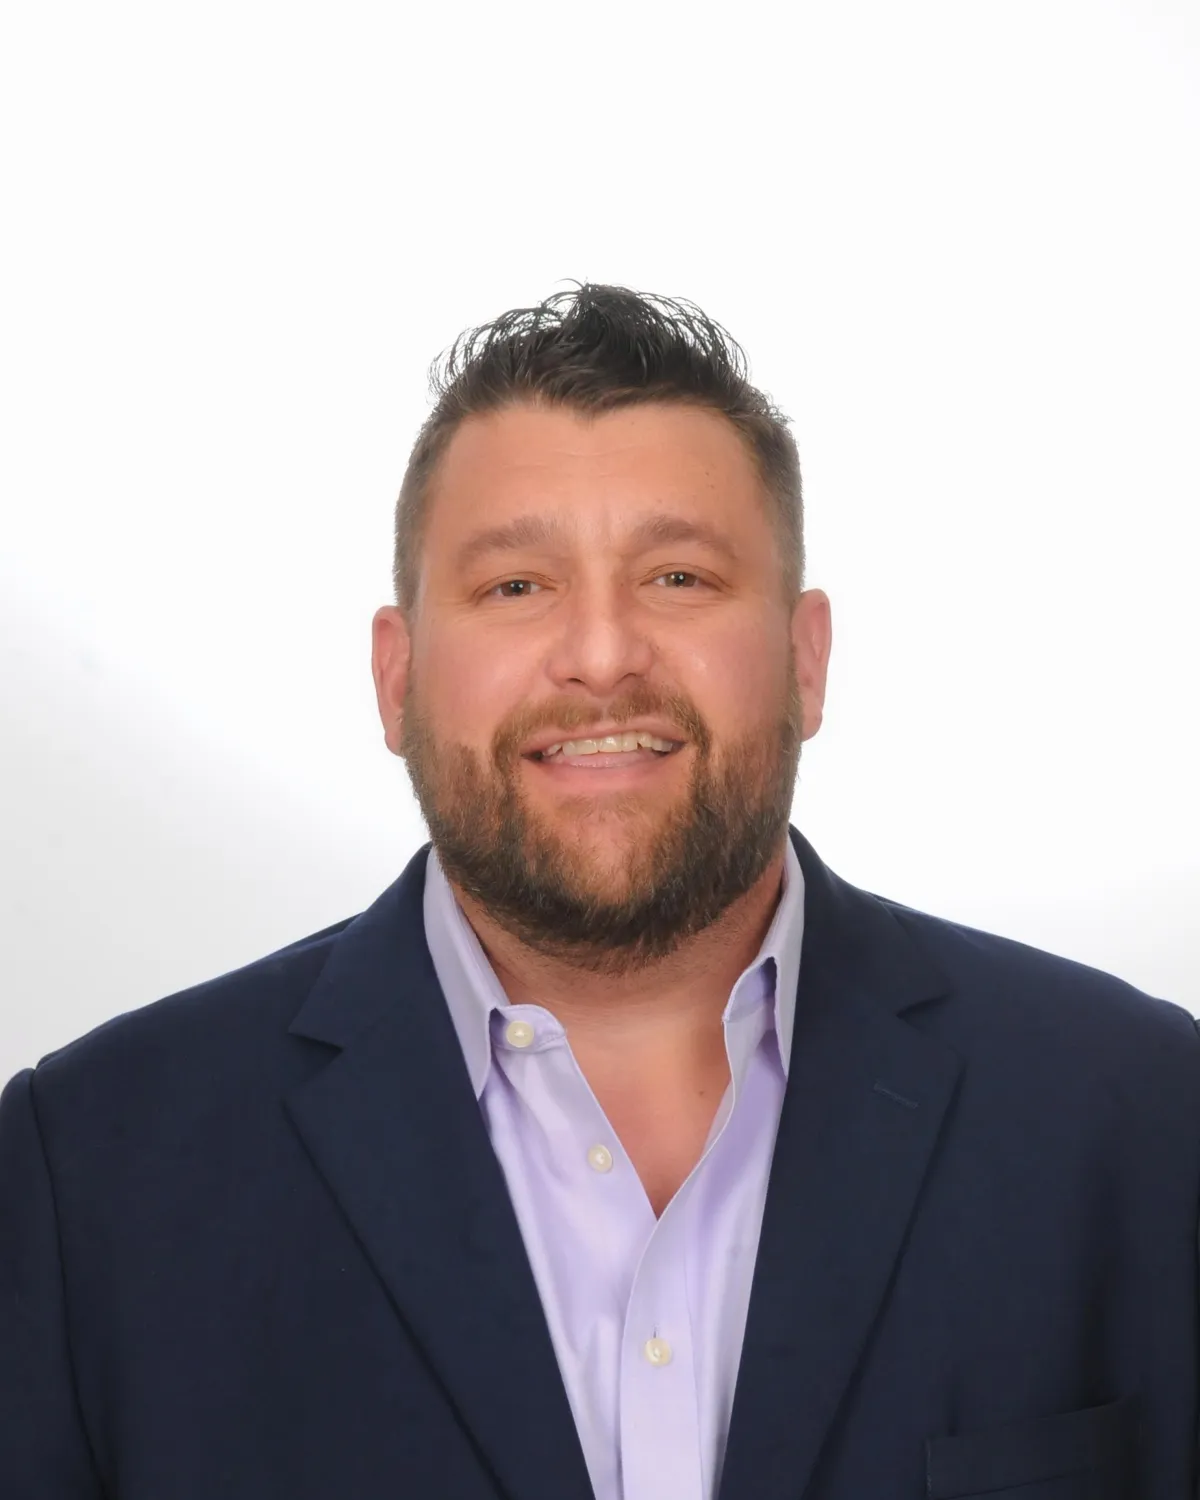
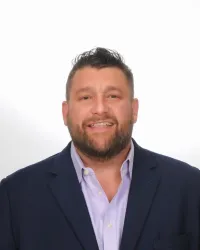
Meet Bill Rapp
NMLS ID # NMLS # 228246
Bill Rapp, CCIM is a Houston-based Capital Advisor at Medallion Funds, specializing in commercial real estate finance and strategic lending solutions. With over two decades of experience across brokerage and capital markets, Bill has worked with leading firms including eXp Commercial, NEXA Mortgage, Viking Enterprise LLC, and Sun Realty Houston.
A graduate of Texas A&M University with a BBA in Finance, Bill brings a disciplined, underwriting-first approach to every deal. His expertise spans commercial and residential financing, including asset-based lending, FHA financing, reverse mortgages, REO properties, and investment strategies for both single-family and commercial assets.
Known for his focus on structure over rate, Bill helps investors, business owners, and developers navigate complex transactions with clarity, precision, and a long-term wealth-building mindset.
The Client Experience
Great experience purchasing our first home! Bill was easy to reach and always able to answer any questions or concerns.

Loan Programs Available
Blogs
The Top 5 Mortgage Mistakes to Avoid
Buying your first home can be both exciting and nerve-wracking at the same time. With so many things to consider and....
Mortgage Do and
Do not list
Mortgages can be tricky, and it's easy to make mistakes that can end up costing you dearly. That's why we've put together this list....
Tips On How To Improve Your Credit Score
Let's talk about some ways you can improve your credit score! Your credit score is actually a big deal, and it can affect...
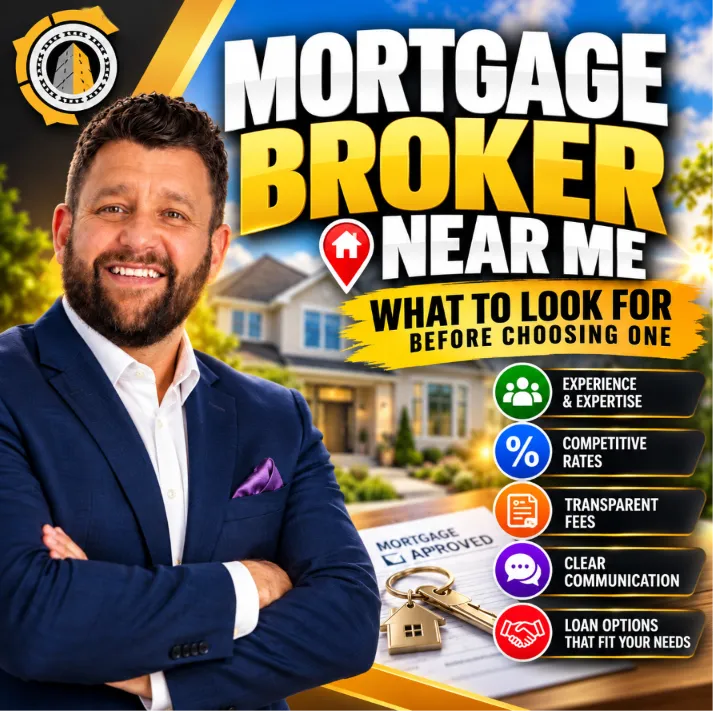
🏡 Mortgage Broker Near Me: 10 Things to Look for Before Choosing a Mortgage Professional 🔑
🏡 Mortgage Broker Near Me: 10 Things to Look for Before Choosing a Mortgage Professional 🔑
💰 How to Find the Best Mortgage Broker Near You: Compare Rates, Fees & Loan Options Before You Buy 🏠
________________________________________________________________________________
🏡 Mortgage Broker Near Me: 10 Things to Look for Before Choosing a Mortgage Professional 🔑
Searching for a "mortgage broker near me" is often one of the first steps toward buying a home, refinancing an existing mortgage, or financing an investment property.
But here's something many borrowers don't realize:
The closest mortgage broker isn't necessarily the best mortgage broker for your financial situation.
Choosing the right mortgage professional can influence your loan options, closing costs, interest rate, monthly payment, and overall homebuying experience.
Whether you're purchasing your first home in Katy, moving to Fulshear, refinancing in Houston, or purchasing rental property, knowing what to look for can help you make a more informed financial decision.
At Medallion Funds, we believe mortgage financing should begin with understanding your goals—not simply quoting an interest rate.
Let's explore ten important factors to evaluate before choosing a mortgage broker.
1. Understand What a Mortgage Broker Actually Does
A mortgage broker serves as an intermediary between borrowers and mortgage lenders.
Unlike a traditional bank that primarily offers its own mortgage products, a mortgage broker can work with multiple wholesale lenders to identify financing options that may fit your financial circumstances.
A mortgage broker typically helps borrowers:
·Evaluate available mortgage programs.
·Compare loan structures and pricing.
·Understand qualification requirements.
·Prepare mortgage applications and documentation.
·Navigate underwriting and closing.
·Identify financing alternatives for unique financial situations.
For example, a self-employed borrower who struggles to qualify through a traditional bank may benefit from exploring alternative documentation programs through a mortgage broker.
Key takeaway: A good mortgage broker helps you evaluate financing solutions, not just complete a loan application.
2. Look for Experience and Mortgage Industry Knowledge
Mortgage lending involves much more than credit scores and interest rates.
A knowledgeable mortgage broker should understand:
·Debt-to-income ratios (DTI).
·Loan-to-value ratios (LTV).
·Mortgage underwriting requirements.
·Credit qualification standards.
·Property appraisal issues.
·Mortgage insurance.
·Closing costs and prepaid expenses.
·Conventional and government-backed loan programs.
Ask prospective brokers how long they've worked in mortgage lending and whether they regularly handle transactions similar to yours.
At Medallion Funds, Bill Rapp brings mortgage lending experience dating back to 2002, along with commercial real estate and capital advisory expertise.
That combination can be particularly valuable for borrowers whose financial goals involve both homeownership and real estate investing.
3. Compare Mortgage Loan Programs, Not Just Interest Rates
Not every borrower fits the same mortgage program.
An experienced mortgage broker should evaluate your financial profile and discuss financing options that match your needs.
Common mortgage products include:
Conventional Loans
Often appropriate for borrowers with qualifying credit, income, and down payment resources.
FHA Loans
Government-insured mortgages that may provide flexible qualification opportunities for eligible borrowers.
VA Loans
Designed for eligible veterans, active-duty military personnel, and certain surviving spouses. Qualified borrowers may be able to purchase a home without a down payment.
USDA Loans
May offer zero-down-payment financing for eligible borrowers purchasing qualifying properties in designated areas.
Jumbo Mortgages
Designed for loan amounts exceeding applicable conforming loan limits.
Doctor and Dentist Mortgage Programs
Specialized financing programs that may offer attractive features for eligible medical professionals.
Bank Statement Mortgages
Alternative documentation programs that may help qualifying self-employed borrowers demonstrate income through business or personal bank deposits.
DSCR Investor Loans
Real estate investor financing that generally emphasizes rental property cash flow rather than traditional personal income calculations.
Not every lender offers every product, and eligibility, pricing, down payments, and documentation requirements vary.
The best mortgage program is the one that aligns with your financial qualifications, property, and long-term goals.
4. Ask About Mortgage Rates, APR, and Total Closing Costs
One of the biggest mistakes borrowers make is choosing a mortgage solely because of an advertised interest rate.
The lowest quoted interest rate does not automatically mean the lowest overall borrowing cost.
When comparing mortgage offers, evaluate:
·Interest rate.
·Annual Percentage Rate (APR).
·Discount points.
·Origination charges.
·Lender credits.
·Mortgage insurance.
·Estimated monthly payment.
·Cash required to close.
·Total financing costs over your expected ownership period.
For example, one lender might offer a lower interest rate but charge substantial discount points.
Another lender might offer a slightly higher rate with fewer upfront costs.
Depending on how long you plan to keep the mortgage, the second option could be financially preferable.
Ask your mortgage broker to explain the Loan Estimate and compare the total cost of each financing option.
5. Evaluate Communication and Responsiveness
Mortgage transactions are deadline-driven.
Purchase contracts, financing contingencies, appraisal schedules, underwriting conditions, and closing dates all require coordination.
A mortgage broker who communicates poorly can create unnecessary uncertainty.
Before choosing a broker, ask:
·How quickly do you respond to questions?
·Will I work directly with you or primarily with a processing team?
·How frequently will I receive updates?
·How are underwriting issues handled?
·Will you communicate with my real estate agent?
·What happens if unexpected problems arise before closing?
The answers can reveal whether the broker has a reliable process.
Strong communication is especially important when you're purchasing a home under a tight contract deadline.
6. Check Licensing, Credentials, and Professional Reputation
Before working with a mortgage professional, verify their licensing information.
The Nationwide Multistate Licensing System (NMLS) provides a free consumer lookup tool.
You can research mortgage companies and individual mortgage loan originators at:
https://www.nmlsconsumeraccess.org/
Review the professional's licensing status, company affiliation, and relevant regulatory information.
You should also consider client reviews, referrals from real estate professionals, and the broker's experience with your particular loan type.
Bill Rapp Jr. | NMLS #228246
Medallion Funds provides residential mortgage services in states where it is appropriately licensed or authorized.
7. Choose a Broker Who Understands Your Local Housing Market
If you're searching for a mortgage broker in Katy, TX, mortgage broker in Fulshear, or mortgage broker in Houston, local real estate knowledge can provide additional value.
The Greater Houston housing market includes established neighborhoods, master-planned communities, new construction, suburban expansion, and investment properties.
Different transactions may present different financing considerations.
For example:
New Construction Homes
Builder incentives, interest-rate buydowns, extended closing schedules, and appraisal considerations can affect financing decisions.
First-Time Homebuyers
Down payment requirements, closing costs, property taxes, and mortgage insurance may influence affordability.
Real Estate Investors
Rental income, reserve requirements, DSCR calculations, and property condition can affect financing eligibility.
Texas Homebuyers
Property taxes, homeowners insurance, flood insurance where applicable, and homeowners association assessments should be evaluated when calculating monthly housing costs.
A broker familiar with these considerations can help borrowers prepare more effectively.
8. Look for Solutions for Nontraditional Borrowers
Traditional mortgage underwriting does not work equally well for every borrower.
Some applicants have strong financial resources but unconventional income documentation.
Examples include:
·Self-employed business owners.
·Independent contractors.
·Gig economy workers.
·Real estate investors.
·Physicians beginning their careers.
·Borrowers with substantial assets but limited W-2 income.
·Borrowers with complex tax returns.
A mortgage broker with access to specialized programs may be able to explore alternative qualification approaches.
For instance, some bank statement mortgage programs evaluate eligible deposits rather than relying exclusively on traditional tax-return income calculations.
Other programs may consider eligible assets or investment-property cash flow.
These loans can have different rates, fees, reserve requirements, and eligibility standards than conventional mortgages.
A borrower who does not qualify for one mortgage program may still have other financing options worth evaluating.
9. Ask About the Pre-Approval Process
A mortgage pre-approval can help establish your purchasing budget and strengthen your preparation before making an offer.
However, not all pre-approval processes involve the same level of review.
Ask your broker whether the process includes:
·Credit review.
·Income documentation.
·Employment verification.
·Asset verification.
·Debt analysis.
·Review of potential underwriting concerns.
A thorough pre-approval process can help identify issues earlier.
It can also help you understand your estimated monthly payment, cash-to-close requirements, and potential financing limitations.
Remember that pre-approval is not a final loan commitment.
Final approval generally depends on underwriting, property eligibility, appraisal, title, and other applicable conditions.
10. Choose a Mortgage Advisor Who Thinks Beyond Closing Day
A mortgage is a long-term financial obligation.
Your financing decision should consider more than simply getting approved today.
An experienced mortgage advisor should help you think through questions such as:
·How long do you expect to own the property?
·Would a fixed-rate or adjustable-rate mortgage better fit your plans?
·How much cash should you retain after closing?
·Should you pay discount points?
·Would a larger down payment improve your financial position?
·How would the payment fit your long-term budget?
·Are you planning to purchase additional investment properties?
For some borrowers, preserving liquidity may be more important than maximizing the down payment.
For others, reducing the monthly payment may be the priority.
The right mortgage strategy should support your broader financial objectives.
Mortgage Broker vs. Bank: What's the Difference?
Both banks and mortgage brokers can provide valuable financing services.
The primary difference is how they source mortgage products.
Mortgage Broker | Traditional Bank |
May access multiple wholesale lenders | Primarily offers its own mortgage products |
Can compare participating lender programs | Offers programs available through its institution |
May offer specialized Non-QM financing | May offer proprietary or portfolio loan programs |
Coordinates financing with participating lenders | Typically originates through its own lending operation |
Pricing depends on lender and transaction | Pricing depends on bank and transaction |
Neither option is automatically cheaper or better.
Borrowers should compare actual Loan Estimates, financing terms, service quality, and product availability.
Seven Questions to Ask Before Hiring a Mortgage Broker
Before selecting your mortgage professional, consider asking:
1.How many years of mortgage lending experience do you have?
2.Which loan programs are available for my situation?
3.Can you explain your fees and how you are compensated?
4.How do your loan options compare on APR and total costs?
5.What documentation will I need for pre-approval?
6.How will you communicate throughout the transaction?
7.What potential issues do you see with my financing scenario?
A qualified mortgage professional should be comfortable discussing these questions clearly.
Why Consider Medallion Funds?
At Medallion Funds, our approach centers on helping borrowers understand their financing choices and identify mortgage solutions aligned with their goals.
Whether you're buying your first home, purchasing a larger residence, refinancing, or expanding a rental property portfolio, we can help evaluate potential lending strategies.
Our financing focus includes conventional, FHA, VA, jumbo, doctor and dentist, bank statement, Non-QM, and real estate investor loan programs.
We work with borrowers across the Greater Houston area, including Katy, Fulshear, Richmond, Cypress, Sugar Land, and surrounding communities, as well as other states where properly authorized.
Ready to Find the Right Mortgage Solution?
Searching for a mortgage broker near me should be about finding the right combination of experience, financing options, transparent costs, and professional service.
Before making one of your largest financial commitments, take time to compare your options and ask the right questions.
Bill Rapp
Partner & Director of Capital Advisory | Medallion Funds
Commercial Lending Nationwide
Residential Lending in AL, CA, CO, NV & TXBottom of Form
https://www.billrapponline.com/
https://findamortgagebroker.com/Profile/WilliamRappJr28883
https://billrapp.commloan.com/
https://billrapponline.com/financingfuturescre-houston-katy
https://houstoncommercialmortgage.com/
https://author.billrapponline.com
https://doctorvideo.billrapponline.com/
https://veteransvideo.billrapponline.com/
https://mortgageviking.billrapponline.com/
https://fha203h.billrapponline.com/
https://renovationvideo.billrapponline.com
https://medallionfunds.com/bill-rapp/
https://www.amazon.com/dp/B0F32Z5BH2
https://veed.cello.so/FOmzTty6oi9
https://buymeacoffee.com/vikingente3
https://creplaybookseries.billrapponline.com
https://creplaybook.billrapponline.com/
© Bill Rapp, Medallion Funds LLC, Director of Capital Advisory
10 Tips for First-Time Homebuyers
Buying your first home can be both exciting and nerve-wracking at the same time. With so many things to consider and....
How To Choose the Right Lender for You
Lorem Ipsum is simply dummy text of the printing and typesetting industry. Lorem Ipsum has been the industry's standard dummy
Refinancing youe loan and when to do it
Lorem Ipsum is simply dummy text of the printing and typesetting industry. Lorem Ipsum has been the industry's standard dummy
Copyright ©2021 | Mortgage Viking Team
Licensed to Do Business | NMLS # 228246
This is not an offer to enter into an agreement. Not all customers will qualify. Information, rates and programs are subject to change without notice. All products are subject to credit and property approval. Other restrictions and limitations may apply. Copyright © 2021 | Medallion Funds
Corporate | NMLS ID NMLS # 1825831
Corporate Address : 2651 N. Green Valley Pkwy STE. 101 Henderson, NV 89014
Corporate NMLS NMLS # 1825831 | Company Website: https://medallionfunds.com/bill-rapp/
Copyright ©2021 | Mortgage Viking Team Licensed to Do Business | NMLS # 228246
This is not an offer to enter into an agreement. Not all customers will qualify. Information, rates and programs are subject to change without notice. All products are subject to credit and property approval. Other restrictions and limitations may apply
Corporate | NMLS ID NMLS # 1825831
Corporate Address : 2651 N. Green Valley Pkwy STE. 101 Henderson, NV 89014 https://medallionfunds.com/bill-rapp/
Facebook
Instagram
X
LinkedIn
Youtube
TikTok