Low Rates.
Our rates are low, our application is quick and easy! We can get you clear to close in as little as 10 days!
Trusted By Agents With
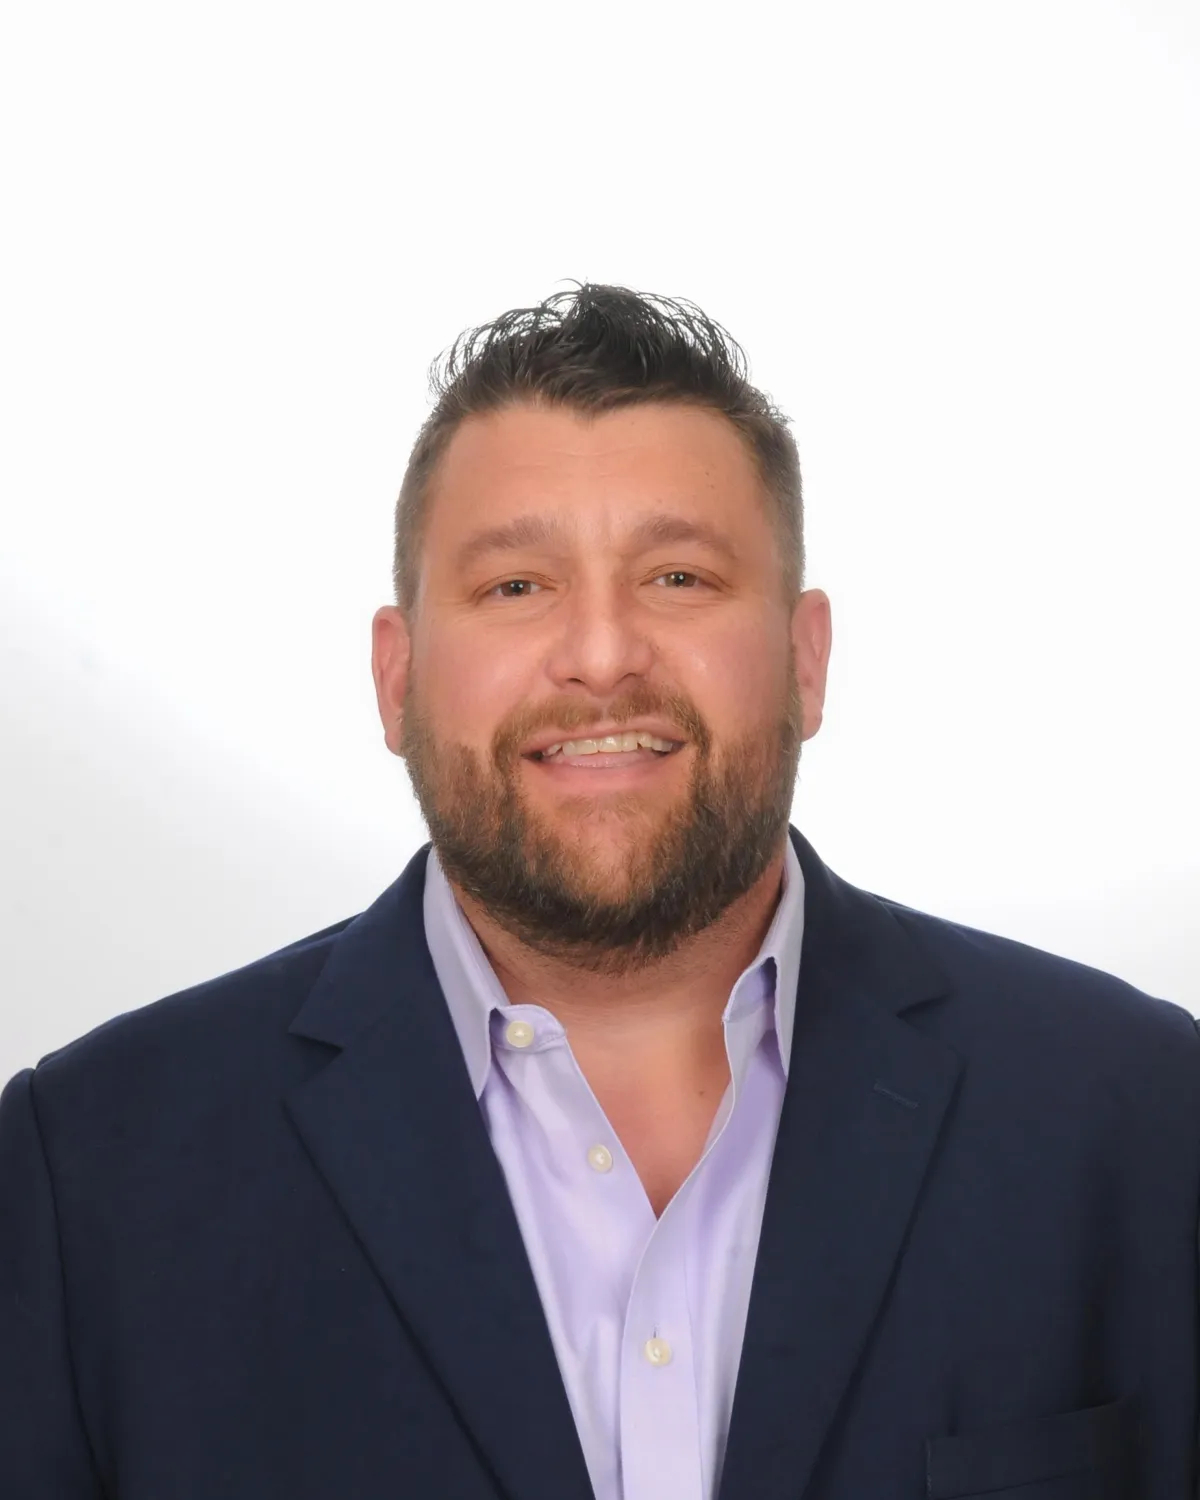
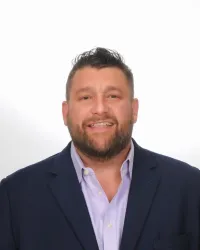
Meet Bill Rapp
NMLS ID # NMLS # 228246
Bill Rapp, CCIM is a Houston-based Capital Advisor at Medallion Funds, specializing in commercial real estate finance and strategic lending solutions. With over two decades of experience across brokerage and capital markets, Bill has worked with leading firms including eXp Commercial, NEXA Mortgage, Viking Enterprise LLC, and Sun Realty Houston.
A graduate of Texas A&M University with a BBA in Finance, Bill brings a disciplined, underwriting-first approach to every deal. His expertise spans commercial and residential financing, including asset-based lending, FHA financing, reverse mortgages, REO properties, and investment strategies for both single-family and commercial assets.
Known for his focus on structure over rate, Bill helps investors, business owners, and developers navigate complex transactions with clarity, precision, and a long-term wealth-building mindset.
The Client Experience
Great experience purchasing our first home! Bill was easy to reach and always able to answer any questions or concerns.

Loan Programs Available


Blogs
The Top 5 Mortgage Mistakes to Avoid
Buying your first home can be both exciting and nerve-wracking at the same time. With so many things to consider and....
Mortgage Do and
Do not list
Mortgages can be tricky, and it's easy to make mistakes that can end up costing you dearly. That's why we've put together this list....
Tips On How To Improve Your Credit Score
Let's talk about some ways you can improve your credit score! Your credit score is actually a big deal, and it can affect...
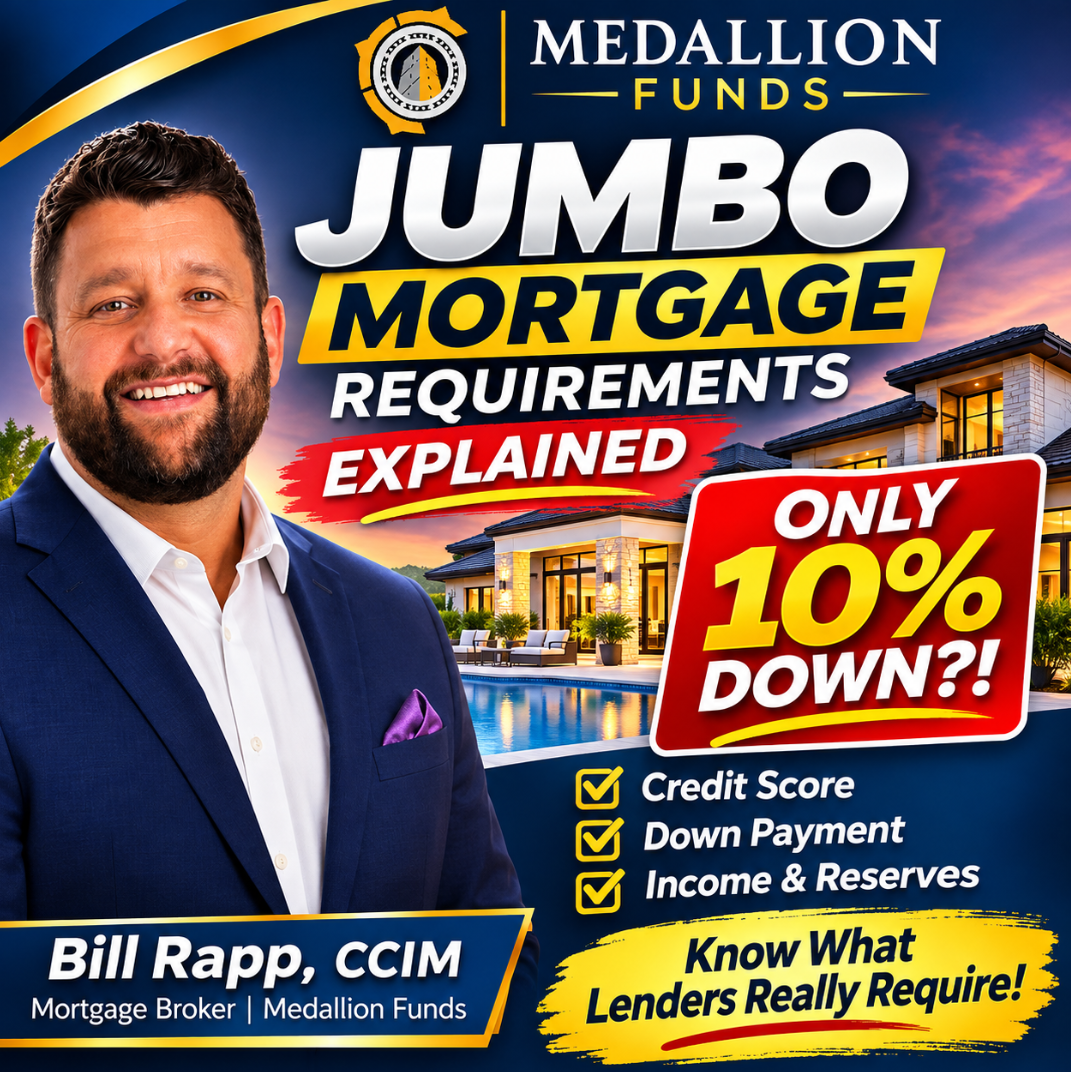
🏡 Jumbo Mortgage Requirements Explained 💰
🏡 Jumbo Mortgage Requirements Explained 💰
💰 How to Qualify for a Jumbo Loan 🏡
___________________________________________________________________________
🏡 Jumbo Mortgage Requirements Explained 💰
By Bill Rapp, CCIM | Medallion Funds | Mortgage Viking
Buying a luxury home or a higher-priced property? You may need a jumbo mortgage—but qualifying for one can be different from obtaining a traditional conventional home loan.
Whether you're purchasing a luxury home in Houston, upgrading to a larger property in Katy or Fulshear, or buying your first home as a physician, dentist, or successful business owner, understanding jumbo mortgage requirements can help you prepare for a smoother financing experience.
The good news? You don't necessarily need a 20% down payment, perfect credit, or a traditional W-2 income to qualify.
Let's explore how jumbo home loans work, what lenders look for, and how you can position yourself for approval.
What Is a Jumbo Mortgage?
A jumbo mortgage is a home loan that exceeds the applicable conforming loan limit established by the Federal Housing Finance Agency (FHFA).
Conforming mortgages generally follow guidelines that allow them to be purchased by Fannie Mae or Freddie Mac. Jumbo mortgages exceed those loan limits and are typically funded through private lenders, banks, or other non-agency mortgage programs.
Because jumbo lenders assume additional risk on larger loan balances, their underwriting requirements can be more restrictive.
However, jumbo loan programs vary significantly between lenders, creating opportunities for qualified borrowers who may not fit traditional lending guidelines.
Important: A jumbo mortgage is determined by the loan amount, not simply the home's purchase price.
For example, purchasing a $1 million home does not automatically mean you need a jumbo mortgage. Your down payment and the applicable county loan limit determine whether your mortgage falls into the jumbo category.
2026 Jumbo Mortgage Loan Limits
For 2026, the baseline conforming loan limit for a one-unit property in most U.S. counties is $832,750.
In designated high-cost areas, the maximum conforming loan limit for a one-unit property can reach $1,249,125.
In most Texas markets, including the Houston metropolitan area, a one-unit mortgage exceeding the baseline conforming loan limit generally requires jumbo or another nonconforming financing solution.
Loan limits are updated annually, and limits for two- to four-unit properties are different.
Understanding the applicable loan limit is especially important when purchasing higher-priced homes in communities such as:
·Katy
·Fulshear
·The Woodlands
·Sugar Land
·Memorial
·River Oaks
·West University
A strategic down payment may allow some buyers to remain within conforming loan limits, while others may benefit from a jumbo mortgage.
What Are the Requirements for a Jumbo Mortgage?
Jumbo mortgage requirements depend on the lender, loan amount, property type, occupancy, and borrower's overall financial profile.
Here are the five primary areas lenders evaluate.
1. Jumbo Loan Credit Score Requirements
Credit scores are an important component of jumbo mortgage underwriting.
Many jumbo mortgage lenders prefer credit scores of 700 or higher, while certain programs may consider borrowers with scores in the upper 600s.
Borrowers with credit scores of 740 or higher may have access to more competitive pricing and additional financing options, depending on the program.
Lenders also evaluate:
·Mortgage payment history
·Recent late payments
·Credit utilization
·Outstanding debts
·Recent credit inquiries
·Bankruptcies or foreclosures
A strong credit score can improve your financing options, but it does not guarantee approval.
Your complete financial profile matters.
2. Jumbo Loan Down Payment Requirements
One of the biggest misconceptions about jumbo mortgages is that every borrower must put 20% down.
While a 20% down payment remains common, some jumbo mortgage programs may allow qualified buyers to purchase a home with as little as 10% down.
Certain specialized professional mortgage programs may offer even lower down payment options, subject to eligibility and loan limits.
Typical financing scenarios may include:
Down Payment | Potential Financing Structure |
5%–10% | Select specialty or professional mortgage programs |
10%–15% | Select low-down-payment jumbo programs |
20% | Common traditional jumbo structure |
25%–30% | May be required for larger balances, second homes, or certain risk profiles |
Lower down payments may require stronger credit, additional cash reserves, or more restrictive debt-to-income ratios.
The right down payment is not always the largest down payment.
For physicians, dentists, entrepreneurs, and real estate investors, preserving liquidity may be an important part of a broader financial strategy.
3. Debt-to-Income Ratio Requirements
Your debt-to-income ratio, commonly called DTI, measures your monthly debt obligations relative to your gross monthly qualifying income.
Many jumbo mortgage programs prefer a DTI of approximately 43% or less, although some lenders may allow higher ratios for borrowers with strong compensating factors.
Monthly debt obligations can include:
·Proposed mortgage payment
·Property taxes and homeowners insurance
·HOA dues
·Automobile loans
·Student loans
·Credit card payments
·Other recurring debt obligations
For example, if your gross qualifying monthly income is $25,000 and your total monthly debt obligations are $10,000, your debt-to-income ratio is 40%.
That calculation helps lenders determine whether your income can support the proposed mortgage.
For doctors and dentists, student loan treatment can be particularly important. Certain physician mortgage programs use specialized underwriting guidelines that may provide more flexibility than traditional jumbo loans.
4. Income and Employment Documentation
Traditional jumbo mortgage lenders generally require borrowers to demonstrate stable, sufficient income.
Depending on your employment situation, documentation may include:
·Recent pay stubs
·W-2 forms
·Federal income tax returns
·Bank and investment statements
·Employment verification
·Business financial statements
·Documentation of bonuses, commissions, or other income
Self-employed borrowers may face additional documentation requirements because lenders need to establish the stability and sustainability of business income.
However, traditional income documentation is not the only option.
Certain non-QM jumbo mortgage programs may allow qualified borrowers to use bank statements, asset-based income calculations, or other alternative documentation methods.
These programs can be particularly useful for business owners, independent contractors, and high-net-worth borrowers whose tax returns do not fully reflect their financial capacity.
Alternative documentation programs typically have their own pricing, down payment, and eligibility requirements.
5. Cash Reserve Requirements
Jumbo mortgage lenders frequently require borrowers to maintain cash reserves after closing.
Cash reserves are funds available to cover future mortgage payments and related housing expenses.
Depending on the lender and loan size, borrowers may need approximately six to twelve months of reserves. Some programs require more, while others may require less.
For example, if your total monthly housing payment is $7,000, a twelve-month reserve requirement would equal $84,000.
Eligible reserves may include:
·Checking and savings accounts
·Brokerage accounts
·Certain retirement accounts
·Other eligible liquid or investment assets
Lenders may apply restrictions or discounts to certain assets when calculating eligible reserves.
Remember: your down payment, closing costs, and post-closing reserves are separate components of your financing strategy.
Jumbo Mortgage Example: Buying a $1.2 Million Home
Suppose you're purchasing a $1.2 million primary residence in the Houston area.
Here's how different down payment strategies could affect your mortgage.
Financing Scenario | 10% Down | 20% Down |
Purchase price | $1,200,000 | $1,200,000 |
Down payment | $120,000 | $240,000 |
Mortgage amount | $1,080,000 | $960,000 |
Loan-to-value ratio | 90% | 80% |
Illustrative interest rate | 6.75% | 6.75% |
Monthly principal and interest | $7,005 | $6,227 |
Both scenarios exceed the 2026 baseline conforming loan limit.
The 10% down payment option allows the buyer to retain an additional $120,000 in upfront capital. However, it also increases the monthly principal and interest payment by approximately $778.
The 20% down payment option reduces monthly debt service and may provide access to different loan programs or pricing.
Which strategy is better?
That depends on your income, liquidity, investment objectives, risk tolerance, and available mortgage programs.
Illustrative calculations assume a 30-year fixed-rate mortgage at a hypothetical 6.75% interest rate. This is not a current rate quote or financing offer. Payments exclude property taxes, homeowners insurance, HOA dues, mortgage insurance if applicable, and closing costs. Actual rates and terms vary.
Jumbo Loans for Doctors and Dentists
Physicians and dentists often have unique financial circumstances.
You may have significant student loan debt, limited savings following residency, or an employment contract reflecting substantial future income.
Certain physician mortgage programs may offer benefits such as:
·Reduced down payment requirements
·Specialized student loan treatment
·Eligibility based on qualifying employment contracts
·Financing for higher-priced primary residences
·Potential mortgage insurance alternatives
These programs are not universally available, and eligibility depends on your profession, career stage, loan amount, and lender requirements.
At Medallion Funds, we help medical professionals explore financing structures that align with their career and financial goals.
Jumbo Loans for Self-Employed Borrowers
Business owners often face a different challenge.
Your business may generate substantial revenue, but legitimate tax deductions can reduce the income shown on your tax returns.
That can make qualifying for a traditional jumbo mortgage more complicated.
Alternative financing options may include:
Bank statement loans: Qualifying income may be calculated using eligible personal or business bank deposits, subject to lender guidelines.
Asset depletion loans: Certain eligible assets may be used to establish qualifying income.
Traditional self-employed jumbo loans: Borrowers may qualify using tax returns and documented business income.
The key is identifying a lender whose underwriting approach fits your financial circumstances.
Jumbo vs. Conventional Mortgages
Feature | Conforming Conventional | Jumbo Mortgage |
Loan amount | Within applicable conforming limits | Above applicable conforming limits |
Credit requirements | May offer more flexibility | Often more restrictive |
Down payment | Some programs allow 3%–5% | Often 10%–20% or more |
Cash reserves | Program dependent | Frequently more substantial |
Income documentation | Standard agency guidelines | Lender-specific guidelines |
Interest rates | Market and borrower dependent | May be higher, similar, or lower |
Jumbo mortgage rates are not automatically higher than conforming mortgage rates.
Pricing depends on market conditions, lender appetite, loan-to-value ratio, creditworthiness, and other factors.
That's one reason comparing multiple lenders can be particularly valuable when financing a higher-priced home.
How to Improve Your Chances of Jumbo Mortgage Approval
Before making an offer on a luxury home, take these steps:
1.Review your credit report and address potential issues.
2.Reduce unnecessary revolving debt.
3.Document your income and employment history.
4.Identify your available down payment and closing funds.
5.Maintain adequate post-closing cash reserves.
6.Avoid major financial changes during underwriting.
7.Obtain a jumbo mortgage pre-approval before shopping.
A strong pre-approval can help you understand your purchasing power, identify potential underwriting challenges, and present a more credible offer to a seller.
Frequently Asked Questions About Jumbo Mortgages
Can I get a jumbo mortgage with 10% down?
Yes. Some lenders offer jumbo mortgage programs with 10% down for qualified borrowers. Eligibility depends on credit, income, reserves, property type, and loan amount.
What credit score do I need for a jumbo loan?
Many lenders prefer a score of at least 700, although certain programs may consider lower scores. Higher credit scores may improve your available options.
Do jumbo mortgages require private mortgage insurance?
Not necessarily. Some jumbo programs offer financing without traditional private mortgage insurance, even with less than 20% down. However, the lender may compensate for the additional risk through pricing or other loan requirements.
Are jumbo mortgage rates higher than conventional rates?
Not always. Jumbo rates can be higher, lower, or comparable depending on the lender and market conditions.
Can self-employed borrowers qualify for jumbo mortgages?
Yes. Self-employed borrowers may qualify through traditional income documentation or alternative programs, including certain bank statement and asset-based mortgages.
Can doctors qualify for a jumbo mortgage with student loan debt?
Yes. Certain physician mortgage programs offer specialized underwriting that may help eligible doctors and dentists qualify despite substantial student loan balances.
Can I refinance a jumbo mortgage?
Yes. Jumbo refinance programs may allow qualified homeowners to change their rate or loan term, or access home equity through a cash-out refinance, subject to lender and applicable state requirements.
Why Work With a Mortgage Broker for a Jumbo Loan?
Not all jumbo mortgage lenders evaluate borrowers the same way.
One lender may require a larger down payment. Another may offer more flexible income documentation. A third may specialize in physician mortgages or self-employed borrowers.
Working with an experienced mortgage broker can help you compare available financing structures rather than relying on a single lender's guidelines.
At Medallion Funds, we help borrowers evaluate mortgage options based on their financial profile, property goals, and long-term objectives.
Whether you're purchasing a luxury home, relocating to Texas, upgrading your primary residence, or exploring specialized financing as a doctor, dentist, or business owner, we can help you navigate the process.
Ready to Explore Your Jumbo Mortgage Options?
Don't let assumptions about credit scores, down payments, or income requirements prevent you from exploring your next home purchase.
The right mortgage strategy begins with understanding your options.
Contact Bill Rapp, CCIM, with Medallion Funds to discuss your jumbo mortgage financing needs.
Bill Rapp
Partner & Director of Capital Advisory | Medallion Funds
Commercial Lending Nationwide
Residential Lending in AL, CA, CO, NV & TXBottom of Form
📞 Call or Text: 281-222-0433
🌐 Website: https://billrapponline.com
🎥 Subscribe to Mortgage Viking: https://www.youtube.com/@billrapp-medallion-funds
https://www.billrapponline.com/
https://findamortgagebroker.com/Profile/WilliamRappJr28883
https://billrapp.commloan.com/
https://billrapponline.com/financingfuturescre-houston-katy
https://houstoncommercialmortgage.com/
https://author.billrapponline.com
https://doctorvideo.billrapponline.com/
https://veteransvideo.billrapponline.com/
https://mortgageviking.billrapponline.com/
https://fha203h.billrapponline.com/
https://renovationvideo.billrapponline.com
https://medallionfunds.com/bill-rapp/
https://www.amazon.com/dp/B0F32Z5BH2
https://veed.cello.so/FOmzTty6oi9
https://buymeacoffee.com/vikingente3
https://creplaybookseries.billrapponline.com
https://creplaybook.billrapponline.com/
© Bill Rapp, Medallion Funds LLC, Director of Capital Advisory
10 Tips for First-Time Homebuyers
Buying your first home can be both exciting and nerve-wracking at the same time. With so many things to consider and....
How To Choose the Right Lender for You
Lorem Ipsum is simply dummy text of the printing and typesetting industry. Lorem Ipsum has been the industry's standard dummy
Refinancing youe loan and when to do it
Lorem Ipsum is simply dummy text of the printing and typesetting industry. Lorem Ipsum has been the industry's standard dummy
Copyright ©2021 | Mortgage Viking Team
Licensed to Do Business | NMLS # 228246
This is not an offer to enter into an agreement. Not all customers will qualify. Information, rates and programs are subject to change without notice. All products are subject to credit and property approval. Other restrictions and limitations may apply. Copyright © 2021 | Medallion Funds
Corporate | NMLS ID NMLS # 1825831
Corporate Address : 2651 N. Green Valley Pkwy STE. 101 Henderson, NV 89014
Corporate NMLS NMLS # 1825831 | Company Website: https://medallionfunds.com/bill-rapp/
Copyright ©2021 | Mortgage Viking Team Licensed to Do Business | NMLS # 228246
This is not an offer to enter into an agreement. Not all customers will qualify. Information, rates and programs are subject to change without notice. All products are subject to credit and property approval. Other restrictions and limitations may apply
Corporate | NMLS ID NMLS # 1825831
Corporate Address : 2651 N. Green Valley Pkwy STE. 101 Henderson, NV 89014 https://medallionfunds.com/bill-rapp/
Facebook
Instagram
X
LinkedIn
Youtube
TikTok