Low Rates.
Our rates are low, our application is quick and easy! We can get you clear to close in as little as 10 days!
Trusted By Agents With
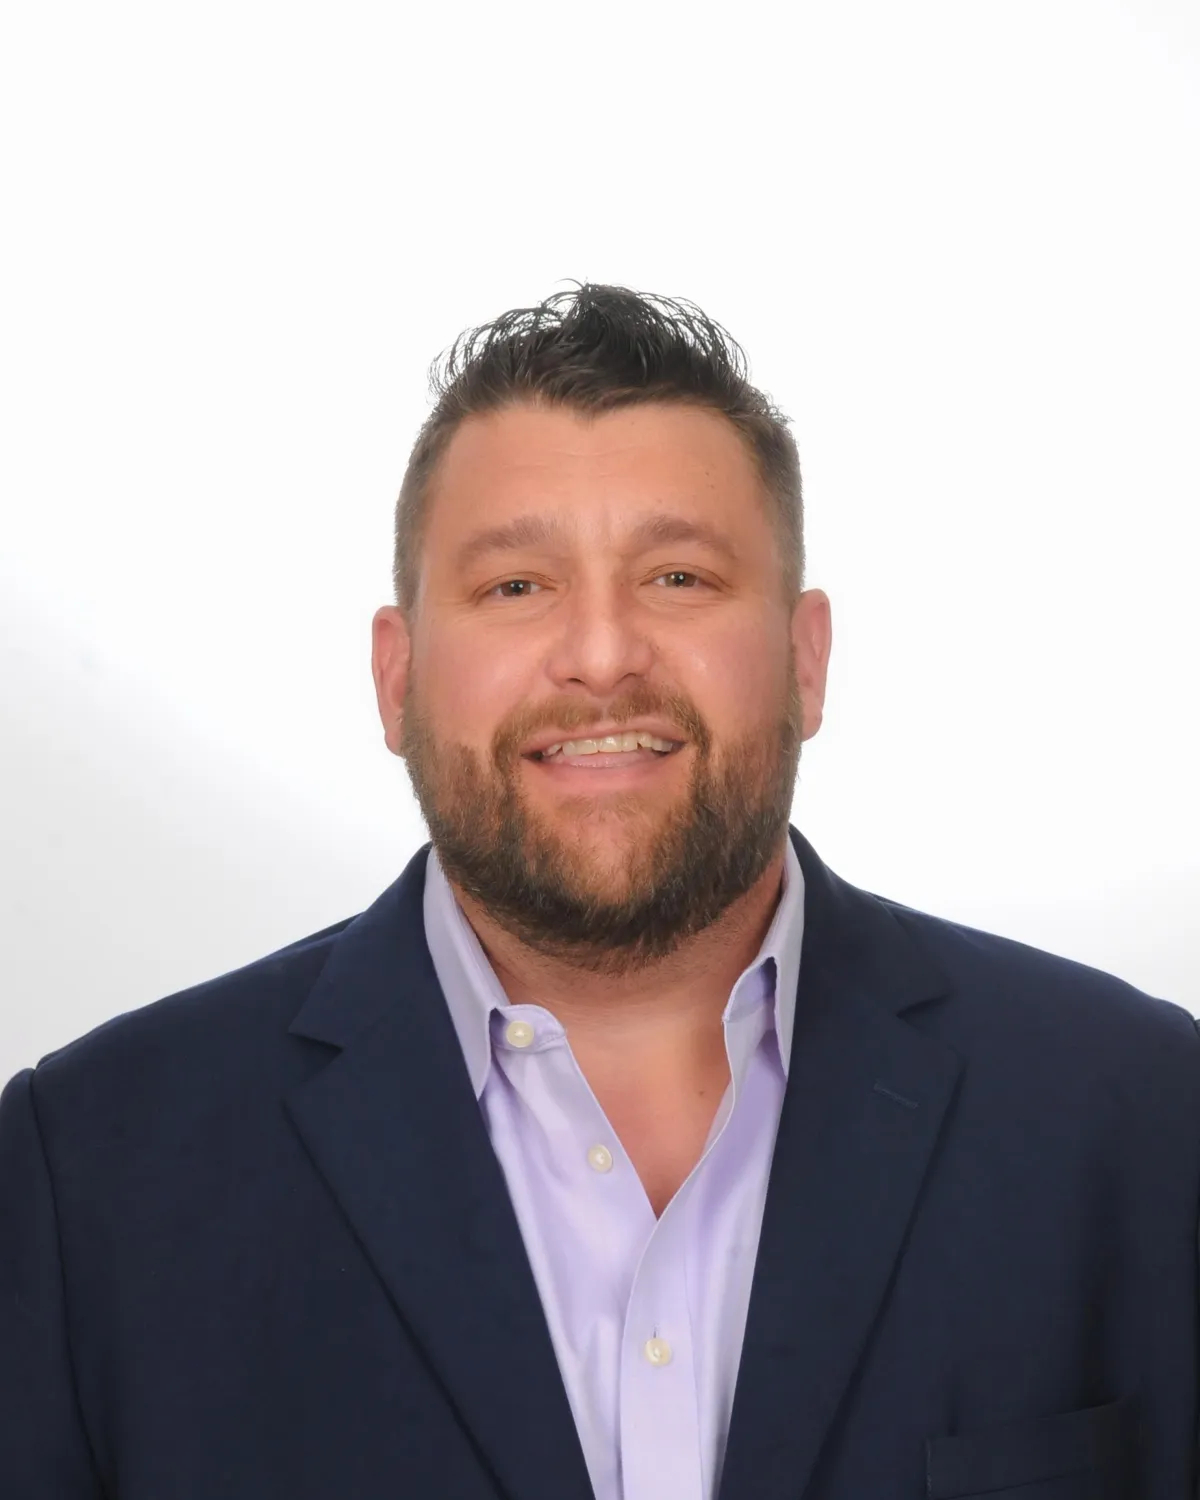
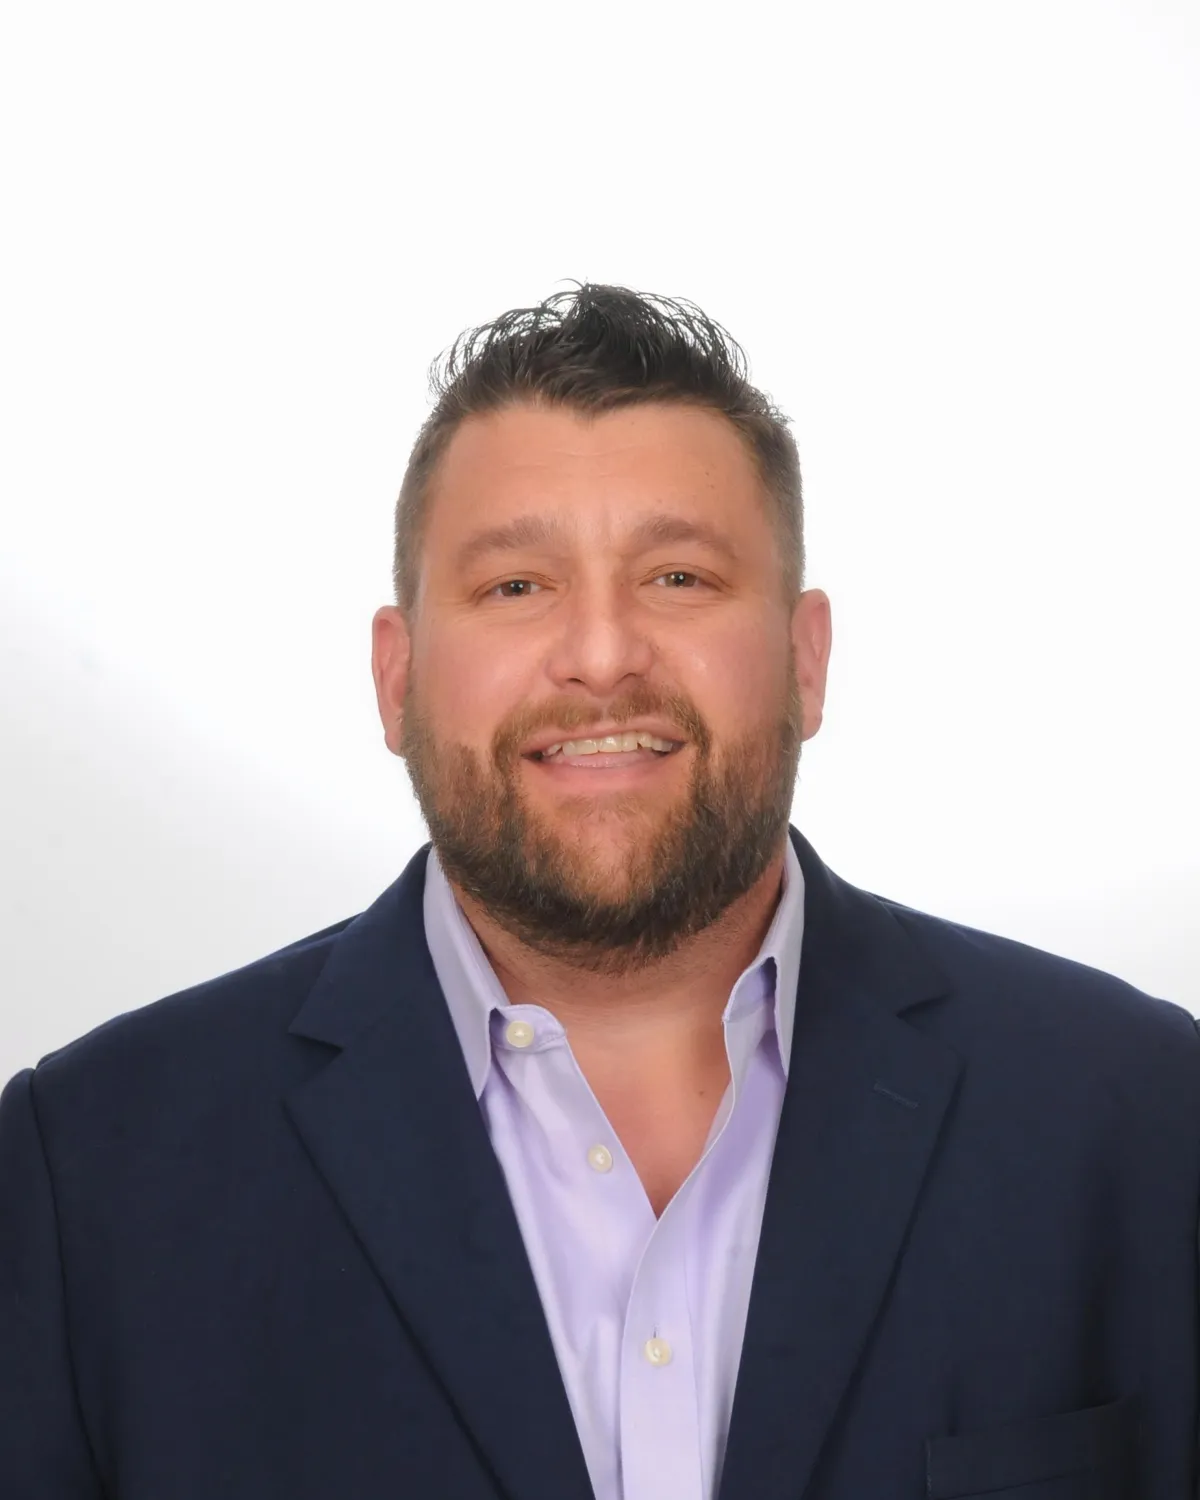
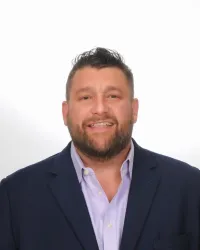
Meet Bill Rapp
NMLS ID # NMLS # 228246
Bill Rapp, CCIM is a Houston-based Capital Advisor at Medallion Funds, specializing in commercial real estate finance and strategic lending solutions. With over two decades of experience across brokerage and capital markets, Bill has worked with leading firms including eXp Commercial, NEXA Mortgage, Viking Enterprise LLC, and Sun Realty Houston.
A graduate of Texas A&M University with a BBA in Finance, Bill brings a disciplined, underwriting-first approach to every deal. His expertise spans commercial and residential financing, including asset-based lending, FHA financing, reverse mortgages, REO properties, and investment strategies for both single-family and commercial assets.
Known for his focus on structure over rate, Bill helps investors, business owners, and developers navigate complex transactions with clarity, precision, and a long-term wealth-building mindset.
The Client Experience
Great experience purchasing our first home! Bill was easy to reach and always able to answer any questions or concerns.

Loan Programs Available


Blogs
The Top 5 Mortgage Mistakes to Avoid
Buying your first home can be both exciting and nerve-wracking at the same time. With so many things to consider and....
Mortgage Do and
Do not list
Mortgages can be tricky, and it's easy to make mistakes that can end up costing you dearly. That's why we've put together this list....
Tips On How To Improve Your Credit Score
Let's talk about some ways you can improve your credit score! Your credit score is actually a big deal, and it can affect...
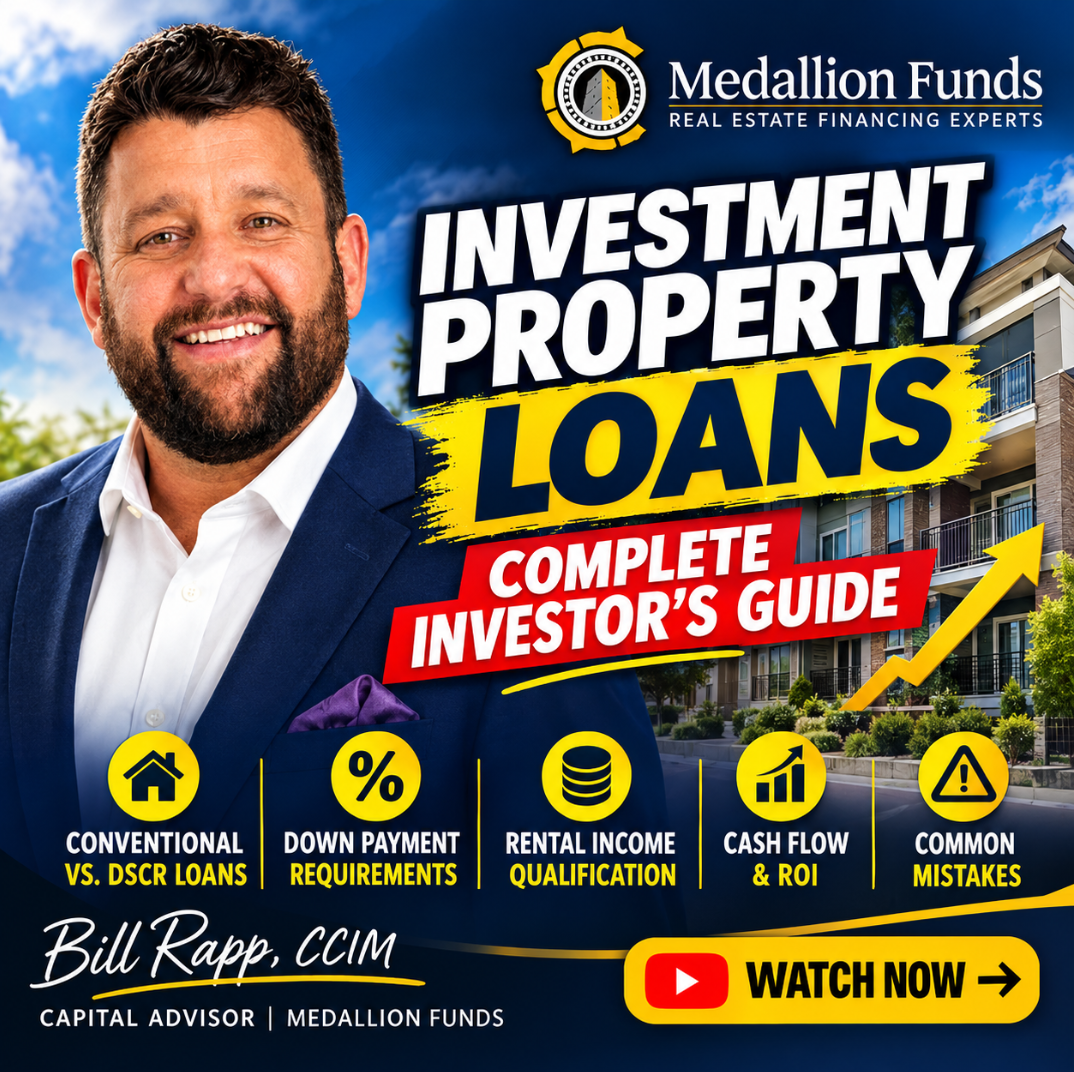
🏠 Investment Property Loans: Complete Investor's Guide 💰
🏠 Investment Property Loans: Complete Investor's Guide 💰
💵 Investment Property Loans: How to Finance Rentals 🏡
____________________________________________________________________________
Investment Property Loans: How to Finance Your Next Rental Property
Real estate investing can be one of the most effective ways to build long-term wealth. Rental properties can generate monthly cash flow, provide potential tax advantages, and appreciate over time.
But before you purchase your first rental home—or expand an existing portfolio—you need to understand one critical component of successful investing: investment property financing.
Not all investment property loans are created equal.
Some programs focus heavily on your personal income, employment history, and debt-to-income ratio. Others evaluate the property's rental income and its ability to support the mortgage payment.
Choosing the right financing structure can affect your cash flow, borrowing capacity, and ability to purchase additional properties.
At Medallion Funds, we help real estate investors evaluate multiple mortgage programs, including conventional investment property loans, DSCR loans, bank statement mortgages, and financing for small multifamily properties.
Let's explore how investment property loans work and how to choose the right financing strategy.
What Is an Investment Property Loan?
An investment property loan is financing used to purchase or refinance real estate primarily intended to generate income or investment returns rather than serve as your primary residence.
Common investment property types include:
·Single-family rental homes
·Duplexes, triplexes, and fourplexes
·Long-term rental properties
·Eligible short-term vacation rentals
·Properties purchased for renovation and resale
·Small multifamily investment properties
Financing options depend on the property's intended use, occupancy, condition, number of units, and borrower qualifications.
For example, a conventional mortgage may work well for a borrower purchasing a single-family rental home with documented W-2 income.
An investor with multiple rental properties might benefit from a DSCR loan that focuses primarily on rental income instead of traditional personal income calculations.
The key is matching the mortgage program to the investment strategy—not forcing every investment into the same financing structure.
Five Types of Investment Property Loans
1. Conventional Investment Property Loans
Conventional mortgages are often an attractive starting point for investors with strong credit, documented income, and manageable existing debt.
These loans are typically used for eligible 1–4-unit residential investment properties.
Potential advantages:
·Competitive long-term fixed-rate options
·Familiar underwriting standards
·Financing for single-family homes and small multifamily properties
·Potentially lower borrowing costs than certain non-QM programs
Important considerations:
Conventional investment property loans generally require larger down payments than owner-occupied mortgages.
A 15% down payment may be available on certain eligible one-unit investment purchases, while other property types and loan scenarios may require 20%–25% or more.
Lenders also evaluate credit scores, debt-to-income ratios, cash reserves, existing financed properties, and rental income documentation.
Conventional financing can be especially useful for investors early in their portfolio-building journey.
2. DSCR Loans: Qualify Using Rental Income
One of the most useful financing tools for real estate investors is the Debt Service Coverage Ratio (DSCR) loan.
Instead of relying primarily on personal W-2 income or tax returns, many DSCR programs focus on the rental property's income relative to its required debt payments.
The basic formula is:
\[ \text{DSCR}=\frac{\text{Qualifying Rental Income}}{\text{Qualifying Debt Payments}} \]
For many residential DSCR loan programs, qualifying debt payments include principal, interest, property taxes, insurance, and applicable association dues.
Example:
Property financials | Monthly amount |
Qualifying rental income | $3,000 |
Principal and interest | $1,800 |
Property taxes and insurance | $600 |
Total qualifying payment | $2,400 |
DSCR | 1.25 |
A DSCR of 1.25 means the property's qualifying rental income is 125% of the qualifying monthly debt payment.
Some lenders prefer ratios of 1.15–1.25 or higher, although program requirements vary. Certain programs permit ratios below 1.0 with additional restrictions or pricing adjustments.
Why investors like DSCR loans:
·Less dependence on traditional personal income documentation
·Potentially useful for self-employed investors
·Financing designed specifically for rental properties
·May accommodate investors with multiple financed properties
·Certain programs allow entity ownership, subject to lender requirements
However, DSCR loans can carry higher interest rates, prepayment penalties, or larger down payment requirements than conventional loans.
3. Bank Statement Loans for Self-Employed Investors
Traditional mortgage underwriting can be challenging for business owners and self-employed investors.
Business deductions may reduce taxable income, making it difficult to qualify using tax returns alone.
Bank statement loan programs may allow qualifying income to be calculated using eligible personal or business deposits.
Depending on the lender, documentation may include 12–24 months of bank statements, business information, and supporting financial records.
These programs can be especially useful for entrepreneurs, independent contractors, consultants, and business owners.
However, not every bank deposit qualifies as income, and lenders may apply expense factors to business deposits.
4. Portfolio Loans
Portfolio lenders may retain loans on their own balance sheets rather than sell them into the conventional secondary mortgage market.
This can allow greater underwriting flexibility for certain borrowers and property types.
Portfolio loans may help investors who have multiple rental properties, complex financial structures, or financing needs that do not fit standard agency guidelines.
Some lenders also offer blanket financing, allowing multiple investment properties to be financed under one loan.
Terms vary significantly and may include adjustable rates, balloon payments, or different amortization schedules.
5. Fix-and-Flip and Bridge Loans
Not every investment property is ready for a traditional long-term mortgage.
Properties requiring substantial renovations may need short-term acquisition and rehabilitation financing.
Fix-and-flip or bridge loans may provide funds for purchasing, renovating, and repositioning a property.
These loans frequently feature shorter terms, higher borrowing costs, and more restrictive exit requirements.
Investors should establish a realistic plan for selling or refinancing before accepting short-term financing.
How Much Down Payment Do You Need for an Investment Property?
The required down payment depends on the mortgage program, property type, credit profile, and lender.
Loan program | Illustrative down payment |
Conventional, eligible one-unit rental | 15%–25% |
Conventional, 2–4-unit investment property | Often 25% |
DSCR investment loan | Commonly 20%–25%+ |
Bank statement investment loan | Often 20%–30% |
Portfolio investment loan | Lender-specific |
Fix-and-flip financing | Based on cost, value, experience, and lender |
These are illustrative ranges, not guaranteed loan terms. Certain programs and transactions require more equity.
Example: Purchasing a $350,000 Rental Property
Investment property down payment
20%
15%
20%
25%
30%
Down payment
$70,000
Loan amount
$280,000
Illustrative purchase financing only. Closing costs, reserves, lender fees, and other expenses are additional.
The down payment is only one component of your cash requirement.
Investors should also budget for appraisal fees, closing costs, inspections, property repairs, insurance, and post-closing liquidity.
Credit Score Requirements for Investment Property Loans
Your credit score affects both loan eligibility and pricing.
Generally, stronger credit may help you obtain more favorable interest rates, lower fees, and additional financing options.
Conventional loans are subject to current agency and lender underwriting standards. DSCR and non-QM lenders often establish their own minimum credit requirements, frequently starting around the low-to-mid 600s, although some programs require higher scores.
A borrower with a 740 credit score may receive materially different pricing from someone with a 660 score, even when both qualify.
Investor tip: Review your credit before submitting offers, particularly if you are carrying high credit card balances or planning multiple property acquisitions.
How Lenders Calculate Rental Income
Rental income is one of the most important variables in investment property financing.
However, different loan programs calculate qualifying rental income differently.
Conventional lenders may use lease agreements or appraisal-supported market rents, applying agency-prescribed adjustments such as a 75% rental income factor in applicable circumstances.
DSCR lenders may use actual lease income, appraiser-supported market rent, or another program-defined rental income measure.
For short-term rentals, some specialized programs consider historical revenue or approved rental income projections, often with additional restrictions.
A property generating $3,000 per month in gross rent will not necessarily contribute $3,000 toward mortgage qualification under every program.
Understanding the lender's calculation method before making an offer helps prevent financing surprises.
Investment Property Cash Flow: What Investors Must Calculate
Qualifying for a mortgage does not automatically mean a property is a good investment.
Investors should evaluate the complete operating economics.
Important expenses include property taxes, insurance, maintenance, vacancies, property management, utilities, association fees, and capital improvements.
Real-World Example: A $300,000 Rental Property
Assume an investor purchases a single-family rental property for $300,000 with a 25% down payment.
The investor finances $225,000 using an illustrative 30-year fixed mortgage at 7.50%.
Illustrative monthly rental analysis
Monthly rent | $2,500 |
Mortgage principal and interest | −$1,573 |
Property taxes and insurance | −$450 |
Maintenance reserve | −$125 |
Vacancy allowance | −$125 |
Property management | −$200 |
Estimated monthly cash flow | $27 |
Rounded illustrative figures. Excludes additional capital expenditures, leasing costs, utilities, HOA dues, and other potential expenses. The 7.50% rate is a hypothetical assumption, not a current rate quote.
Although this property generates $2,500 in monthly rent, the projected cash flow is only about $27 per month before additional expenses.
That is a very thin margin.
A single major repair or extended vacancy could eliminate months of projected profits.
This example demonstrates why cash flow analysis is just as important as mortgage qualification.
DSCR Loans vs. Conventional Loans: Which Is Better?
Feature | Conventional loan | DSCR loan |
Primary qualification | Personal income and debt | Property rental income |
Tax returns | Often required | Often not required for personal income |
Rates | Often lower | Often higher |
Down payment | Program-dependent | Commonly 20%–25%+ |
Investor portfolio growth | Subject to agency limits | May offer greater flexibility |
Prepayment penalties | Generally not permitted on covered consumer mortgages | May apply to business-purpose loans |
Best suited for | Investors with qualifying personal income | Investors emphasizing property cash flow |
Neither option is universally better.
An investor with strong W-2 income purchasing a first rental may benefit from conventional financing.
An investor who owns multiple properties or has complex self-employment income may find DSCR financing more practical.
The optimal solution depends on total borrowing costs, qualifying income, cash flow, property performance, and long-term goals.
Can You Buy a Multifamily Investment Property?
Yes.
Investors can purchase duplexes, triplexes, and fourplexes using eligible residential investment property financing.
Properties containing five or more residential units generally require commercial multifamily financing.
There is also an important distinction between investment properties and owner-occupied multifamily properties.
For example, a qualifying buyer who intends to live in one unit of a duplex may be eligible for an owner-occupied mortgage with a lower down payment than a non-owner-occupied investor loan.
FHA financing may allow eligible owner-occupants to purchase 2–4-unit properties with a minimum 3.5% down payment, subject to FHA requirements, including applicable self-sufficiency rules for three- and four-unit properties.
FHA financing is not intended for purchasing a purely non-owner-occupied rental property.
Five Mistakes Investors Should Avoid
1. Focusing only on the interest rate. Compare points, lender fees, prepayment provisions, loan terms, and total borrowing costs.
2. Underestimating property taxes and insurance. Texas investors should pay particular attention to potential reassessment and insurance costs.
3. Ignoring reserves. Vacancies, maintenance, and unexpected repairs can quickly consume projected profits.
4. Choosing short-term financing without an exit strategy. Refinancing is not guaranteed, particularly if property values, interest rates, or rental income change.
5. Waiting until after signing a purchase contract to discuss financing. Early lender evaluation can help identify issues with property condition, rental income, loan structure, or borrower qualifications.
How to Get Approved for an Investment Property Loan
Before making an offer, investors should organize their financial information and review the financing structure with a mortgage professional.
Depending on the loan program, lenders may request:
·Credit authorization and identification
·Income documentation or bank statements
·Current mortgage statements
·Asset statements and available down payment funds
·Existing rental property information
·Lease agreements or projected market rents
·Property purchase contract
·Appraisal and insurance information
DSCR loans may require less personal income documentation, but lenders still evaluate credit, assets, property condition, and program eligibility.
The earlier you understand the requirements, the better positioned you are to negotiate and close.
Why Work With Medallion Funds?
Investment property financing becomes more complicated as your portfolio grows.
At Medallion Funds, we help investors compare mortgage structures and evaluate financing strategies based on their goals.
Whether you're purchasing your first rental home, expanding into small multifamily properties, or evaluating a DSCR refinance, our objective is to help you understand the options before committing to a loan.
As a mortgage broker and commercial real estate professional, I bring both financing knowledge and an investment-oriented perspective to these conversations.
Bill Rapp
Partner & Director of Capital Advisory | Medallion Funds
Commercial Lending Nationwide
Residential Lending in AL, CA, CO, NV & TXBottom of Form
📞 Call or Text: 281-222-0433
🌐 Website: https://billrapponline.com
🎥 Subscribe to Mortgage Viking: https://www.youtube.com/@billrapp-medallion-funds
https://www.billrapponline.com/
https://findamortgagebroker.com/Profile/WilliamRappJr28883
https://billrapp.commloan.com/
https://billrapponline.com/financingfuturescre-houston-katy
https://houstoncommercialmortgage.com/
https://author.billrapponline.com
https://doctorvideo.billrapponline.com/
https://veteransvideo.billrapponline.com/
https://mortgageviking.billrapponline.com/
https://fha203h.billrapponline.com/
https://renovationvideo.billrapponline.com
https://medallionfunds.com/bill-rapp/
https://www.amazon.com/dp/B0F32Z5BH2
https://veed.cello.so/FOmzTty6oi9
https://buymeacoffee.com/vikingente3
https://creplaybookseries.billrapponline.com
https://creplaybook.billrapponline.com/
© Bill Rapp, Medallion Funds LLC, Director of Capital Advisory
10 Tips for First-Time Homebuyers
Buying your first home can be both exciting and nerve-wracking at the same time. With so many things to consider and....
How To Choose the Right Lender for You
Lorem Ipsum is simply dummy text of the printing and typesetting industry. Lorem Ipsum has been the industry's standard dummy
Refinancing youe loan and when to do it
Lorem Ipsum is simply dummy text of the printing and typesetting industry. Lorem Ipsum has been the industry's standard dummy
Copyright ©2021 | Mortgage Viking Team
Licensed to Do Business | NMLS # 228246
This is not an offer to enter into an agreement. Not all customers will qualify. Information, rates and programs are subject to change without notice. All products are subject to credit and property approval. Other restrictions and limitations may apply. Copyright © 2021 | Medallion Funds
Corporate | NMLS ID NMLS # 1825831
Corporate Address : 2651 N. Green Valley Pkwy STE. 101 Henderson, NV 89014
Corporate NMLS NMLS # 1825831 | Company Website: https://medallionfunds.com/bill-rapp/
Copyright ©2021 | Mortgage Viking Team Licensed to Do Business | NMLS # 228246
This is not an offer to enter into an agreement. Not all customers will qualify. Information, rates and programs are subject to change without notice. All products are subject to credit and property approval. Other restrictions and limitations may apply
Corporate | NMLS ID NMLS # 1825831
Corporate Address : 2651 N. Green Valley Pkwy STE. 101 Henderson, NV 89014 https://medallionfunds.com/bill-rapp/
Facebook
Instagram
X
LinkedIn
Youtube
TikTok