Low Rates.
Our rates are low, our application is quick and easy! We can get you clear to close in as little as 10 days!
Trusted By Agents With
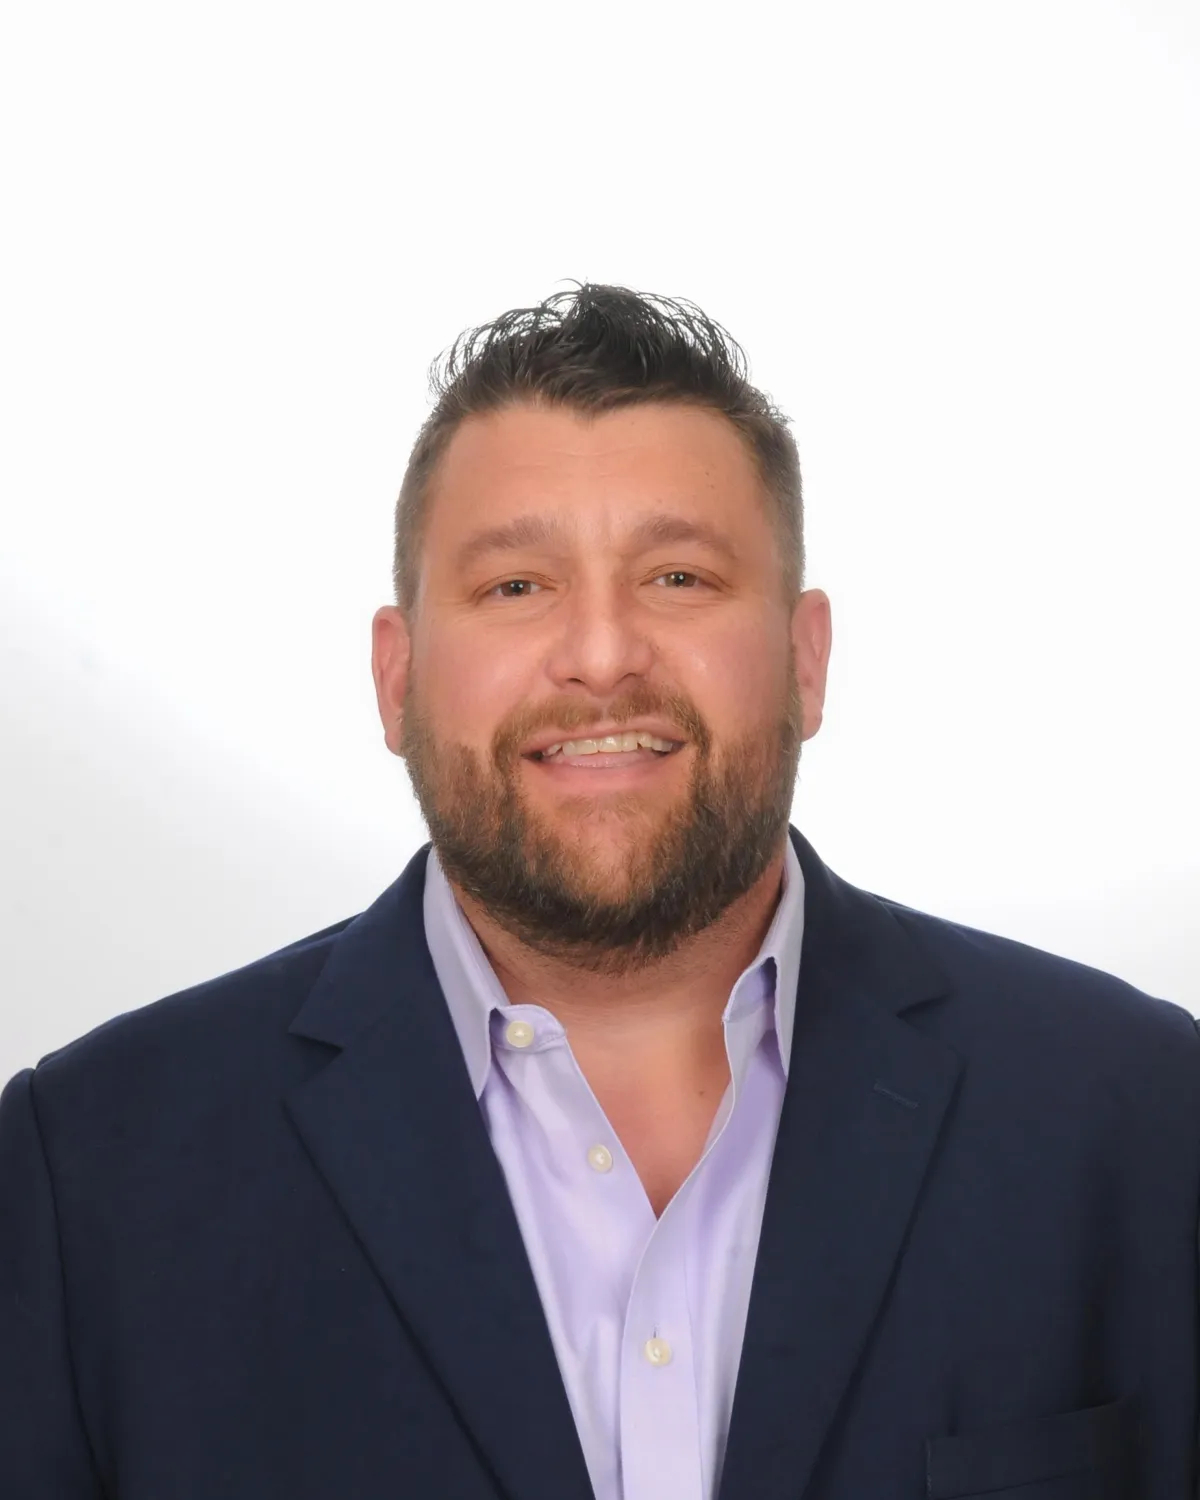
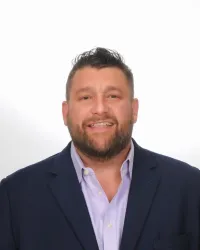
Meet Bill Rapp
NMLS ID # NMLS # 228246
Bill Rapp, CCIM is a Houston-based Capital Advisor at Medallion Funds, specializing in commercial real estate finance and strategic lending solutions. With over two decades of experience across brokerage and capital markets, Bill has worked with leading firms including eXp Commercial, NEXA Mortgage, Viking Enterprise LLC, and Sun Realty Houston.
A graduate of Texas A&M University with a BBA in Finance, Bill brings a disciplined, underwriting-first approach to every deal. His expertise spans commercial and residential financing, including asset-based lending, FHA financing, reverse mortgages, REO properties, and investment strategies for both single-family and commercial assets.
Known for his focus on structure over rate, Bill helps investors, business owners, and developers navigate complex transactions with clarity, precision, and a long-term wealth-building mindset.
The Client Experience
Great experience purchasing our first home! Bill was easy to reach and always able to answer any questions or concerns.

Loan Programs Available
Blogs
The Top 5 Mortgage Mistakes to Avoid
Buying your first home can be both exciting and nerve-wracking at the same time. With so many things to consider and....
Mortgage Do and
Do not list
Mortgages can be tricky, and it's easy to make mistakes that can end up costing you dearly. That's why we've put together this list....
Tips On How To Improve Your Credit Score
Let's talk about some ways you can improve your credit score! Your credit score is actually a big deal, and it can affect...
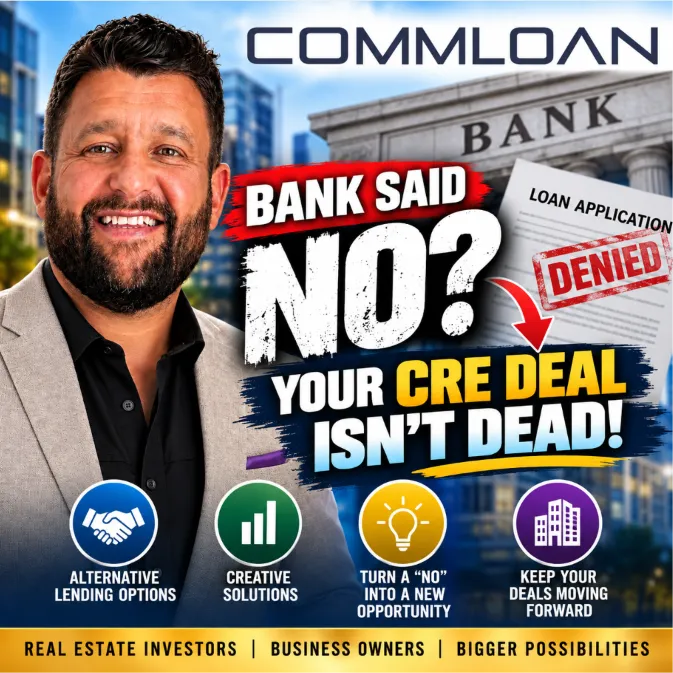
🏦 How to Win CRE Financing Business From Banks That Say No: Turn Declined Loans Into Opportunities 🚀
🏦 How to Win CRE Financing Business From Banks That Say No: Turn Declined Loans Into Opportunities 🚀
💰 Bank Declined Your Commercial Real Estate Loan? How Alternative CRE Financing Can Save the Deal 🔑
________________________________________________________________________________
How to Win CRE Financing Business From Banks That Say No
A commercial bank declining a real estate loan does not necessarily mean the transaction is a bad deal. Sometimes, it simply means the financing request does not fit that particular bank's lending guidelines.
For commercial real estate investors, business owners, and mortgage professionals, understanding this distinction can create significant opportunities.
Every day, banks decline commercial real estate financing requests because of loan-to-value restrictions, debt service coverage requirements, property conditions, concentration limits, or internal credit policies.
But here's the important point:
A bank's inability to approve a commercial loan does not automatically mean another lender cannot finance the transaction.
This is where commercial mortgage brokers, capital advisors, and alternative lending platforms can provide substantial value.
Through the CommLoan Empower Program, commercial real estate financing professionals can evaluate opportunities across a broad lender marketplace and help borrowers explore financing structures that traditional banks may not offer.
Why Banks Decline Commercial Real Estate Loans
Before pursuing alternative commercial real estate financing, it is essential to understand why the original lender declined the request.
1. Debt Service Coverage Ratio (DSCR) Is Too Low
Banks typically require sufficient property cash flow to support the proposed debt payments.
For example, a lender requiring a 1.25x DSCR wants the property's qualifying net operating income to cover annual debt service by at least 125%.
Consider a property generating $150,000 in annual NOI.
At a 1.25x minimum DSCR:
$150,000 ÷ 1.25 = $120,000
The property's maximum annual debt service under that requirement would be $120,000.
If the requested loan requires $140,000 in annual payments, the bank may decline the transaction or reduce the loan amount.
An alternative lender may evaluate the transaction differently, particularly when the property has a credible business plan, improving occupancy, or significant equity.
However, alternative financing does not eliminate the need for a realistic repayment strategy.
2. The Property Does Not Meet Occupancy Requirements
Many banks prefer stabilized commercial properties with predictable income.
Properties with significant vacancy can create challenges, including:
·Insufficient current cash flow
·Uncertainty regarding future lease-up
·Increased operating expenses
·Tenant rollover exposure
·Difficulty establishing sustainable property value
For example, a 60%-occupied multifamily property may not qualify for conventional permanent financing.
However, a bridge lender may consider the transaction when the borrower has adequate liquidity, a realistic renovation and lease-up strategy, and a credible refinancing or sale exit.
The opportunity is not simply finding a lender willing to accept vacancy. It is matching the property's business plan with the appropriate capital structure.
3. The Bank Has Reached Its Lending Concentration Limits
Commercial banks manage exposure across geographic markets, property types, industries, and individual borrowers.
A bank may have reached its internal lending limit for multifamily, hospitality, office, or construction financing.
In these situations, the loan may be financially sound, but the bank cannot add more exposure within that category.
This creates a potential referral opportunity for commercial mortgage professionals who have access to lenders with different portfolio objectives.
4. The Borrower Does Not Meet Traditional Underwriting Requirements
Traditional lenders may evaluate borrowers based on personal credit, liquidity, net worth, global cash flow, and historical operating performance.
Challenges can arise when borrowers have:
·Complex ownership structures
·Limited operating history
·Recent business acquisitions
·Nontraditional income sources
·High existing leverage
·Significant but illiquid assets
Some private credit, debt fund, and other specialized lenders may emphasize property-level collateral, sponsorship, and the business plan differently.
Nevertheless, borrower creditworthiness, liquidity, and repayment capacity remain important.
5. The Loan Request Does Not Fit the Bank's Product Offering
Not every lender finances every property type or transaction structure.
A bank focused on stabilized commercial properties may not offer financing for heavy renovations, ground-up construction, transitional assets, or short-term bridge transactions.
A financing request can be declined because the bank lacks the appropriate product rather than because the underlying transaction is inherently unfinanceable.
The Opportunity: Turn Bank Declines Into Commercial Financing Referrals
For commercial mortgage brokers and capital advisors, declined bank loans can represent a valuable source of business.
Banks frequently encounter borrowers they would like to help but cannot accommodate under their current credit policies.
Instead of losing the relationship entirely, a banker may be able to introduce the borrower to a qualified financing professional, subject to the bank's policies and the borrower's authorization.
A successful referral relationship should create value for three parties.
Participant | Potential benefit |
Bank relationship manager | Helps the customer explore another financing path |
Commercial mortgage broker | Gains an opportunity to structure and place a loan |
Borrower | Receives access to additional financing alternatives |
The most productive relationships are built around solving financing problems, protecting borrower confidentiality, and maintaining professional trust.
Five Strategies for Winning CRE Financing Referrals From Banks
Strategy 1: Build Relationships With Commercial Bankers
Develop relationships with commercial loan officers, business bankers, credit officers, and relationship managers.
Focus on institutions serving commercial real estate investors and business owners.
Instead of simply asking for referrals, explain the types of financing challenges you can help evaluate.
For example:
A banker may be unable to finance a partially occupied retail property because it does not meet the bank's stabilization requirements.
A commercial mortgage advisor could evaluate whether a bridge loan provides a feasible path toward lease-up and eventual permanent financing.
The goal is to become a trusted resource for transactions that fall outside the bank's lending appetite.
Strategy 2: Understand the Reason for the Decline
Not all declined loans are equally attractive opportunities.
Before approaching another lender, identify the underlying issue.
Was the request declined because of DSCR, LTV, borrower credit, property condition, concentration limits, or the loan's intended use?
The answer determines which lender categories may be appropriate.
For example, a loan declined because of bank concentration limits may be a stronger conventional lending candidate than a loan declined because the property cannot generate sufficient cash flow under reasonable assumptions.
Strategy 3: Develop Expertise in Alternative CRE Financing
Commercial mortgage professionals should understand multiple lending structures.
These may include:
·Bridge loans
·Private credit and debt fund financing
·SBA 7(a) and 504 loans for eligible businesses
·Commercial construction financing
·Multifamily financing
·CMBS loans
·Agency multifamily programs
·Owner-occupied commercial real estate loans
·Portfolio lending
·Specialized property financing
Each program has different underwriting requirements, documentation standards, pricing, and exit considerations.
The ability to identify an appropriate financing structure is more valuable than simply presenting a long list of lenders.
Strategy 4: Build a Complete Financing Package
A declined loan is not necessarily improved by submitting the same incomplete package to additional lenders.
A professional financing package should generally include the property description, current rent roll, trailing operating statements, borrower financial information, sources and uses, business plan, requested loan structure, and proposed repayment or exit strategy.
The precise documentation depends on the transaction.
A strong package helps lenders evaluate the opportunity efficiently and can reduce unnecessary back-and-forth.
Strategy 5: Protect the Bank's Relationship With the Borrower
One of the biggest concerns bankers may have when making outside referrals is losing their customers.
Commercial mortgage professionals can address this concern by establishing clear expectations.
When appropriate, explain that the objective is to solve the immediate financing challenge, not solicit unrelated banking relationships.
For example, a borrower might obtain a short-term bridge loan while continuing to maintain deposits, treasury services, or other relationships with the referring bank.
Future permanent financing could potentially return to the bank once the property qualifies, subject to lender approval.
How the CommLoan Empower Program Helps Evaluate Financing Alternatives
The CommLoan Empower Program provides commercial real estate financing professionals access to technology and a broad network of lending relationships.
Through CommLoan's CUPID™ platform, advisors can evaluate commercial financing opportunities across a marketplace of more than 700 lenders.
The platform supports a more structured approach to evaluating potential financing solutions.
Rather than relying exclusively on one bank's credit box, advisors can compare potential financing options across multiple lending categories.
This can be particularly useful for borrowers whose transactions involve transitional properties, unusual financing structures, or specialized commercial assets.
The objective is not to guarantee financing. It is to improve lender alignment, evaluate realistic options, and help borrowers make informed capital decisions.
Example: When a Bank Decline Becomes a Financing Opportunity
Consider a hypothetical commercial real estate investor purchasing a partially occupied retail center.
Illustrative transaction
Purchase price
$2,000,000
Requested loan
$1,400,000
Current occupancy
65%
Target occupancy
90%
The borrower's bank declines the request because current property cash flow does not meet its minimum DSCR requirement.
A commercial mortgage advisor reviews the transaction and determines that a bridge lender might consider the property if the borrower can demonstrate sufficient equity, liquidity, leasing demand, and a viable stabilization plan.
The financing strategy could include a short-term bridge loan, funding for eligible property improvements, a structured lease-up period, and a potential refinance into permanent debt once the property meets underwriting requirements.
This strategy may involve higher financing costs, shorter maturities, and greater execution risk than conventional bank financing.
The borrower must evaluate whether the anticipated improvements justify those risks.
The lesson: A decline from one lender may identify a financing mismatch rather than the end of the transaction.
How Borrowers Should Respond When Their Bank Says No
If your bank declines a commercial real estate loan, avoid immediately submitting the same application to numerous lenders.
Instead, request a clear explanation of the decline, confirm whether the issue can be resolved, and reassess the transaction's cash flow, leverage, collateral, and repayment strategy.
Then work with a qualified commercial mortgage advisor who understands which lenders may be appropriate for the specific transaction.
Sometimes the solution is a different lender. Other times, it requires additional equity, a smaller loan, improved operating performance, or a revised business plan.
And in some situations, the prudent decision is not to proceed.
Frequently Asked Questions
Can I get a commercial real estate loan after my bank declines me?
Possibly. Another lender may have different underwriting guidelines, property preferences, or loan products. Approval depends on the transaction's financial strength and lender requirements.
Are alternative commercial loans more expensive?
They can be. Bridge loans and private credit often carry higher rates, fees, and shorter terms than conventional bank financing. Borrowers should compare total financing costs and exit risks.
Can a commercial mortgage broker help with low-occupancy properties?
Yes. A broker can assess whether bridge, transitional, or value-add financing may be available. Lenders generally expect a credible stabilization strategy and sufficient borrower resources.
Can banks refer declined loans to commercial mortgage brokers?
They may, subject to institutional policies, applicable law, borrower consent, and conflict-of-interest requirements. Referral arrangements and compensation must comply with applicable rules.
What is the biggest mistake after a commercial loan decline?
Assuming that every lender will evaluate the request the same way—or that another lender can overcome a fundamentally unworkable transaction without changing its structure.
Final Thoughts: A Bank's No May Be the Beginning of a Better Financing Strategy
Commercial real estate financing is not a one-size-fits-all business.
Banks, credit unions, debt funds, private lenders, and government-supported lending programs serve different borrower needs.
For commercial real estate investors and business owners, a declined bank loan may create an opportunity to reassess the financing strategy.
For commercial mortgage professionals, developing trusted banking relationships and understanding alternative financing structures can create a valuable referral channel.
The key is identifying financeable transactions, matching them with suitable lenders, and providing borrowers with transparent guidance.
Work With Bill Rapp, CCIM — CommLoan Empower Program
If your bank declined a commercial real estate loan—or you are a banker with a transaction that falls outside your institution's guidelines—let's evaluate the available options.
Top of Form
Bottom of Form
Bill Rapp, CCIM
Director | CommLoan
📞 281-222-0433
📧 [email protected]
🌐 https://billrapp.commloan.com/
🌐 https://HoustonCommercialMortgage.com/
Commercial Real Estate Financing Nationwide
https://billrapp.commloan.com/
https://author.billrapponline.com/
https://www.amazon.com/dp/B0F32Z5BH2
https://veed.cello.so/FOmzTty6oi9
https://buymeacoffee.com/vikingente3
https://creplaybookseries.billrapponline.com
https://creplaybook.billrapponline.com/
©Bill Rapp, CCIM - Director - CommLoan
10 Tips for First-Time Homebuyers
Buying your first home can be both exciting and nerve-wracking at the same time. With so many things to consider and....
How To Choose the Right Lender for You
Lorem Ipsum is simply dummy text of the printing and typesetting industry. Lorem Ipsum has been the industry's standard dummy
Refinancing youe loan and when to do it
Lorem Ipsum is simply dummy text of the printing and typesetting industry. Lorem Ipsum has been the industry's standard dummy
Copyright ©2021 | Mortgage Viking Team
Licensed to Do Business | NMLS # 228246
This is not an offer to enter into an agreement. Not all customers will qualify. Information, rates and programs are subject to change without notice. All products are subject to credit and property approval. Other restrictions and limitations may apply. Copyright © 2021 | Medallion Funds
Corporate | NMLS ID NMLS # 1825831
Corporate Address : 2651 N. Green Valley Pkwy STE. 101 Henderson, NV 89014
Corporate NMLS NMLS # 1825831 | Company Website: https://medallionfunds.com/bill-rapp/
Copyright ©2021 | Mortgage Viking Team Licensed to Do Business | NMLS # 228246
This is not an offer to enter into an agreement. Not all customers will qualify. Information, rates and programs are subject to change without notice. All products are subject to credit and property approval. Other restrictions and limitations may apply
Corporate | NMLS ID NMLS # 1825831
Corporate Address : 2651 N. Green Valley Pkwy STE. 101 Henderson, NV 89014 https://medallionfunds.com/bill-rapp/
Facebook
Instagram
X
LinkedIn
Youtube
TikTok