Low Rates.
Our rates are low, our application is quick and easy! We can get you clear to close in as little as 10 days!
Trusted By Agents With
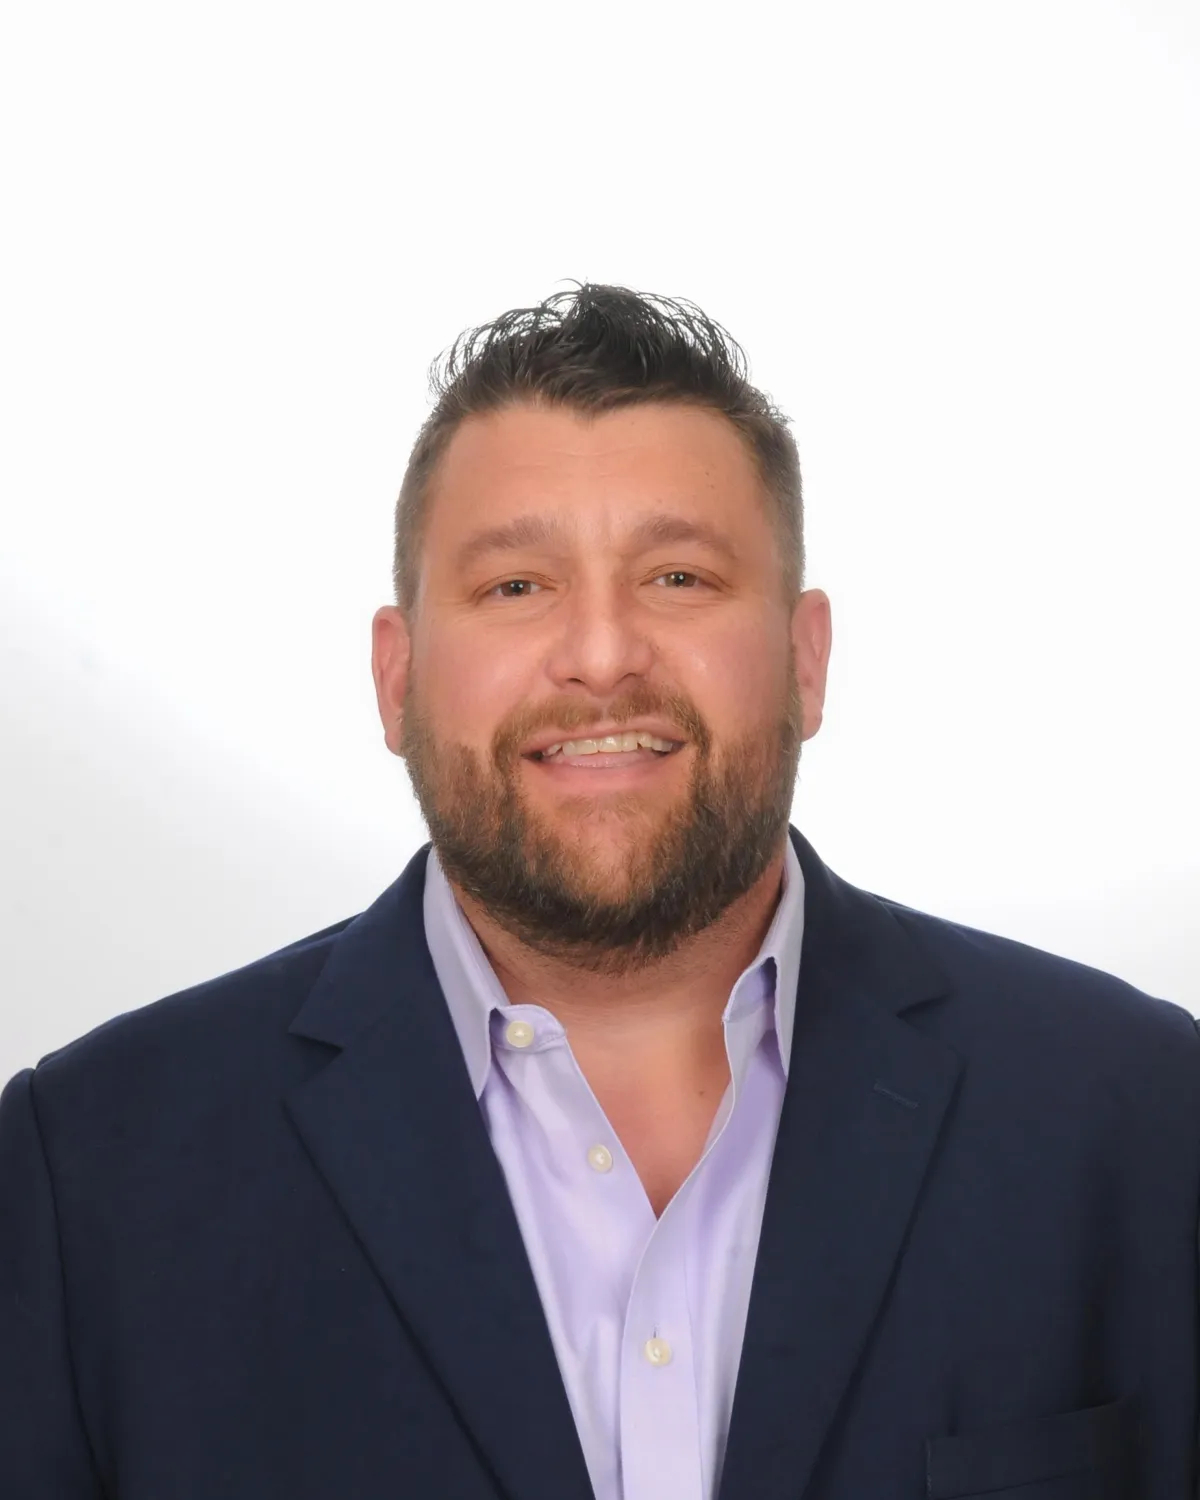
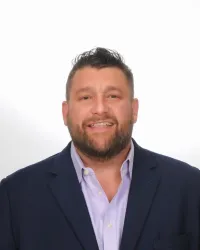
Meet Bill Rapp
NMLS ID # NMLS # 228246
Bill Rapp, CCIM is a Houston-based Capital Advisor at Medallion Funds, specializing in commercial real estate finance and strategic lending solutions. With over two decades of experience across brokerage and capital markets, Bill has worked with leading firms including eXp Commercial, NEXA Mortgage, Viking Enterprise LLC, and Sun Realty Houston.
A graduate of Texas A&M University with a BBA in Finance, Bill brings a disciplined, underwriting-first approach to every deal. His expertise spans commercial and residential financing, including asset-based lending, FHA financing, reverse mortgages, REO properties, and investment strategies for both single-family and commercial assets.
Known for his focus on structure over rate, Bill helps investors, business owners, and developers navigate complex transactions with clarity, precision, and a long-term wealth-building mindset.
The Client Experience
Great experience purchasing our first home! Bill was easy to reach and always able to answer any questions or concerns.

Loan Programs Available


Blogs
The Top 5 Mortgage Mistakes to Avoid
Buying your first home can be both exciting and nerve-wracking at the same time. With so many things to consider and....
Mortgage Do and
Do not list
Mortgages can be tricky, and it's easy to make mistakes that can end up costing you dearly. That's why we've put together this list....
Tips On How To Improve Your Credit Score
Let's talk about some ways you can improve your credit score! Your credit score is actually a big deal, and it can affect...
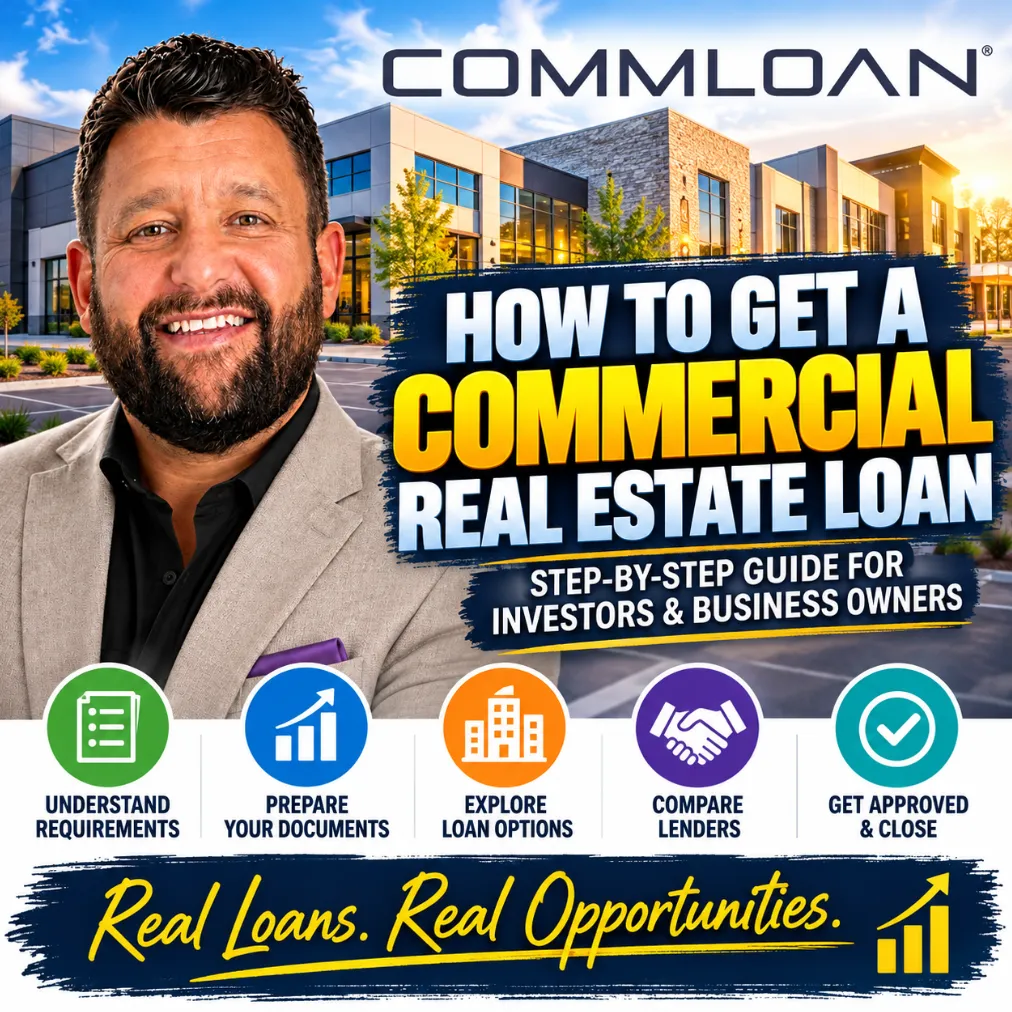
🏢 How to Get a Commercial Real Estate Loan: Step-by-Step Guide for Investors & Business Owners 💰
🏢 How to Get a Commercial Real Estate Loan: Step-by-Step Guide for Investors & Business Owners 💰
💵 Commercial Real Estate Loan Requirements: How to Qualify, Find the Right Lender & Secure Financing 🏦
________________________________________________________________________________
Primary keyword: How to Get a Commercial Real Estate Loan
How to Get a Commercial Real Estate Loan: A Step-by-Step Guide
Buying commercial real estate can be one of the most significant financial decisions an investor or business owner makes. Whether you're purchasing an apartment building, office property, retail center, industrial warehouse, or owner-occupied business location, securing the right financing is essential.
But commercial real estate financing works differently from residential mortgage lending.
Commercial lenders evaluate more than your credit score and down payment. They examine the property's income, debt service coverage, borrower experience, liquidity, financial strength, and overall transaction risk.
Understanding how to get a commercial real estate loan can help you avoid costly mistakes, improve your financing options, and negotiate more favorable loan terms.
At the CommLoan Empower Program, we help commercial real estate investors and business owners evaluate financing alternatives through a broad commercial lending marketplace.
Here's what you need to know before applying.
Step 1: Understand the Types of Commercial Real Estate Loans
The first step is identifying the financing program that fits your property, investment strategy, and financial objectives.
Conventional Commercial Real Estate Loans
Conventional commercial mortgages are commonly offered by banks, credit unions, and other commercial lenders.
These loans are frequently used to finance stabilized commercial properties, including office buildings, retail centers, industrial facilities, and multifamily investments.
Typical characteristics may include:
·Loan-to-value ratios around 65%–80%, depending on the lender and property.
·Fixed or floating interest rates.
·Amortization periods commonly ranging from 15–30 years.
·Loan maturities that may be shorter than the amortization schedule.
·Full, partial, or nonrecourse structures, depending on the transaction.
SBA 7(a) and SBA 504 Loans
Small Business Administration loan programs can provide attractive financing for eligible owner-occupied commercial properties.
SBA 7(a) financing can support qualifying real estate purchases, business acquisitions, equipment, and certain working capital needs.
SBA 504 financing primarily supports eligible long-term fixed assets, including commercial property acquisitions, construction, and major equipment.
Qualified borrowers may benefit from lower equity requirements than many conventional commercial mortgages.
SBA financing generally requires qualifying business occupancy and is not designed for passive real estate investment.
Commercial Bridge Loans
Bridge financing is often used when a property needs renovations, lease-up, repositioning, or stabilization before qualifying for permanent financing.
Bridge loans typically offer shorter terms and may carry higher interest rates and fees than stabilized permanent financing.
A clearly defined exit strategy is critical.
Multifamily and Agency Loans
Investors purchasing or refinancing qualifying apartment properties may have access to financing through banks, life insurance companies, debt funds, and agency lending programs.
Fannie Mae and Freddie Mac multifamily programs can provide attractive financing for eligible properties and sponsors.
Construction Loans
Construction financing supports ground-up development, major renovations, and redevelopment projects.
Lenders typically evaluate construction budgets, project feasibility, sponsor experience, guarantees, and the anticipated permanent financing or sale strategy.
Key takeaway: The best loan program depends on the property, borrower, and business plan—not simply the lowest advertised interest rate.
Step 2: Understand Commercial Loan Qualification Requirements
Commercial mortgage lenders generally evaluate several important underwriting factors.
Loan-to-Value Ratio (LTV)
LTV measures the proposed loan amount relative to the property's appraised value.
\[ \text{LTV}=\frac{\text{Loan Amount}}{\text{Property Value}}\times100 \]
For example, if a property is valued at $2,000,000 and the proposed loan is $1,400,000:
\[ \text{LTV}=70\% \]
For acquisitions, lenders may also apply purchase-price or lower-of-cost-or-value limitations.
Debt Service Coverage Ratio (DSCR)
DSCR measures the property's ability to cover its annual mortgage payments from net operating income.
\[ \text{DSCR}=\frac{\text{Net Operating Income}}{\text{Annual Debt Service}} \]
Suppose a commercial property generates $180,000 in annual NOI and requires $135,000 in annual debt service.
\[ \text{DSCR}=1.33x \]
This means the property generates approximately $1.33 in net operating income for every $1.00 of required debt service.
Many lenders target minimum DSCR levels around 1.20x–1.30x, although actual requirements vary by property type, loan product, and lender.
Debt Yield
Debt yield evaluates the property's NOI relative to the loan amount.
\[ \text{Debt Yield}=\frac{\text{NOI}}{\text{Loan Amount}}\times100 \]
For a property with $180,000 in NOI and a proposed $1,800,000 loan:
\[ \text{Debt Yield}=10\% \]
Debt yield helps lenders evaluate credit risk independently of interest rates and amortization.
Borrower Credit, Liquidity, and Net Worth
Commercial lenders may also consider personal credit, available liquidity, contingent liabilities, real estate ownership experience, and post-closing reserves.
A strong property does not automatically overcome a weak borrower profile.
Step 3: Determine Your Down Payment
One of the most common questions is:
How much money do I need down for a commercial real estate loan?
The answer depends on the property type, financing program, and transaction risk.
Financing type | Illustrative equity requirement |
Conventional commercial mortgage | 20%–35% |
SBA 7(a) real estate financing | Often 10% or more |
SBA 504 eligible project | Often 10%–20% |
Multifamily investment financing | 20%–35% |
Hotel financing | 25%–40% or more |
Bridge financing | Varies substantially |
These are general planning ranges, not guaranteed lender terms. SBA equity requirements depend on program rules and transaction characteristics.
Investors should also budget for appraisals, environmental assessments, legal fees, lender fees, reserves, and other closing expenses.
Step 4: Prepare Your Commercial Loan Documentation
One of the fastest ways to delay a commercial financing transaction is submitting an incomplete loan package.
Depending on the lender and transaction, commonly requested documents include:
·Purchase contract or letter of intent.
·Current rent roll and copies of leases.
·Trailing 12-month operating statement (T-12).
·Historical property financial statements.
·Personal financial statement.
·Personal and business tax returns, when required.
·Bank and investment account statements.
·Schedule of real estate owned.
·Business financial statements for owner-occupied properties.
·Property insurance information.
·Business plan, renovation budget, or construction projections when applicable.
A complete package helps lenders evaluate the transaction more efficiently and can reduce repeated document requests.
Step 5: Determine How Much Financing the Property Can Support
One of the biggest misconceptions in commercial real estate financing is that a lender's maximum advertised LTV automatically determines your loan amount.
It doesn't.
Lenders may size loans using several constraints, including LTV, DSCR, debt yield, and borrower financial strength.
Example: Commercial Loan Sizing
Illustrative investment property financing
Property value
$3,000,000
Annual NOI
$210,000
Maximum LTV
75%
Minimum DSCR
1.25x
Loan sizing constraints
LTV maximum
$2,250,000
DSCR maximum
$2,059,000
Estimated maximum loan
$2.06M
Assumes a 7.00% interest rate, 25-year amortization, annual debt service factor of approximately 8.48%, and no more restrictive debt-yield or other constraints. Illustration only.
Even though the lender permits 75% LTV, the property's income supports a smaller loan under the assumed DSCR requirement.
This is why underwriting the property before negotiating financing terms is so important.
Step 6: Compare Commercial Mortgage Lenders
Different commercial lenders have different credit policies, property preferences, and loan structures.
A bank might offer an attractive rate but require substantial recourse.
A debt fund might provide more flexible underwriting but charge higher financing costs.
An agency lender might offer attractive long-term financing for a qualifying multifamily property but impose specific prepayment provisions.
When comparing commercial loan offers, evaluate:
1.Interest rate and total borrowing cost.
2.Maximum loan proceeds.
3.Loan term and amortization.
4.Recourse and guarantee requirements.
5.Prepayment penalties and exit flexibility.
6.Reserve requirements and closing costs.
The cheapest quoted interest rate does not necessarily produce the best investment outcome.
Step 7: Get Prequalified Before Making an Offer
Commercial loan prequalification can help investors understand their potential financing capacity before entering into a purchase agreement.
An initial financing assessment may evaluate property value, anticipated NOI, down payment availability, borrower experience, and proposed loan structure.
Prequalification is not a commitment to lend. Final approval remains subject to underwriting, due diligence, and lender requirements.
Nevertheless, an informed financing strategy can improve negotiations and reduce execution risk.
Step 8: Complete Underwriting and Due Diligence
Once a lender is selected, the transaction moves through formal underwriting.
The process may involve:
·Third-party appraisal.
·Phase I environmental site assessment.
·Property condition assessment.
·Title and survey review.
·Lease and income verification.
·Borrower financial verification.
·Credit approval and legal documentation.
Additional requirements may apply to specialized property types such as hotels, healthcare facilities, restaurants, and construction projects.
Step 9: Review the Loan Terms Before Closing
Before signing commercial mortgage documents, understand the obligations you are accepting.
Pay particular attention to balloon maturities, personal guarantees, cash management provisions, reserve requirements, financial reporting covenants, and prepayment penalties.
Some commercial loans require yield maintenance, defeasance, or other prepayment arrangements that can materially affect the cost of refinancing or selling.
A financing structure should align with your anticipated ownership period and exit strategy.
Step 10: Work With a Commercial Capital Advisor
Commercial financing is not a one-size-fits-all process.
The right capital advisor can help investors understand lender requirements, structure a financeable transaction, evaluate competing loan offers, and identify potential issues before they become closing problems.
Through the CommLoan Empower Program, borrowers can explore financing opportunities through a commercial lending marketplace with access to more than 700 lenders.
Instead of assuming that one bank's credit policy represents the entire lending market, investors can evaluate financing alternatives based on the needs of their specific transaction.
Common Mistakes to Avoid When Applying for a Commercial Real Estate Loan
Several preventable mistakes can undermine an otherwise attractive transaction.
Mistake 1: Shopping exclusively for the lowest rate. Loan proceeds, recourse, prepayment flexibility, and maturity risk may matter just as much.
Mistake 2: Assuming maximum LTV equals available financing. DSCR and debt yield may produce a lower loan amount.
Mistake 3: Underestimating required equity. Closing expenses, reserves, and lender adjustments can increase the cash required.
Mistake 4: Providing incomplete financial documentation. Missing rent rolls, financial statements, and borrower information can delay underwriting.
Mistake 5: Ignoring the exit strategy. A short-term loan without a realistic refinance or sale plan can create significant risk.
Frequently Asked Questions About Commercial Real Estate Loans
What credit score do you need for a commercial real estate loan?
There is no universal minimum credit score. Some commercial lenders emphasize sponsor credit, while others place greater weight on property cash flow, collateral, and liquidity. SBA and bank programs may have specific credit standards.
Can I get a commercial real estate loan with 10% down?
Potentially. Certain qualifying SBA transactions may permit financing with approximately 10% borrower equity, while conventional investment property loans often require substantially more.
How long does it take to get a commercial real estate loan?
Straightforward transactions may close within approximately 30–60 days after a complete application, while complex, agency, SBA, construction, or specialized property transactions may take longer. Timelines vary considerably.
Can an LLC obtain a commercial real estate loan?
Yes. Many commercial real estate loans are originated to limited liability companies or other eligible borrowing entities. Lenders may still require personal guarantees or evaluate the financial strength of the principals.
Can I qualify without substantial commercial real estate experience?
Possibly. Lenders consider borrower experience alongside property performance, leverage, financial resources, and professional management. Requirements vary by lender and program.
Is it better to use a bank or commercial mortgage broker?
A bank offers its own financing programs, while a commercial mortgage broker or capital advisor can help evaluate alternatives across multiple lending sources. The best approach depends on your transaction and existing lending relationships.
Final Thoughts: Getting the Right Commercial Real Estate Loan
Getting a commercial real estate loan involves more than completing an application.
Successful borrowers understand their financing options, prepare complete financial documentation, evaluate the property's cash flow, and select financing that supports their investment strategy.
Whether you're acquiring your first commercial property, expanding your portfolio, refinancing an existing investment, or purchasing real estate for your business, the right financing structure can make a meaningful difference.
Ready to Explore Your Commercial Financing Options?
Bill Rapp, CCIM CommLoan Empower Program | Commercial Capital Advisor
Explore commercial financing alternatives and take the next step toward your investment objectives.
Explore Commercial Financing with Bill Rapp
Top of Form
Bottom of Form
Bill Rapp, CCIM
Director | CommLoan
📞 281-222-0433
📧 [email protected]
🌐 https://billrapp.commloan.com/
🌐 https://HoustonCommercialMortgage.com/
Commercial Real Estate Financing Nationwide
https://billrapp.commloan.com/
https://author.billrapponline.com/
https://www.amazon.com/dp/B0F32Z5BH2
https://veed.cello.so/FOmzTty6oi9
https://buymeacoffee.com/vikingente3
https://creplaybookseries.billrapponline.com
https://creplaybook.billrapponline.com/
©Bill Rapp, CCIM - Director - CommLoan
10 Tips for First-Time Homebuyers
Buying your first home can be both exciting and nerve-wracking at the same time. With so many things to consider and....
How To Choose the Right Lender for You
Lorem Ipsum is simply dummy text of the printing and typesetting industry. Lorem Ipsum has been the industry's standard dummy
Refinancing youe loan and when to do it
Lorem Ipsum is simply dummy text of the printing and typesetting industry. Lorem Ipsum has been the industry's standard dummy
Copyright ©2021 | Mortgage Viking Team
Licensed to Do Business | NMLS # 228246
This is not an offer to enter into an agreement. Not all customers will qualify. Information, rates and programs are subject to change without notice. All products are subject to credit and property approval. Other restrictions and limitations may apply. Copyright © 2021 | Medallion Funds
Corporate | NMLS ID NMLS # 1825831
Corporate Address : 2651 N. Green Valley Pkwy STE. 101 Henderson, NV 89014
Corporate NMLS NMLS # 1825831 | Company Website: https://medallionfunds.com/bill-rapp/
Copyright ©2021 | Mortgage Viking Team Licensed to Do Business | NMLS # 228246
This is not an offer to enter into an agreement. Not all customers will qualify. Information, rates and programs are subject to change without notice. All products are subject to credit and property approval. Other restrictions and limitations may apply
Corporate | NMLS ID NMLS # 1825831
Corporate Address : 2651 N. Green Valley Pkwy STE. 101 Henderson, NV 89014 https://medallionfunds.com/bill-rapp/
Facebook
Instagram
X
LinkedIn
Youtube
TikTok