Low Rates.
Our rates are low, our application is quick and easy! We can get you clear to close in as little as 10 days!
Trusted By Agents With
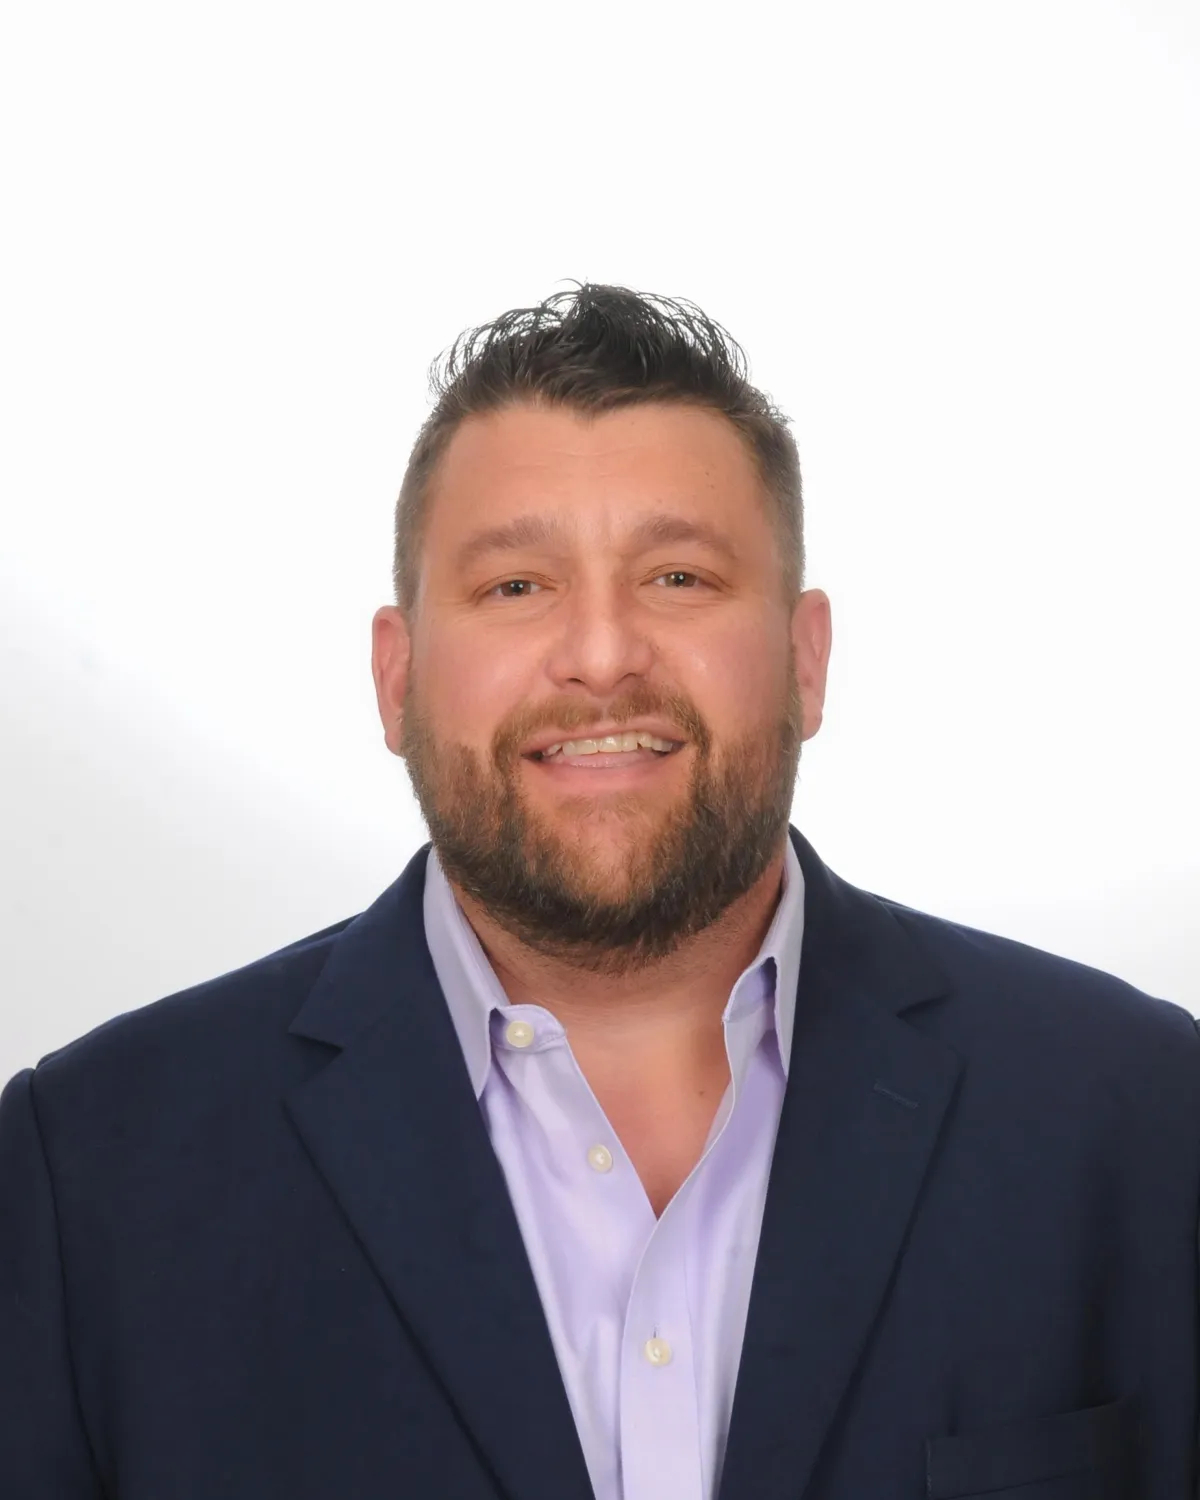
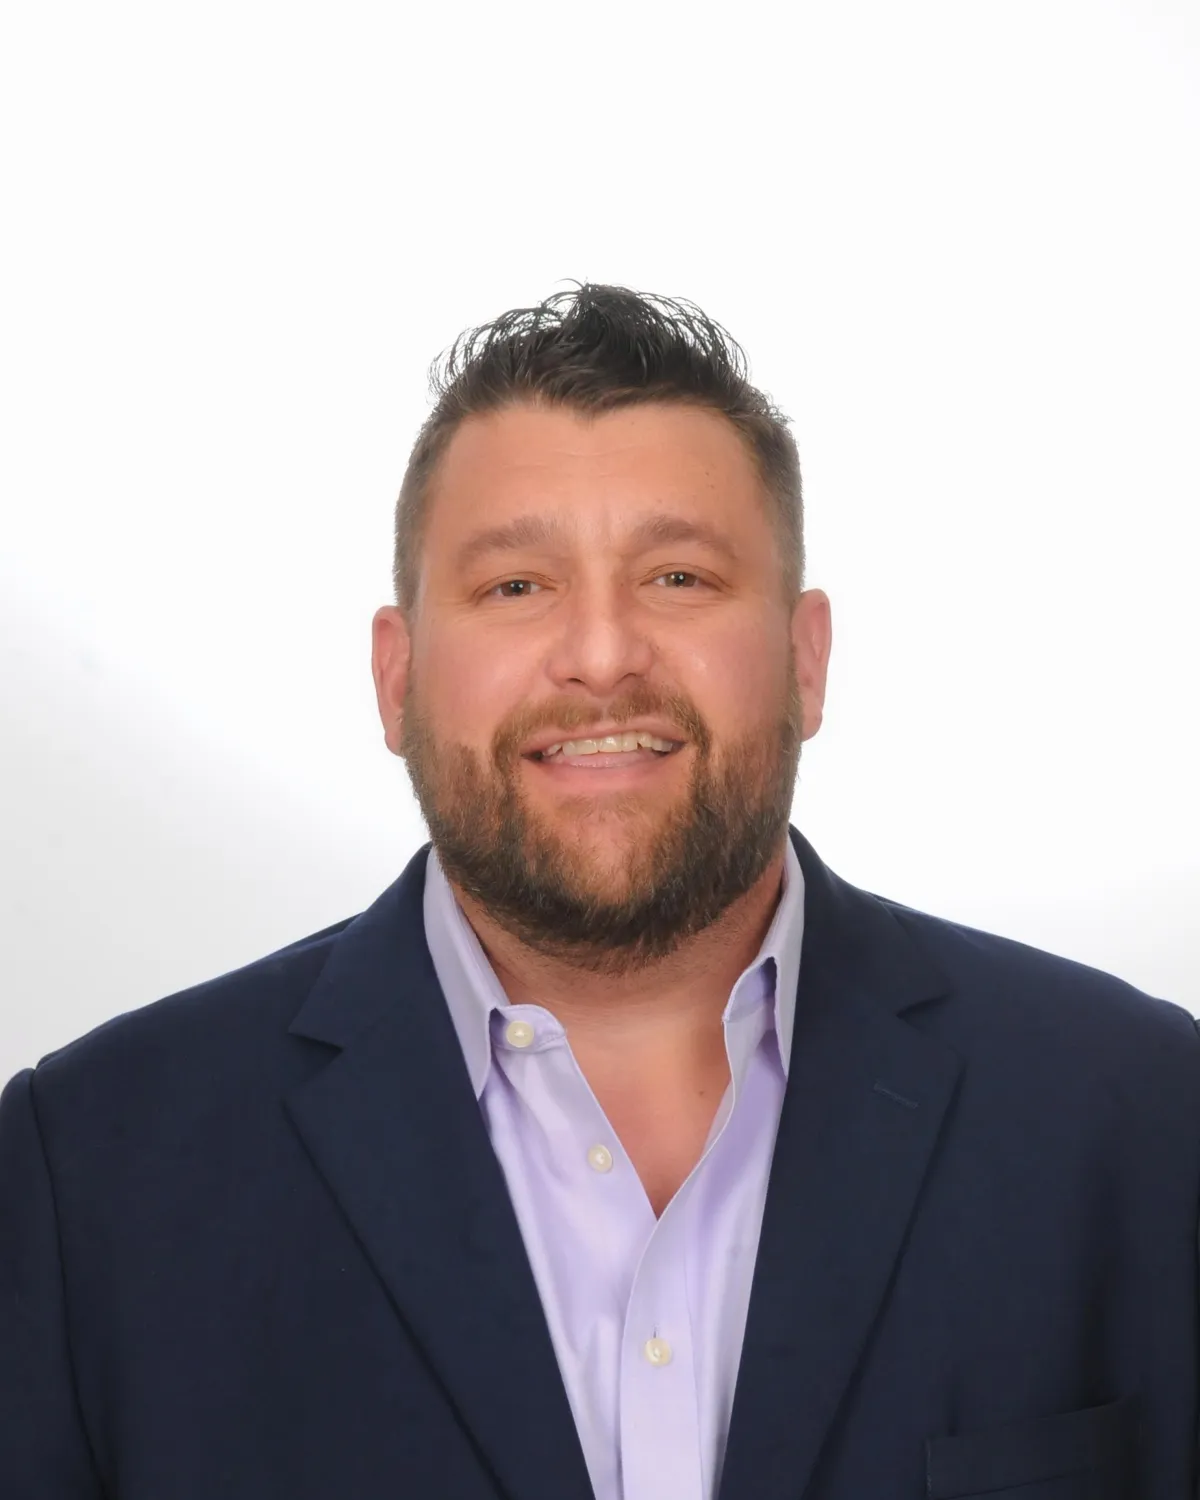
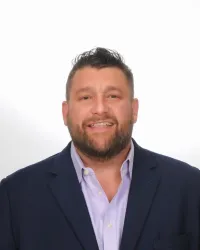
Meet Bill Rapp
NMLS ID # NMLS # 228246
Bill Rapp, CCIM is a Houston-based Capital Advisor at Medallion Funds, specializing in commercial real estate finance and strategic lending solutions. With over two decades of experience across brokerage and capital markets, Bill has worked with leading firms including eXp Commercial, NEXA Mortgage, Viking Enterprise LLC, and Sun Realty Houston.
A graduate of Texas A&M University with a BBA in Finance, Bill brings a disciplined, underwriting-first approach to every deal. His expertise spans commercial and residential financing, including asset-based lending, FHA financing, reverse mortgages, REO properties, and investment strategies for both single-family and commercial assets.
Known for his focus on structure over rate, Bill helps investors, business owners, and developers navigate complex transactions with clarity, precision, and a long-term wealth-building mindset.
The Client Experience
Great experience purchasing our first home! Bill was easy to reach and always able to answer any questions or concerns.

Loan Programs Available


Blogs
The Top 5 Mortgage Mistakes to Avoid
Buying your first home can be both exciting and nerve-wracking at the same time. With so many things to consider and....
Mortgage Do and
Do not list
Mortgages can be tricky, and it's easy to make mistakes that can end up costing you dearly. That's why we've put together this list....
Tips On How To Improve Your Credit Score
Let's talk about some ways you can improve your credit score! Your credit score is actually a big deal, and it can affect...
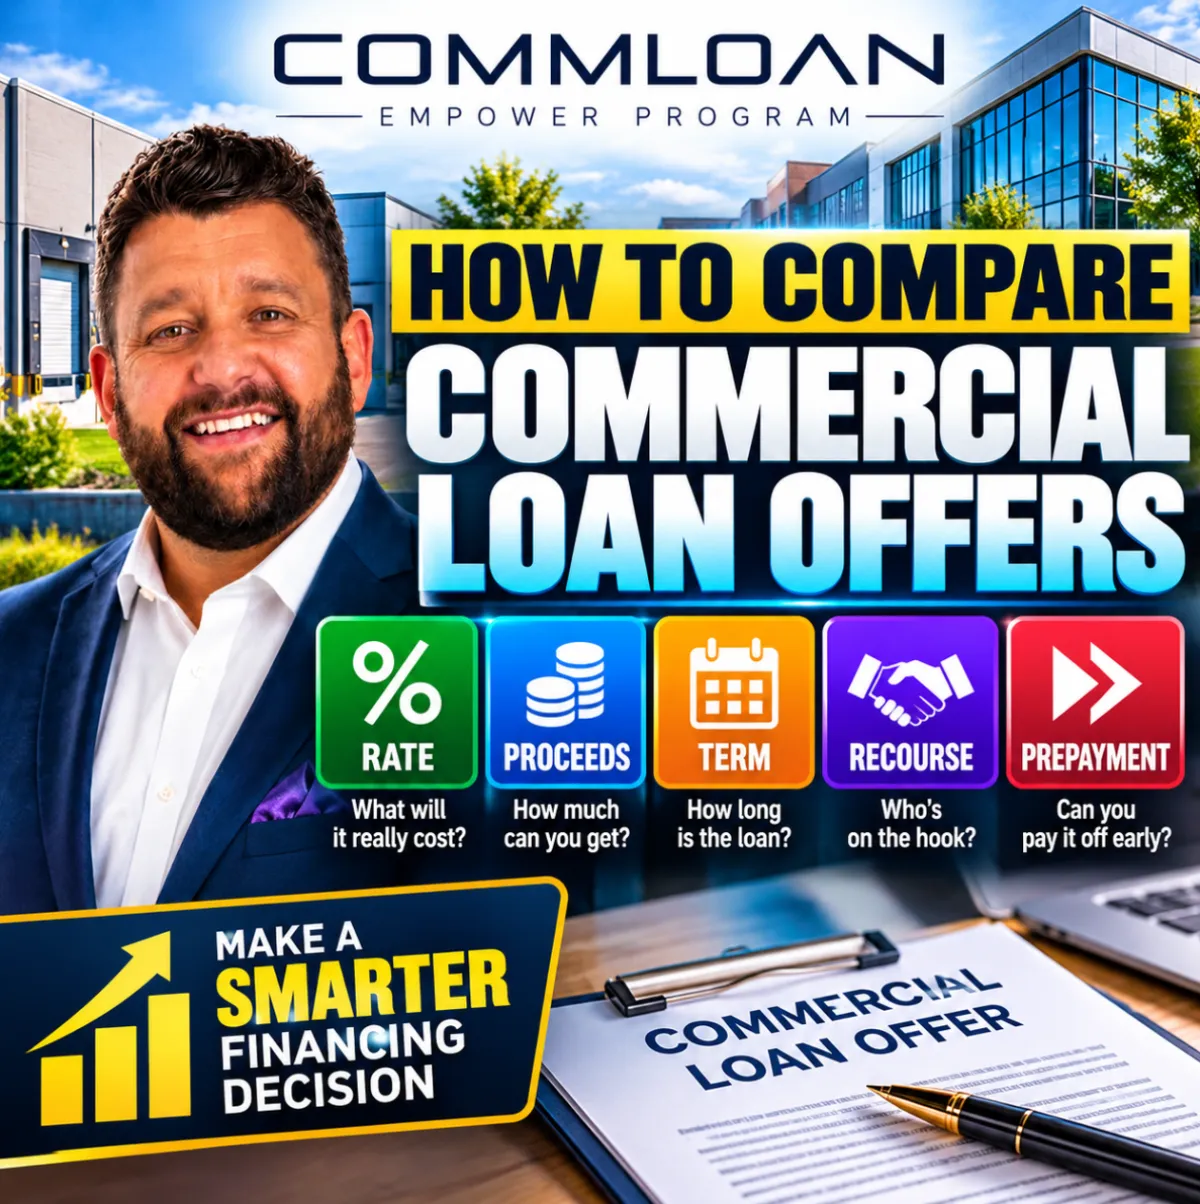
🏦 How to Compare Commercial Loan Offers: Rate, Proceeds, Term, Recourse & Prepayment 🔍
🏦 How to Compare Commercial Loan Offers: Rate, Proceeds, Term, Recourse & Prepayment 🔍
💰 The Lowest Rate Isn’t Always the Best Deal: 5 Factors to Compare in a Commercial Real Estate Loan 🏢
How to Compare Commercial Loan Offers: Rate, Proceeds, Term, Recourse and Prepayment
When commercial real estate investors and business owners receive multiple loan offers, the natural reaction is often to look at one number first:
The interest rate.
That makes sense—but it can also lead to the wrong financing decision.
A commercial loan with a lower interest rate is not automatically the better loan. One lender may offer a lower rate but provide fewer proceeds, require full recourse, impose a shorter term or include restrictive prepayment provisions. Another lender may charge a slightly higher rate but offer more leverage, better flexibility or terms that fit your investment strategy more effectively.
The key is to compare the entire commercial loan structure, not one number on the term sheet.
Here are five factors I believe borrowers should evaluate when comparing commercial real estate loan offers.
1. Interest Rate: What Will the Debt Actually Cost?
The interest rate matters because it directly affects your debt service, cash flow and debt service coverage ratio.
But don't stop at the quoted rate.
Determine whether the commercial loan has a fixed or floating interest rate.
A fixed-rate loan can provide payment certainty throughout the fixed-rate period. A floating-rate loan typically moves with an underlying benchmark plus a lender spread, meaning your borrowing cost can increase or decrease as the benchmark changes.
For floating-rate debt, borrowers should also evaluate whether the lender requires an interest-rate cap or other hedging arrangement.
Then consider fees.
Origination fees, lender fees, legal costs and other financing expenses can materially affect your total cost of capital.
Instead of asking only:
"What's my rate?"
Ask:
"What is the total economic cost of this financing?"
2. Loan Proceeds: How Much Capital Is the Lender Actually Providing?
Two lenders can evaluate the exact same property and arrive at significantly different loan amounts.
That's because commercial real estate lenders may size loans using several constraints, including:
·Loan-to-Value (LTV)
·Loan-to-Cost (LTC)
·Debt Service Coverage Ratio (DSCR)
·Debt Yield
·Property cash flow
·Borrower liquidity and net worth
·Property type and market
·Lender-specific underwriting requirements
For example, a lender may advertise 75% maximum LTV, but that does not necessarily mean your transaction will qualify for 75% leverage.
If DSCR or debt yield supports only a smaller loan, your actual proceeds may be lower.
That difference can have a major impact on the equity you need to bring to closing.
This is why commercial loan proceeds should be evaluated alongside the rate.
Saving 25 basis points may not be worth it if another structure provides substantially more capital and better aligns with your investment objectives.
3. Loan Term and Amortization: Don't Confuse the Two
Commercial borrowers should understand the difference between loan term and amortization.
The loan term determines when the loan matures.
The amortization period determines the schedule used to calculate principal repayment.
For example, you might receive a:
5-year loan with 25-year amortization.
Your monthly payment is calculated as though the loan were being repaid over 25 years, but the remaining balance becomes due when the loan matures after five years.
That creates a balloon payment.
When comparing loan offers, consider whether the maturity aligns with your expected business or investment timeline.
If you expect to own a property for ten years, a five-year maturity introduces refinancing risk midway through your projected hold.
That doesn't necessarily make the loan unattractive—but it is a risk that should be understood before closing.
4. Recourse: What Are You Personally Guaranteeing?
One of the most important—and sometimes overlooked—differences between commercial loan offers is recourse.
With a full-recourse loan, the borrower or guarantor may be personally responsible for the debt subject to the loan documents and applicable law.
A non-recourse loan generally limits the lender's recovery to the collateral, although commercial non-recourse loans commonly contain carve-outs that can create liability under specified circumstances.
Between these structures, borrowers may encounter limited or partial recourse.
The right structure depends on the transaction, lender, property and borrower.
When comparing term sheets, don't treat recourse as boilerplate.
Ask:
What exactly am I guaranteeing, for how long, and under what circumstances could that guarantee be enforced?
Those questions can be just as important as the interest rate.
5. Prepayment: What Happens When You Want to Exit?
This is where an attractive commercial loan can become surprisingly expensive.
Imagine receiving an excellent fixed interest rate today, but two years later you decide to sell the property.
Can you simply pay off the loan?
Maybe.
Commercial loans can include several types of prepayment structures, such as step-down penalties, yield maintenance, defeasance, lockout periods or other lender-specific provisions.
A step-down structure might decline over time—for example, 5%, 4%, 3%, 2% and 1%—although actual structures vary considerably by lender and loan.
Yield maintenance or defeasance can be substantially more complex.
This makes your exit strategy critical when choosing commercial financing.
An investor planning a long-term hold may evaluate prepayment restrictions differently from an investor expecting to sell or refinance within three years.
Compare Commercial Loans Side by Side
Suppose you receive two hypothetical commercial loan offers.
Loan A
6.50% interest rate
$2,000,000 proceeds
5-year term
25-year amortization
Full recourse
5-4-3-2-1 prepayment structure
Loan B
6.75% interest rate
$2,200,000 proceeds
10-year term
30-year amortization
Limited recourse
Different prepayment provisions
Which is better?
There isn't enough information to answer that from the rate alone.
Loan A has the lower interest rate.
But Loan B provides $200,000 more in proceeds, a longer term and a different recourse structure.
Your expected hold period, cash-flow requirements, equity position, refinancing strategy and risk tolerance could materially affect how you evaluate the alternatives.
That is why sophisticated borrowers compare structure, not simply rate.
Look Beyond the Term Sheet
Commercial financing can also contain important provisions that aren't captured by the five headline numbers.
Depending on the transaction, borrowers should review requirements involving reserves, escrows, cash management, reporting, covenants, guaranties, extension options and lender approval rights.
A loan that appears attractive on the first page of a term sheet may look different after evaluating the complete structure.
The Bottom Line
When comparing commercial real estate loan offers, evaluate at least these five factors together:
Rate + Proceeds + Term + Recourse + Prepayment
Then ask a broader question:
Does this financing structure support my business plan and exit strategy?
The lowest rate may ultimately be the best choice—but it should win because the overall loan structure works for the transaction, not simply because one number is smaller.
Through the CommLoan Empower Program, I help commercial real estate investors and business owners evaluate financing alternatives and understand how different loan structures may affect their transactions.
Top of Form
Bottom of Form
Bill Rapp, CCIM
Director | CommLoan
📞 281-222-0433
📧 [email protected]
🌐 https://billrapp.commloan.com/
🌐 https://HoustonCommercialMortgage.com/
Commercial Real Estate Financing Nationwide
https://billrapp.commloan.com/
https://author.billrapponline.com/
https://www.amazon.com/dp/B0F32Z5BH2
https://veed.cello.so/FOmzTty6oi9
https://buymeacoffee.com/vikingente3
https://creplaybookseries.billrapponline.com
https://creplaybook.billrapponline.com/
©Bill Rapp, CCIM - Director - CommLoan
10 Tips for First-Time Homebuyers
Buying your first home can be both exciting and nerve-wracking at the same time. With so many things to consider and....
How To Choose the Right Lender for You
Lorem Ipsum is simply dummy text of the printing and typesetting industry. Lorem Ipsum has been the industry's standard dummy
Refinancing youe loan and when to do it
Lorem Ipsum is simply dummy text of the printing and typesetting industry. Lorem Ipsum has been the industry's standard dummy
Copyright ©2021 | Mortgage Viking Team
Licensed to Do Business | NMLS # 228246
This is not an offer to enter into an agreement. Not all customers will qualify. Information, rates and programs are subject to change without notice. All products are subject to credit and property approval. Other restrictions and limitations may apply. Copyright © 2021 | Medallion Funds
Corporate | NMLS ID NMLS # 1825831
Corporate Address : 2651 N. Green Valley Pkwy STE. 101 Henderson, NV 89014
Corporate NMLS NMLS # 1825831 | Company Website: https://medallionfunds.com/bill-rapp/
Copyright ©2021 | Mortgage Viking Team Licensed to Do Business | NMLS # 228246
This is not an offer to enter into an agreement. Not all customers will qualify. Information, rates and programs are subject to change without notice. All products are subject to credit and property approval. Other restrictions and limitations may apply
Corporate | NMLS ID NMLS # 1825831
Corporate Address : 2651 N. Green Valley Pkwy STE. 101 Henderson, NV 89014 https://medallionfunds.com/bill-rapp/
Facebook
Instagram
X
LinkedIn
Youtube
TikTok