Low Rates.
Our rates are low, our application is quick and easy! We can get you clear to close in as little as 10 days!
Trusted By Agents With
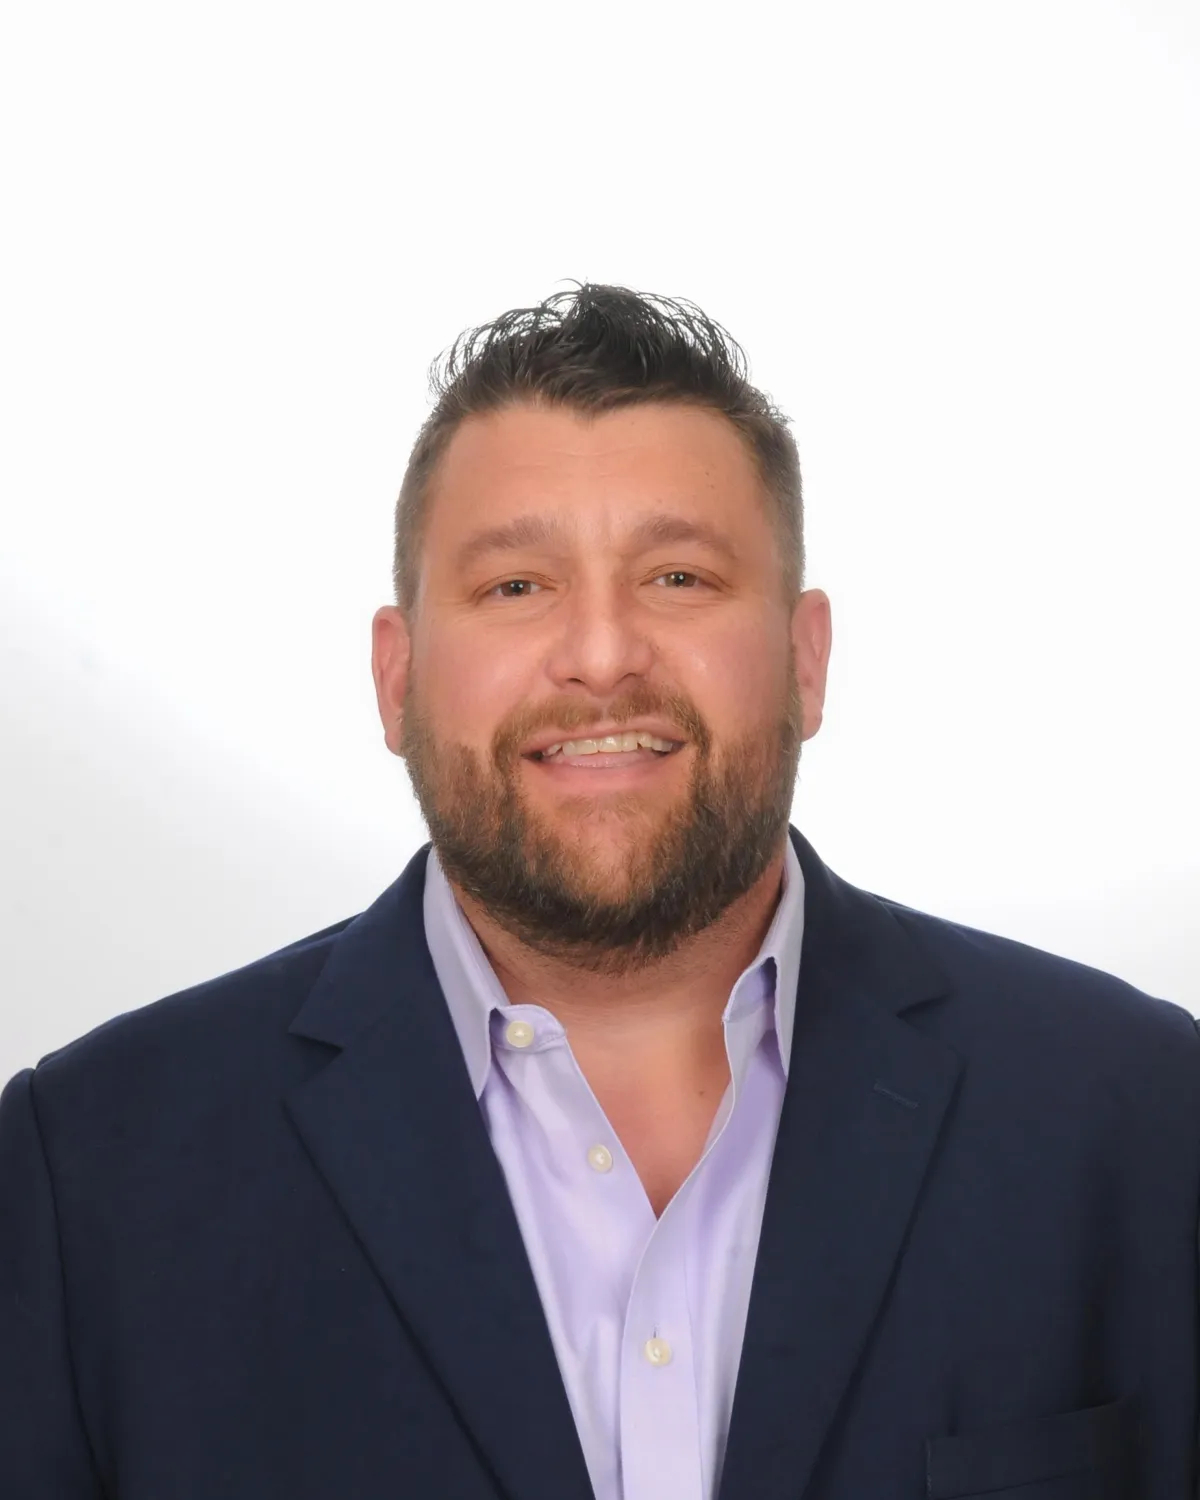
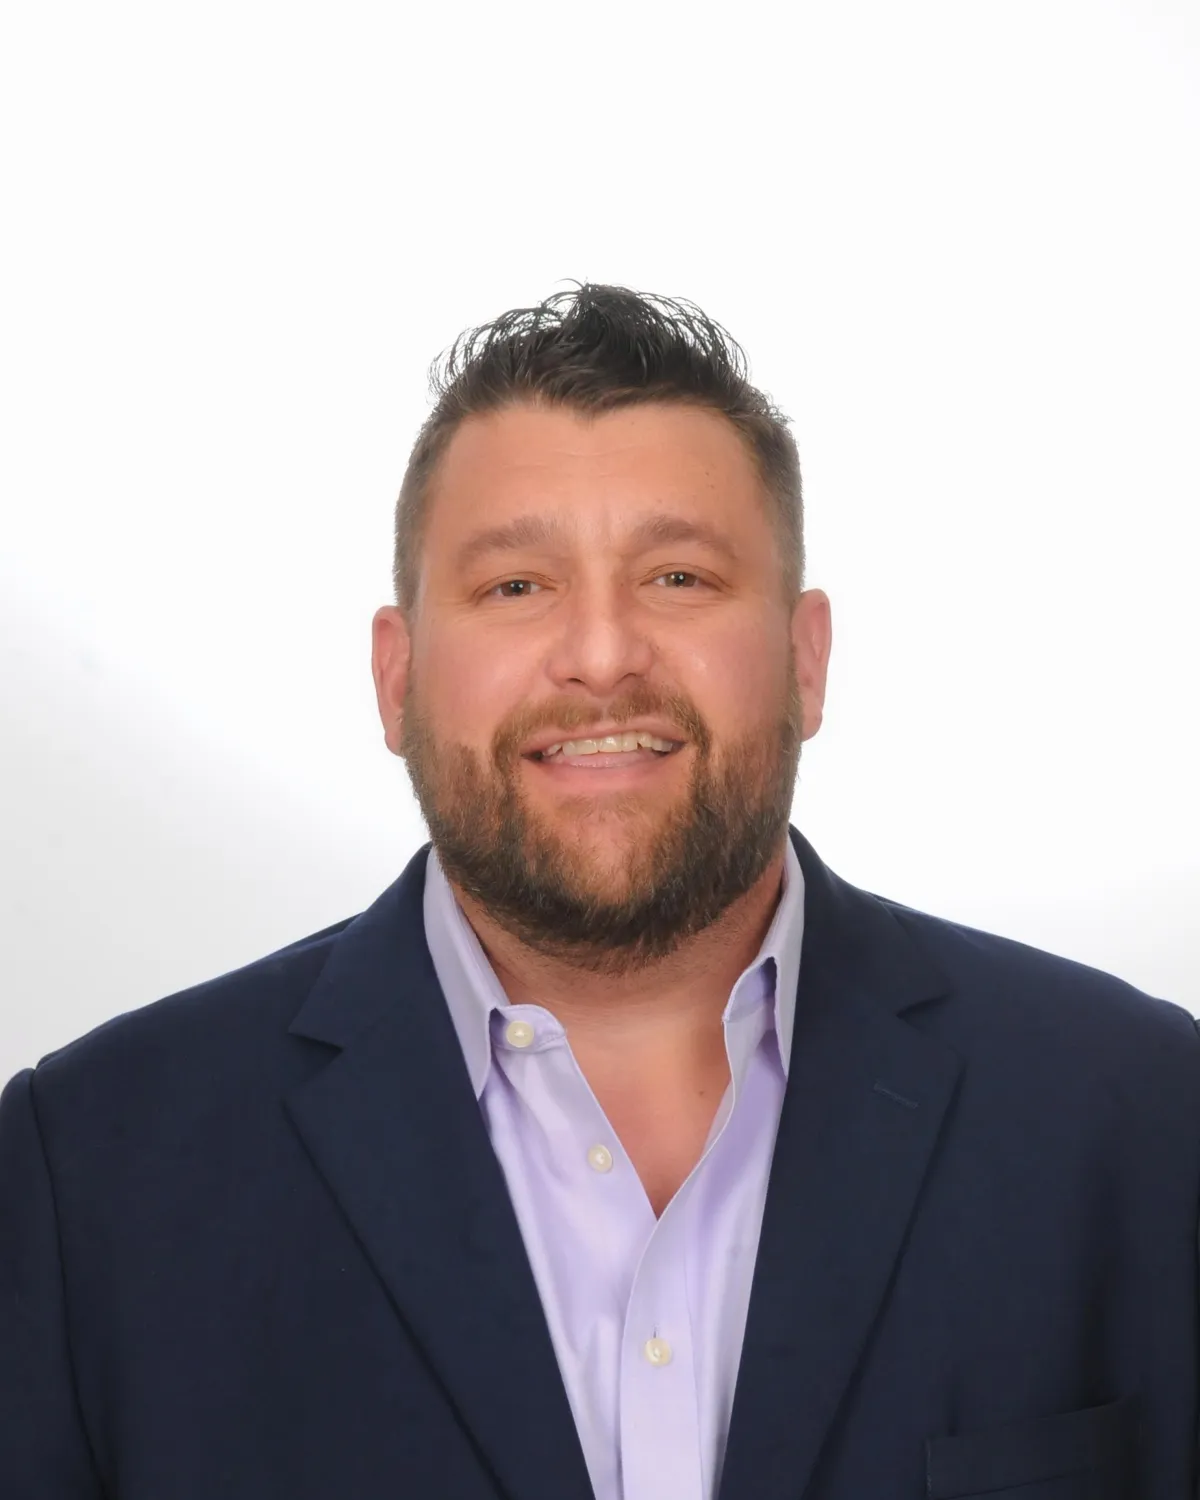
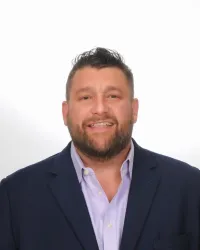
Meet Bill Rapp
NMLS ID # NMLS # 228246
Bill Rapp, CCIM is a Houston-based Capital Advisor at Medallion Funds, specializing in commercial real estate finance and strategic lending solutions. With over two decades of experience across brokerage and capital markets, Bill has worked with leading firms including eXp Commercial, NEXA Mortgage, Viking Enterprise LLC, and Sun Realty Houston.
A graduate of Texas A&M University with a BBA in Finance, Bill brings a disciplined, underwriting-first approach to every deal. His expertise spans commercial and residential financing, including asset-based lending, FHA financing, reverse mortgages, REO properties, and investment strategies for both single-family and commercial assets.
Known for his focus on structure over rate, Bill helps investors, business owners, and developers navigate complex transactions with clarity, precision, and a long-term wealth-building mindset.
The Client Experience
Great experience purchasing our first home! Bill was easy to reach and always able to answer any questions or concerns.

Loan Programs Available


Blogs
The Top 5 Mortgage Mistakes to Avoid
Buying your first home can be both exciting and nerve-wracking at the same time. With so many things to consider and....
Mortgage Do and
Do not list
Mortgages can be tricky, and it's easy to make mistakes that can end up costing you dearly. That's why we've put together this list....
Tips On How To Improve Your Credit Score
Let's talk about some ways you can improve your credit score! Your credit score is actually a big deal, and it can affect...
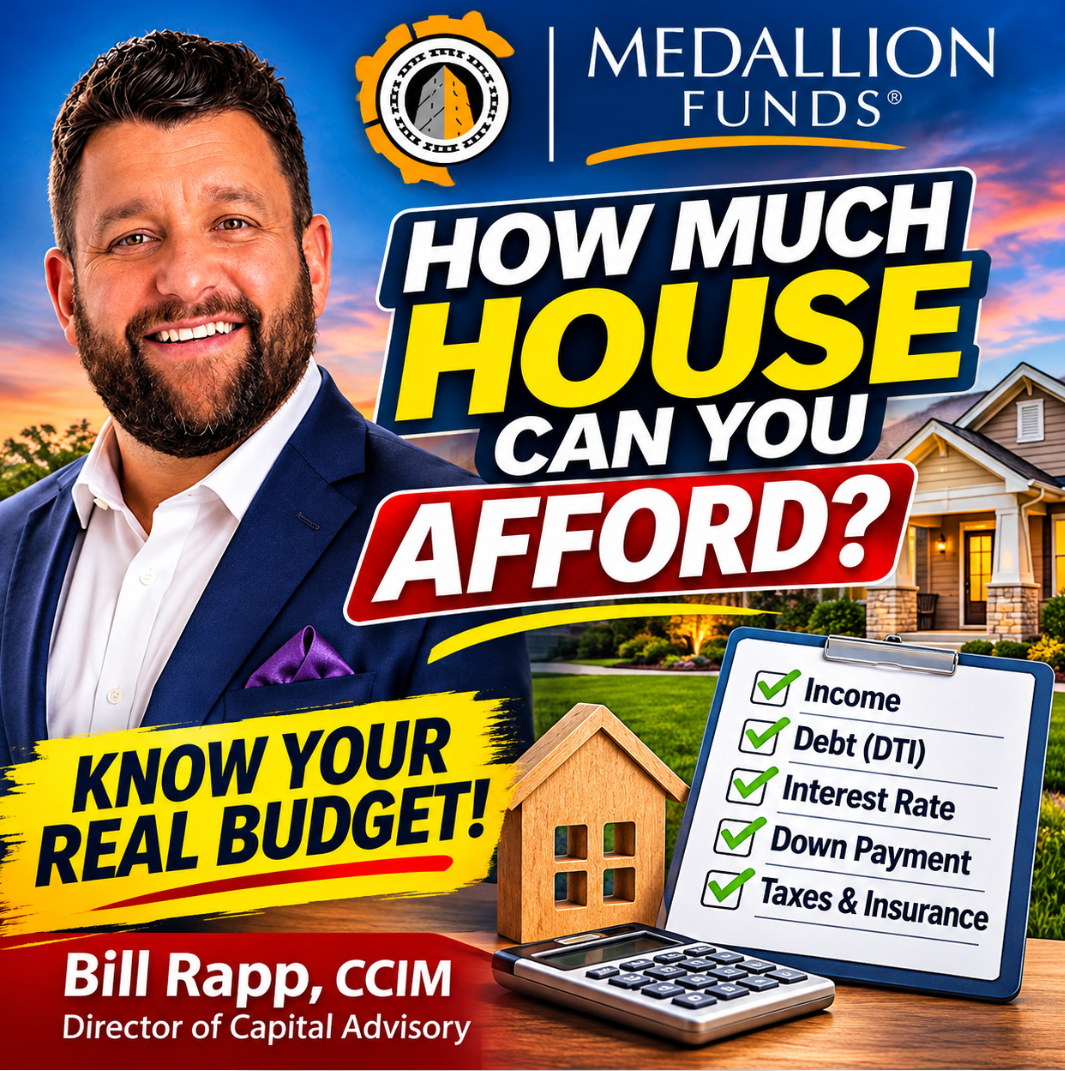
🏡 How Much House Can I Afford? 💰
🏡 How Much House Can I Afford? 💰
💰 How Much Home Can You REALLY Afford? 🏠
______________________________________________________________________________
🏡 How Much House Can I Afford? A Homebuyer's Guide to Finding Your Budget
Buying a home is one of the biggest financial decisions you will ever make. But before you start browsing listings, attending open houses, or falling in love with your dream kitchen, there is one important question you need to answer:
How much house can I actually afford?
The answer involves much more than your annual salary or the maximum mortgage amount a lender is willing to approve.
Your income, monthly debt, credit profile, down payment, mortgage interest rate, property taxes, homeowners insurance, and personal financial goals all play a role in determining your ideal homebuying budget.
At Medallion Funds, we help homebuyers evaluate their mortgage options and develop financing strategies designed around their individual financial circumstances—not simply the maximum amount they can borrow.
Here is what you need to know before purchasing your next home.
1. Understand the Difference Between Mortgage Qualification and Affordability
One of the biggest mistakes homebuyers make is assuming that the maximum mortgage amount they qualify for is the amount they should spend.
These are two very different things.
Mortgage qualification determines how much a lender may be willing to lend based on its underwriting guidelines.
Home affordability determines how much you can comfortably spend while maintaining your lifestyle, savings, and long-term financial goals.
For example, a lender might approve you for a $450,000 home. However, after accounting for childcare, retirement contributions, travel, emergency savings, and other expenses, you may feel more comfortable purchasing a $375,000 home.
The goal is not simply to become a homeowner.
The goal is to become a financially comfortable homeowner.
2. Calculate Your Debt-to-Income Ratio
Your debt-to-income ratio, commonly called DTI, is one of the most important factors lenders consider when evaluating your mortgage application.
DTI compares your qualifying monthly debt payments to your gross monthly income before taxes.
Your monthly debt obligations may include:
·Automobile payments
·Student loans
·Credit card minimum payments
·Personal loans
·Other mortgage payments
·Certain court-ordered financial obligations
·Your proposed monthly housing payment
The formula is:
Debt-to-Income Ratio = Total Qualifying Monthly Debt ÷ Gross Monthly Income × 100
For example, suppose you earn $8,000 per month before taxes.
Your existing monthly debt payments total $800, and your proposed mortgage payment, including taxes and insurance, is $2,400.
Your total monthly debt would be $3,200.
Your debt-to-income ratio would be:
$3,200 ÷ $8,000 = 40%
A 40% DTI may be acceptable under certain mortgage programs, depending on your credit, assets, income documentation, and other underwriting factors.
However, qualifying for a particular DTI does not necessarily mean that payment is comfortable for your personal budget.
3. Use the 28/36 Rule as a Starting Point
Many homebuyers use the traditional 28/36 rule when estimating mortgage affordability.
This guideline suggests:
·Spending approximately 28% or less of gross monthly income on housing expenses.
·Keeping total monthly debt payments at approximately 36% or less of gross monthly income.
For a household earning $100,000 annually, gross monthly income is approximately $8,333.
Using the 28% guideline, the suggested monthly housing budget would be approximately $2,333.
Using the 36% guideline, total monthly debt payments would be approximately $3,000.
If that household already has $700 in monthly debt, its suggested housing budget under the total debt guideline would be approximately $2,300.
These percentages are budgeting guidelines—not universal mortgage approval requirements.
Some borrowers may qualify with higher ratios, while others may prefer a more conservative budget.
4. Understand What Your Monthly Mortgage Payment Really Includes
Many online mortgage calculators focus primarily on principal and interest.
However, your actual monthly housing expenses can be significantly higher.
A typical mortgage payment may include four primary components, commonly known as PITI:
Principal: The portion of your payment that reduces your outstanding loan balance.
Interest: The cost of borrowing money from your mortgage lender.
Taxes: Property taxes assessed by local taxing authorities.
Insurance: Homeowners insurance and, when applicable, other required insurance coverage.
Additional expenses may include:
·Private mortgage insurance, or PMI
·FHA mortgage insurance premiums
·Homeowners association dues
·Flood insurance
·Maintenance and repairs
·Utilities
·Special assessments
This is especially important for Texas homebuyers, where property taxes, insurance costs, and certain HOA or special district assessments can materially affect affordability.
A $2,000 principal-and-interest payment could easily become a $2,800 total housing expense once other costs are included.
Always evaluate the complete cost of homeownership.
5. How Much House Can You Afford Based on Your Salary?
Your annual income provides a useful starting point for estimating your housing budget.
The following examples use the traditional 28% housing-expense guideline.
Annual Household Income | Gross Monthly Income | Illustrative Monthly Housing Budget |
$50,000 | $4,167 | $1,167 |
$75,000 | $6,250 | $1,750 |
$100,000 | $8,333 | $2,333 |
$125,000 | $10,417 | $2,917 |
$150,000 | $12,500 | $3,500 |
$200,000 | $16,667 | $4,667 |
These figures represent estimated total housing budgets, not just principal and interest.
Your actual purchasing power depends on your existing debt, mortgage rate, down payment, loan program, property taxes, insurance, and personal financial situation.
6. How Mortgage Interest Rates Affect Your Buying Power
Mortgage interest rates have a direct impact on the amount of home you can afford.
Even a relatively small change in your interest rate can significantly affect your monthly payment.
Consider a $400,000 home purchased with a 20% down payment, resulting in a $320,000 mortgage with a 30-year fixed term.
Illustrative Interest Rate | Monthly Principal & Interest |
5.5% | $1,817 |
6.0% | $1,919 |
6.5% | $2,023 |
7.0% | $2,129 |
The difference between a 5.5% and 7% mortgage rate is approximately $312 per month.
That represents roughly $3,744 per year in additional principal-and-interest payments.
These hypothetical rates are for educational purposes and are not current rate quotes or offers of financing.
The important takeaway is that mortgage affordability is influenced by both the purchase price and the cost of financing.
7. Your Down Payment Can Change Your Mortgage Strategy
A larger down payment generally reduces your mortgage balance and monthly principal-and-interest payment.
However, you do not necessarily need 20% down to purchase a home.
Depending on your qualifications, available mortgage programs may include:
·Conventional loans with down payments as low as 3% for eligible borrowers.
·FHA loans with down payments as low as 3.5% for eligible borrowers.
·VA loans offering zero-down financing for eligible veterans, service members, and certain surviving spouses.
·USDA loans offering zero-down financing for eligible borrowers and properties.
·Jumbo mortgages with varying down payment requirements.
·Physician mortgage programs designed for qualifying medical professionals.
Each loan program has different eligibility requirements, mortgage insurance provisions, credit guidelines, and potential fees.
A mortgage broker can help you compare available financing structures and evaluate whether preserving cash or making a larger down payment is more appropriate for your situation.
8. Real-World Example: Buying a $350,000 Home
Let's assume a household earns $120,000 annually and is considering purchasing a $350,000 home.
Here is an illustrative financing scenario:
Purchase Details | Amount |
Annual household income | $120,000 |
Gross monthly income | $10,000 |
Purchase price | $350,000 |
Down payment — 10% | $35,000 |
Mortgage amount | $315,000 |
Loan term | 30 years |
Illustrative interest rate | 6.5% |
The estimated monthly housing expenses might look like this:
Monthly Expense | Estimated Payment |
Principal and interest | $1,991 |
Property taxes | $600 |
Homeowners insurance | $200 |
Private mortgage insurance | $125 |
HOA dues | $75 |
Total estimated housing payment | $2,991 |
If the household has $600 in other qualifying monthly debt payments, total monthly debt would be $3,591.
The estimated debt-to-income ratio would be approximately 35.9%.
This example demonstrates why homebuyers must look beyond the advertised mortgage payment.
Although principal and interest total approximately $1,991, the estimated housing payment is nearly $3,000 per month.
The household would also need to budget for maintenance, utilities, closing costs, and emergency savings.
Actual taxes, insurance premiums, mortgage insurance, and financing terms will vary.
9. Don't Forget Closing Costs and Cash Reserves
Your down payment is not the only cash expense associated with buying a home.
Homebuyers should also prepare for:
·Mortgage origination and lender fees
·Appraisal fees
·Title and settlement charges
·Prepaid property taxes and insurance
·Home inspections
·Moving expenses
·Initial repairs and furnishings
Closing costs commonly range from approximately 2% to 5% of the purchase price, although actual costs vary by transaction and location.
For a $350,000 home, that could represent approximately $7,000 to $17,500 in additional expenses before considering applicable credits or assistance.
It is also important to maintain an emergency fund after closing.
Buying a home should not require completely depleting your savings.
10. How to Increase Your Homebuying Power
If your current budget does not support the home you want, several strategies may help improve your mortgage affordability.
Reduce existing debt. Paying down qualifying monthly obligations may improve your debt-to-income ratio.
Improve your credit profile. A stronger credit profile may help you access more favorable financing options.
Increase your down payment. A larger down payment may reduce your loan amount and mortgage insurance costs.
Compare mortgage programs. Different loan programs may offer different qualification requirements and payment structures.
Evaluate seller concessions. Eligible seller contributions may help reduce your upfront closing expenses or fund certain permitted rate buydowns.
Consider different locations. Property taxes, insurance, HOA dues, and home prices can vary significantly between neighborhoods.
Increase documented income. Additional qualifying income may improve your borrowing capacity when it meets lender documentation requirements.
The best strategy depends on your individual financial circumstances.
11. Why Mortgage Pre-Approval Matters
Before you begin shopping for a home, consider obtaining a mortgage pre-approval.
A mortgage pre-approval can help you:
·Understand your potential borrowing capacity.
·Identify suitable mortgage programs.
·Estimate your monthly housing payment.
·Determine your potential down payment and closing costs.
·Identify documentation or credit issues early.
·Shop for homes within a realistic price range.
Pre-approval is not a final loan commitment, and financing remains subject to underwriting, property eligibility, and other lender requirements.
Nevertheless, starting the process early can help you approach your home search with greater confidence.
Frequently Asked Questions About Home Affordability
How much house can I afford if I make $100,000 a year?
Using the traditional 28% guideline, a household earning $100,000 annually might begin with a total monthly housing budget of approximately $2,333. The corresponding purchase price depends on mortgage rates, down payment, taxes, insurance, and other financial obligations.
Can I buy a house with less than 20% down?
Yes. Several mortgage programs offer lower down payment options for qualified borrowers. Depending on the program, mortgage insurance or other fees may apply.
What debt-to-income ratio do I need for a mortgage?
DTI requirements vary by mortgage program, lender, and borrower qualifications. Some programs may allow ratios above 43%, but higher qualification limits should not automatically determine your personal spending budget.
Does mortgage pre-approval mean I can afford the entire loan amount?
Not necessarily. Pre-approval estimates potential borrowing capacity under lender guidelines. Your personal affordability should also account for living expenses, savings, retirement contributions, and financial goals.
How much money should I save before buying a home?
You should plan for your down payment, closing costs, moving expenses, potential repairs, and emergency savings. The appropriate amount depends on your purchase price, loan program, and financial circumstances.
Final Thoughts: Buy the Right Home, Not Just the Biggest Home
Determining how much house you can afford is about finding the right balance between homeownership and long-term financial stability.
A mortgage should support your financial goals—not prevent you from achieving them.
Before making an offer, evaluate your income, debt, savings, loan options, and complete monthly housing expenses.
At Medallion Funds, we help homebuyers explore financing strategies designed around their individual needs. Whether you are purchasing your first home, moving into a larger property, or exploring specialized mortgage programs, understanding your options is an important first step.
Ready to discover how much house you can afford?
Contact me today to discuss your mortgage options and develop a financing strategy that fits your goals.
Bill Rapp
Partner & Director of Capital Advisory | Medallion Funds
Commercial Lending Nationwide
Residential Lending in AL, CA, CO, NV & TXBottom of Form
📞 Call or Text: 281-222-0433
🌐 Website: https://billrapponline.com
🎥 Subscribe to Mortgage Viking: https://www.youtube.com/@billrapp-medallion-funds
https://www.billrapponline.com/
https://findamortgagebroker.com/Profile/WilliamRappJr28883
https://billrapp.commloan.com/
https://billrapponline.com/financingfuturescre-houston-katy
https://houstoncommercialmortgage.com/
https://author.billrapponline.com
https://doctorvideo.billrapponline.com/
https://veteransvideo.billrapponline.com/
https://mortgageviking.billrapponline.com/
https://fha203h.billrapponline.com/
https://renovationvideo.billrapponline.com
https://medallionfunds.com/bill-rapp/
https://www.amazon.com/dp/B0F32Z5BH2
https://veed.cello.so/FOmzTty6oi9
https://buymeacoffee.com/vikingente3
https://creplaybookseries.billrapponline.com
https://creplaybook.billrapponline.com/
© Bill Rapp, Medallion Funds LLC, Director of Capital Advisory
10 Tips for First-Time Homebuyers
Buying your first home can be both exciting and nerve-wracking at the same time. With so many things to consider and....
How To Choose the Right Lender for You
Lorem Ipsum is simply dummy text of the printing and typesetting industry. Lorem Ipsum has been the industry's standard dummy
Refinancing youe loan and when to do it
Lorem Ipsum is simply dummy text of the printing and typesetting industry. Lorem Ipsum has been the industry's standard dummy
Copyright ©2021 | Mortgage Viking Team
Licensed to Do Business | NMLS # 228246
This is not an offer to enter into an agreement. Not all customers will qualify. Information, rates and programs are subject to change without notice. All products are subject to credit and property approval. Other restrictions and limitations may apply. Copyright © 2021 | Medallion Funds
Corporate | NMLS ID NMLS # 1825831
Corporate Address : 2651 N. Green Valley Pkwy STE. 101 Henderson, NV 89014
Corporate NMLS NMLS # 1825831 | Company Website: https://medallionfunds.com/bill-rapp/
Copyright ©2021 | Mortgage Viking Team Licensed to Do Business | NMLS # 228246
This is not an offer to enter into an agreement. Not all customers will qualify. Information, rates and programs are subject to change without notice. All products are subject to credit and property approval. Other restrictions and limitations may apply
Corporate | NMLS ID NMLS # 1825831
Corporate Address : 2651 N. Green Valley Pkwy STE. 101 Henderson, NV 89014 https://medallionfunds.com/bill-rapp/
Facebook
Instagram
X
LinkedIn
Youtube
TikTok