Low Rates.
Our rates are low, our application is quick and easy! We can get you clear to close in as little as 10 days!
Trusted By Agents With
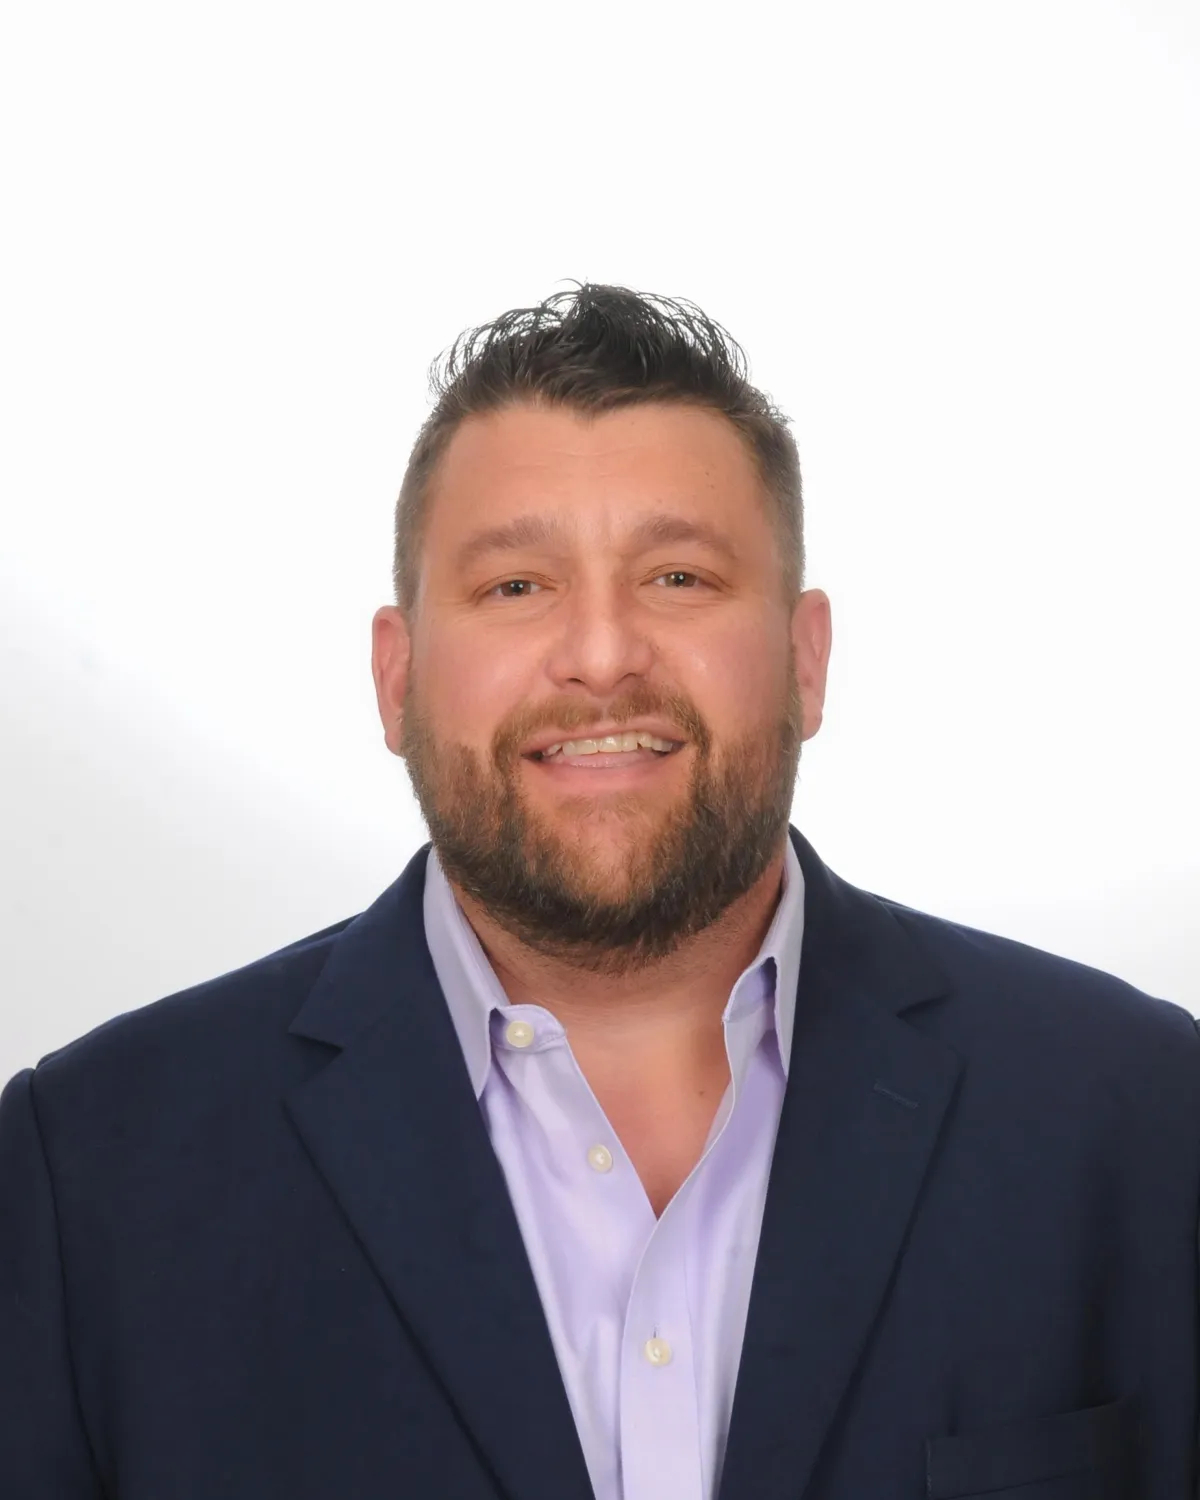
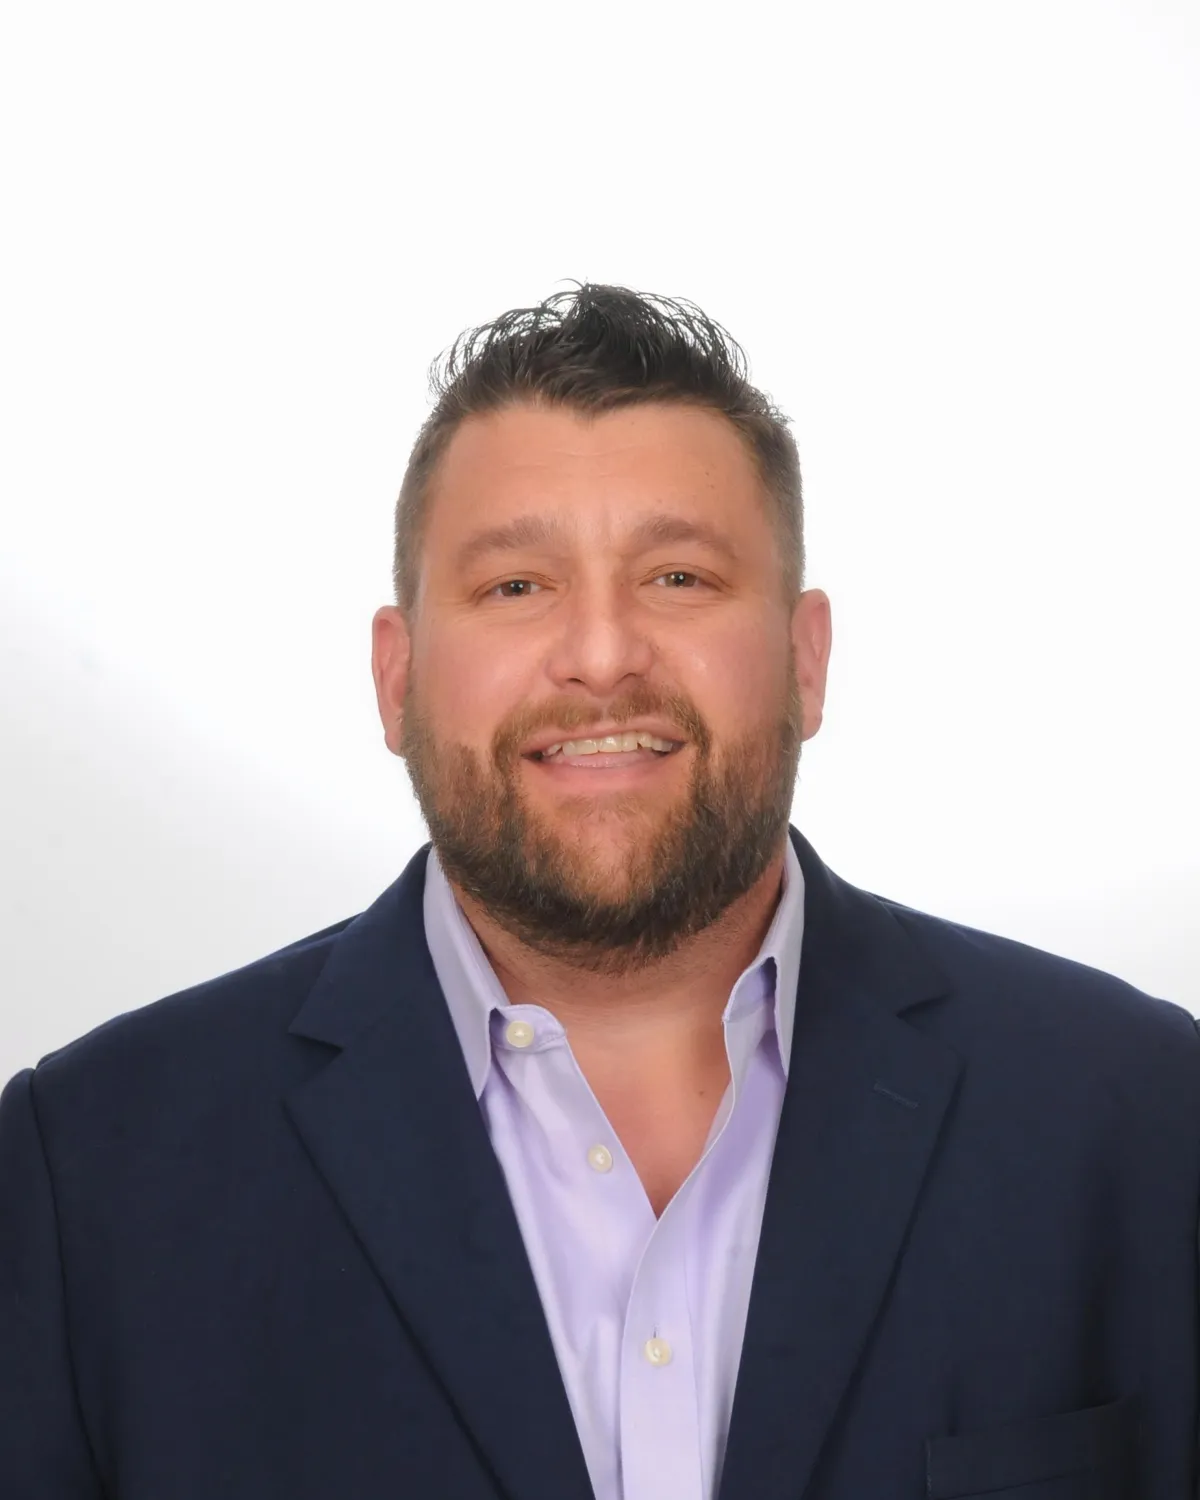
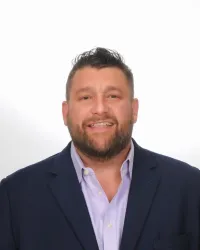
Meet Bill Rapp
NMLS ID # NMLS # 228246
Bill Rapp, CCIM is a Houston-based Capital Advisor at Medallion Funds, specializing in commercial real estate finance and strategic lending solutions. With over two decades of experience across brokerage and capital markets, Bill has worked with leading firms including eXp Commercial, NEXA Mortgage, Viking Enterprise LLC, and Sun Realty Houston.
A graduate of Texas A&M University with a BBA in Finance, Bill brings a disciplined, underwriting-first approach to every deal. His expertise spans commercial and residential financing, including asset-based lending, FHA financing, reverse mortgages, REO properties, and investment strategies for both single-family and commercial assets.
Known for his focus on structure over rate, Bill helps investors, business owners, and developers navigate complex transactions with clarity, precision, and a long-term wealth-building mindset.
The Client Experience
Great experience purchasing our first home! Bill was easy to reach and always able to answer any questions or concerns.

Loan Programs Available


Blogs
The Top 5 Mortgage Mistakes to Avoid
Buying your first home can be both exciting and nerve-wracking at the same time. With so many things to consider and....
Mortgage Do and
Do not list
Mortgages can be tricky, and it's easy to make mistakes that can end up costing you dearly. That's why we've put together this list....
Tips On How To Improve Your Credit Score
Let's talk about some ways you can improve your credit score! Your credit score is actually a big deal, and it can affect...
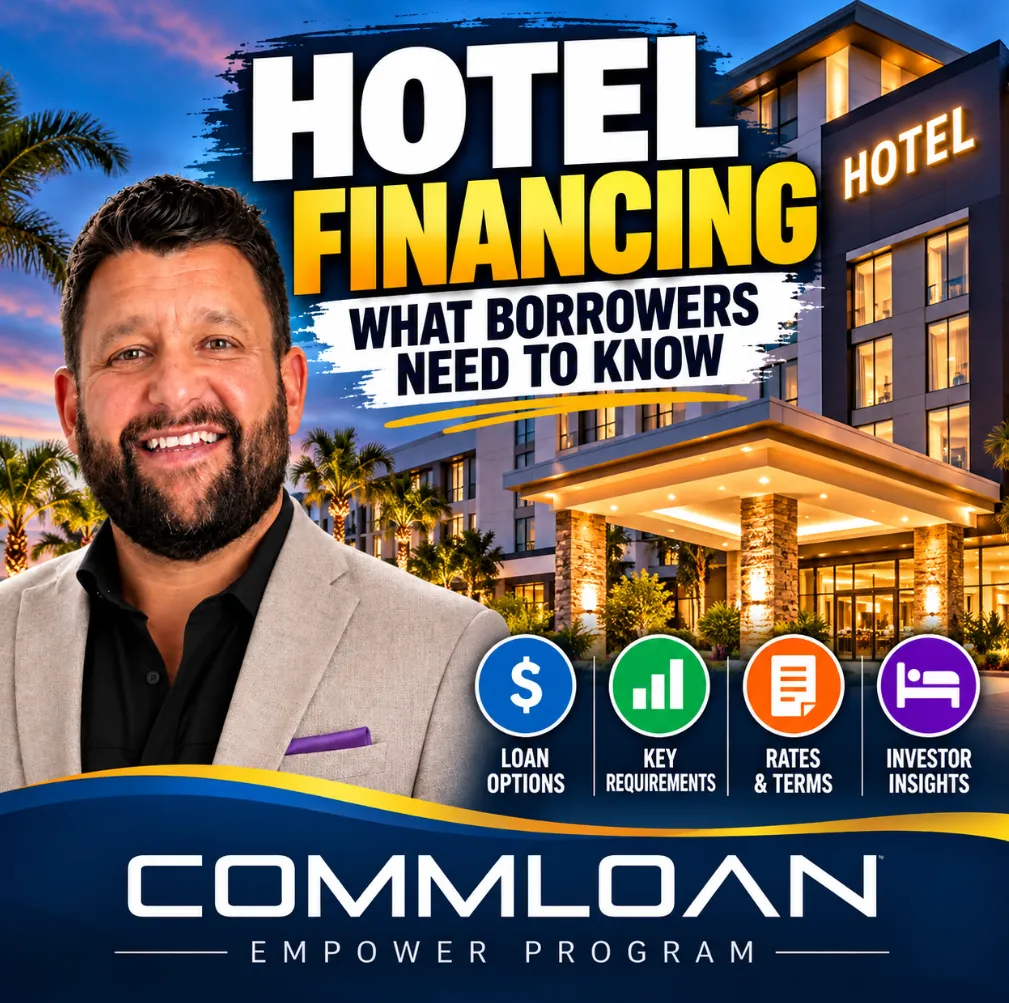
🏨 Hotel Financing Explained: What Every Borrower Needs to Know Before Applying for a Hotel Loan 💰
🏨 Hotel Financing Explained: What Every Borrower Needs to Know Before Applying for a Hotel Loan 💰
💵 Hotel Loans Made Simple: Financing Options, Down Payments & Lender Requirements 🏨
________________________________________________________________________________
Hotel Financing: What Borrowers Need to Know Before Applying for a Hotel Loan
Financing a hotel is different from financing a traditional commercial real estate investment. Hotels operate as both real estate assets and active businesses, making underwriting more complex than it is for many office, retail, industrial, or multifamily properties.
Whether you're purchasing an existing hotel, refinancing a hospitality property, renovating an underperforming asset, or developing a new hotel, understanding hotel financing requirements, loan structures, and lender expectations can help you secure the right capital.
At the CommLoan Empower Program, we help commercial real estate investors and business owners evaluate financing opportunities through a broad network of lenders.
Here's what borrowers need to know before pursuing hotel financing.
What Is Hotel Financing?
Hotel financing refers to commercial loans used to acquire, refinance, renovate, reposition, or construct hospitality properties.
Common property types include limited-service hotels, select-service hotels, full-service hotels, boutique hotels, extended-stay properties, and independent hotels.
Unlike conventional commercial real estate, hotel income depends on nightly room demand, occupancy, average daily room rates, operating efficiency, and competitive market conditions.
Because hospitality revenue can fluctuate significantly, lenders evaluate both the property's real estate value and its operational performance.
Types of Hotel Financing Available
1. Conventional Commercial Hotel Loans
Traditional banks and commercial lenders provide financing for established hotels with demonstrated operating histories.
These loans may offer competitive pricing to experienced operators with strong financial performance.
Typical considerations include:
·Historical operating income and cash flow
·Borrower liquidity and net worth
·Hotel franchise or brand affiliation
·Property condition and capital expenditure needs
·Market occupancy and demand trends
2. SBA Hotel Loans
Eligible owner-operated hotels may qualify for financing through SBA programs.
SBA 7(a) loans can support eligible acquisitions, refinancing, improvements, and certain business-related expenses, subject to program rules.
SBA 504 loans are generally designed for eligible long-term fixed-asset financing, including owner-occupied real estate and qualifying improvements.
Hotels must satisfy applicable SBA eligibility and occupancy requirements, including rules governing the operating business and property ownership structure.
SBA financing may be attractive to qualifying borrowers seeking lower down payments or longer amortization periods than certain conventional alternatives.
3. Hotel Bridge Loans
Bridge financing can be appropriate when a hotel requires significant renovation, operational improvement, or stabilization.
For example, an investor acquiring a hotel with below-market occupancy may use short-term financing while executing a property improvement plan.
Bridge loans typically involve higher financing costs and a defined exit strategy.
Borrowers should evaluate the projected refinance or sale carefully rather than assume stabilization will automatically produce permanent financing.
4. Hotel Construction Loans
Hotel construction financing supports ground-up development and, in some cases, major redevelopment.
Lenders may require:
·Detailed construction budgets and timelines
·Feasibility studies and market analysis
·Franchise agreements or brand commitments
·Developer and operator experience
·Equity contributions and contingency reserves
·A credible stabilization and permanent-financing strategy
Construction financing can involve staged advances and interest-only payments during development.
How Much Down Payment Do You Need for a Hotel Loan?
One of the most common questions borrowers ask is how much equity they need to purchase a hotel.
For preliminary planning, conventional hotel acquisitions may require approximately 25%–40% equity, although actual requirements vary substantially by lender, property, market, sponsor, and loan structure.
Certain eligible SBA transactions may require less, while bridge financing, construction, or distressed properties can require more.
For example, consider a $5 million hotel acquisition.
Equity contribution | Amount | Loan request |
25% | $1,250,000 | $3,750,000 |
30% | $1,500,000 | $3,500,000 |
35% | $1,750,000 | $3,250,000 |
These figures illustrate capital structures, not guaranteed lender approvals. Closing costs, reserves, renovations, and franchise-required improvements may increase the total equity needed.
Five Key Factors Hotel Lenders Evaluate
1. Debt Service Coverage Ratio (DSCR)
DSCR measures the property's ability to generate enough qualifying cash flow to cover debt service.
\[ DSCR=\frac{\text{Qualifying Cash Flow}}{\text{Annual Debt Service}} \]
For example, if a hotel's lender-adjusted cash flow is $650,000 and annual debt service is $500,000:
\[ DSCR=1.30x \]
That indicates $1.30 of qualifying cash flow for every $1.00 of debt service.
Lenders may require a DSCR around 1.25x–1.40x or higher, depending on the financing program and transaction. Some lenders also apply a debt-yield test.
2. Occupancy Rate
Occupancy measures the percentage of available room nights sold.
A hotel with 100 rooms selling an average of 70 rooms nightly has approximately 70% occupancy.
Lenders evaluate historical occupancy, seasonality, demand generators, and performance against competing hotels.
3. Average Daily Rate (ADR)
ADR represents average room revenue per occupied room.
Higher ADR can improve revenue, but only when supported by sustainable demand and occupancy.
4. Revenue Per Available Room (RevPAR)
RevPAR combines room pricing and occupancy into a single metric.
\[ RevPAR=ADR\times Occupancy \]
If ADR is $150 and occupancy is 70%, RevPAR equals $105.
RevPAR is particularly useful for evaluating a hotel's room-revenue productivity and comparing its performance with competitive properties.
5. Borrower Experience and Financial Strength
Hospitality lending is operationally intensive.
Lenders frequently examine the borrower's hotel management experience, liquidity, net worth, credit profile, operating partners, and ability to fund unexpected expenses.
An experienced management company may strengthen a financing proposal, although it does not necessarily replace sponsor requirements.
Why Hotel Cash Flow Matters More Than the Asking Price
A hotel may be worth $8 million based on a purchase contract or appraisal, but that does not automatically mean a lender will finance a particular percentage of that value.
Hotel loans are often constrained by several underwriting tests:
·Loan-to-value (LTV)
·Debt service coverage ratio (DSCR)
·Debt yield
·Borrower equity and liquidity
·Franchise and property improvement requirements
The lowest allowable loan amount resulting from these constraints may determine the maximum financing available.
The central question is not simply how much the hotel is worth. It's how much debt the hotel's sustainable cash flow can support.
Franchise Agreements and Property Improvement Plans
Many branded hotels operate under franchise agreements that impose operational and physical-property standards.
When a hotel changes ownership, the franchisor may require a Property Improvement Plan (PIP).
A PIP can involve guestroom renovations, furniture replacements, lobby upgrades, technology improvements, exterior improvements, and other brand-mandated work.
For borrowers, these obligations can materially change the total acquisition budget.
For example, a $6 million hotel purchase with a $1 million PIP may require significantly more capital than the purchase price alone suggests.
Lenders generally want to understand the PIP scope, costs, timing, available funding, and operational disruption before approving financing.
Documents Needed to Apply for a Hotel Loan
Preparing a complete financing package can help streamline lender review.
Typical documentation includes:
1.Current and historical operating statements, often three years when available.
2.Trailing 12-month financial statements.
3.Occupancy, ADR, and RevPAR reports.
4.STR or comparable competitive-set reports, when available.
5.Franchise agreement and applicable PIP.
6.Purchase contract or refinancing information.
7.Borrower financial statements and liquidity verification.
8.Business plan and management background.
9.Renovation or construction budgets, if applicable.
10.Property information, insurance, and existing debt details.
Additional tax returns, entity documents, and third-party reports may be requested.
Hotel Financing Mistakes to Avoid
Mistake #1: Shopping exclusively for the lowest interest rate. A lower rate may come with reduced proceeds, restrictive prepayment provisions, or an unfavorable maturity.
Mistake #2: Underestimating renovation expenses. Franchise PIPs and deferred maintenance can create significant capital requirements.
Mistake #3: Relying on projected occupancy without support. Lenders want credible assumptions grounded in actual market performance.
Mistake #4: Ignoring loan maturity and refinancing risk. A hotel that cannot meet permanent-loan underwriting requirements at maturity may require additional equity or a sale.
Mistake #5: Approaching lenders without a complete financial package. Missing operating statements, room metrics, or capital budgets can delay underwriting.
Why Work With a Commercial Mortgage Advisor?
Hotel financing is not a one-size-fits-all transaction.
Different lenders have different appetites for hospitality assets, franchise brands, loan sizes, markets, borrower profiles, and business plans.
Working with a commercial mortgage advisor can help borrowers compare loan structures, identify financing constraints, and evaluate multiple capital sources.
Through the CommLoan Empower Program, borrowers can explore financing opportunities using CommLoan's CUPID™ commercial lending platform and its network of 700+ lenders.
The objective is to identify financing that supports the property's operating performance, investment strategy, and long-term goals.
Final Thoughts: Structure the Financing Around the Hotel
Hotel financing requires more than a favorable appraisal or an attractive purchase price.
Successful borrowers understand their hotel's cash flow, operating performance, equity requirements, franchise obligations, and exit strategy before approaching lenders.
Whether you're acquiring your first hospitality property or expanding an established hotel portfolio, preparing the right information and evaluating financing alternatives can make a meaningful difference.
Ready to Explore Hotel Financing?
I'm Bill Rapp, CCIM, with the CommLoan Empower Program.
If you're purchasing, refinancing, renovating, or developing a hotel, let's evaluate the opportunity and determine what financing structure may fit your transaction.
Top of Form
Bottom of Form
Bill Rapp, CCIM
Director | CommLoan
📞 281-222-0433
📧 [email protected]
🌐 https://billrapp.commloan.com/
🌐 https://HoustonCommercialMortgage.com/
Commercial Real Estate Financing Nationwide
https://billrapp.commloan.com/
https://author.billrapponline.com/
https://www.amazon.com/dp/B0F32Z5BH2
https://veed.cello.so/FOmzTty6oi9
https://buymeacoffee.com/vikingente3
https://creplaybookseries.billrapponline.com
https://creplaybook.billrapponline.com/
©Bill Rapp, CCIM - Director - CommLoan
10 Tips for First-Time Homebuyers
Buying your first home can be both exciting and nerve-wracking at the same time. With so many things to consider and....
How To Choose the Right Lender for You
Lorem Ipsum is simply dummy text of the printing and typesetting industry. Lorem Ipsum has been the industry's standard dummy
Refinancing youe loan and when to do it
Lorem Ipsum is simply dummy text of the printing and typesetting industry. Lorem Ipsum has been the industry's standard dummy
Copyright ©2021 | Mortgage Viking Team
Licensed to Do Business | NMLS # 228246
This is not an offer to enter into an agreement. Not all customers will qualify. Information, rates and programs are subject to change without notice. All products are subject to credit and property approval. Other restrictions and limitations may apply. Copyright © 2021 | Medallion Funds
Corporate | NMLS ID NMLS # 1825831
Corporate Address : 2651 N. Green Valley Pkwy STE. 101 Henderson, NV 89014
Corporate NMLS NMLS # 1825831 | Company Website: https://medallionfunds.com/bill-rapp/
Copyright ©2021 | Mortgage Viking Team Licensed to Do Business | NMLS # 228246
This is not an offer to enter into an agreement. Not all customers will qualify. Information, rates and programs are subject to change without notice. All products are subject to credit and property approval. Other restrictions and limitations may apply
Corporate | NMLS ID NMLS # 1825831
Corporate Address : 2651 N. Green Valley Pkwy STE. 101 Henderson, NV 89014 https://medallionfunds.com/bill-rapp/
Facebook
Instagram
X
LinkedIn
Youtube
TikTok