Low Rates.
Our rates are low, our application is quick and easy! We can get you clear to close in as little as 10 days!
Trusted By Agents With
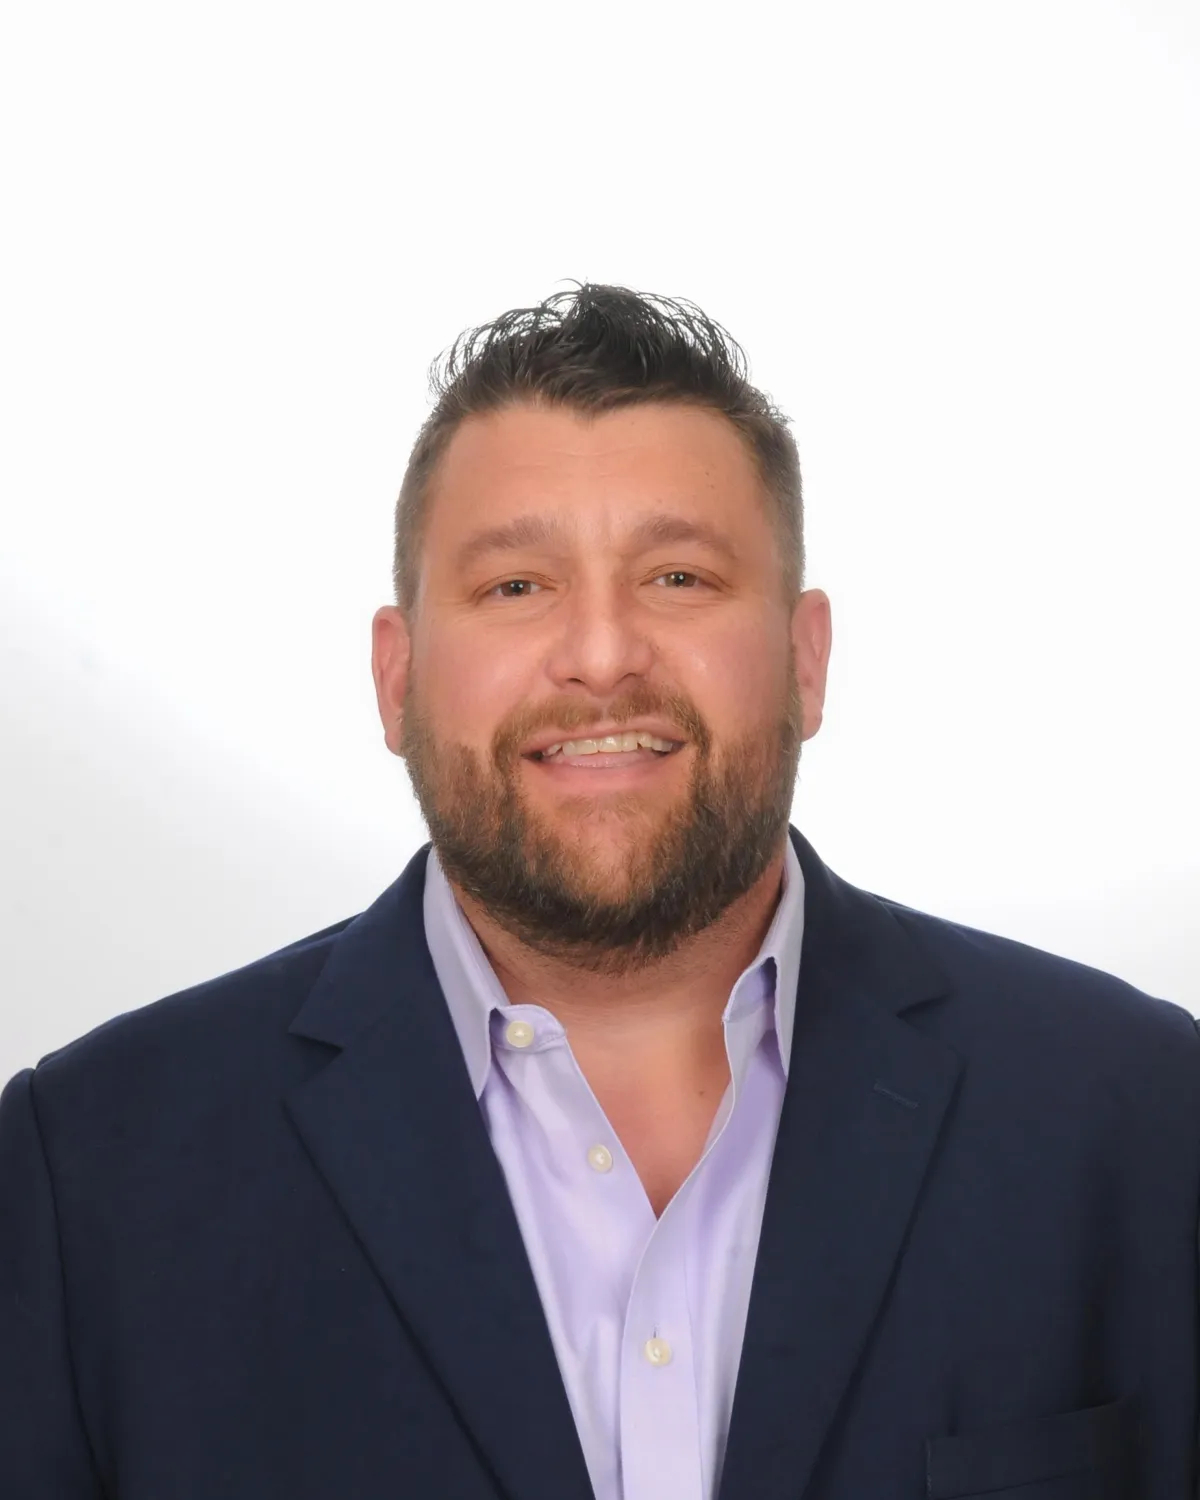
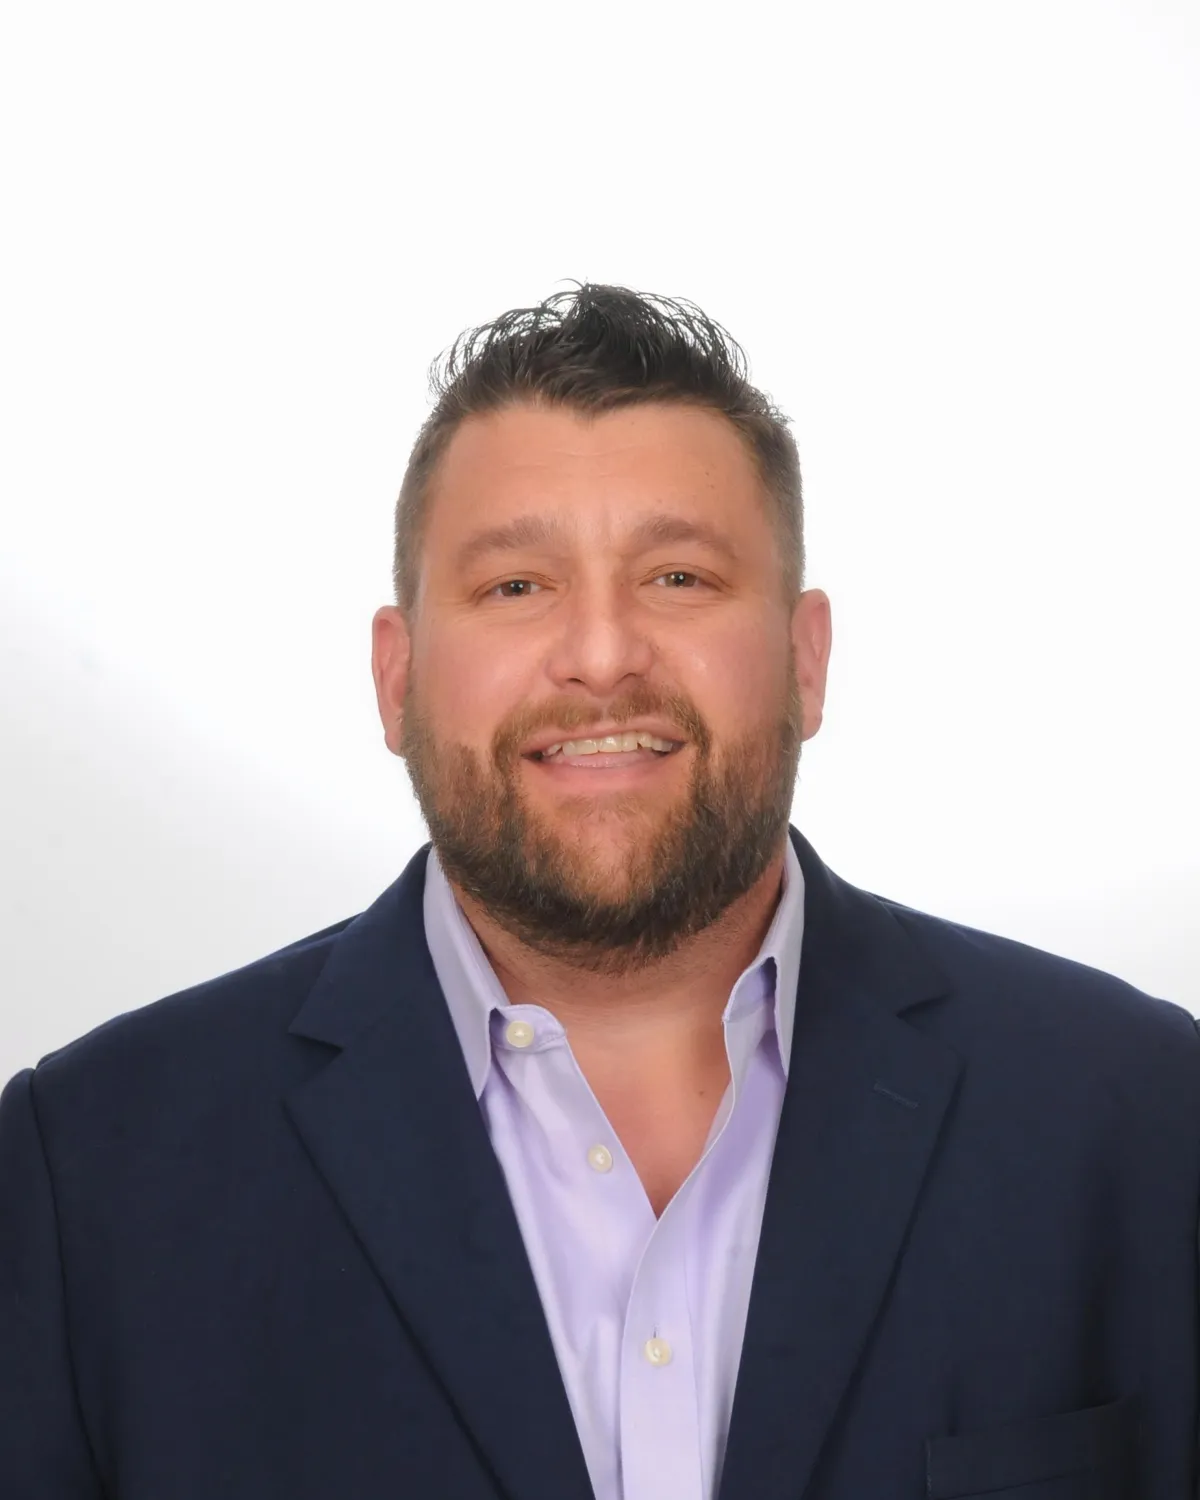
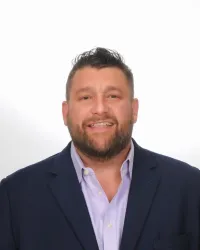
Meet Bill Rapp
NMLS ID # NMLS # 228246
Bill Rapp, CCIM is a Houston-based Capital Advisor at Medallion Funds, specializing in commercial real estate finance and strategic lending solutions. With over two decades of experience across brokerage and capital markets, Bill has worked with leading firms including eXp Commercial, NEXA Mortgage, Viking Enterprise LLC, and Sun Realty Houston.
A graduate of Texas A&M University with a BBA in Finance, Bill brings a disciplined, underwriting-first approach to every deal. His expertise spans commercial and residential financing, including asset-based lending, FHA financing, reverse mortgages, REO properties, and investment strategies for both single-family and commercial assets.
Known for his focus on structure over rate, Bill helps investors, business owners, and developers navigate complex transactions with clarity, precision, and a long-term wealth-building mindset.
The Client Experience
Great experience purchasing our first home! Bill was easy to reach and always able to answer any questions or concerns.

Loan Programs Available


Blogs
The Top 5 Mortgage Mistakes to Avoid
Buying your first home can be both exciting and nerve-wracking at the same time. With so many things to consider and....
Mortgage Do and
Do not list
Mortgages can be tricky, and it's easy to make mistakes that can end up costing you dearly. That's why we've put together this list....
Tips On How To Improve Your Credit Score
Let's talk about some ways you can improve your credit score! Your credit score is actually a big deal, and it can affect...
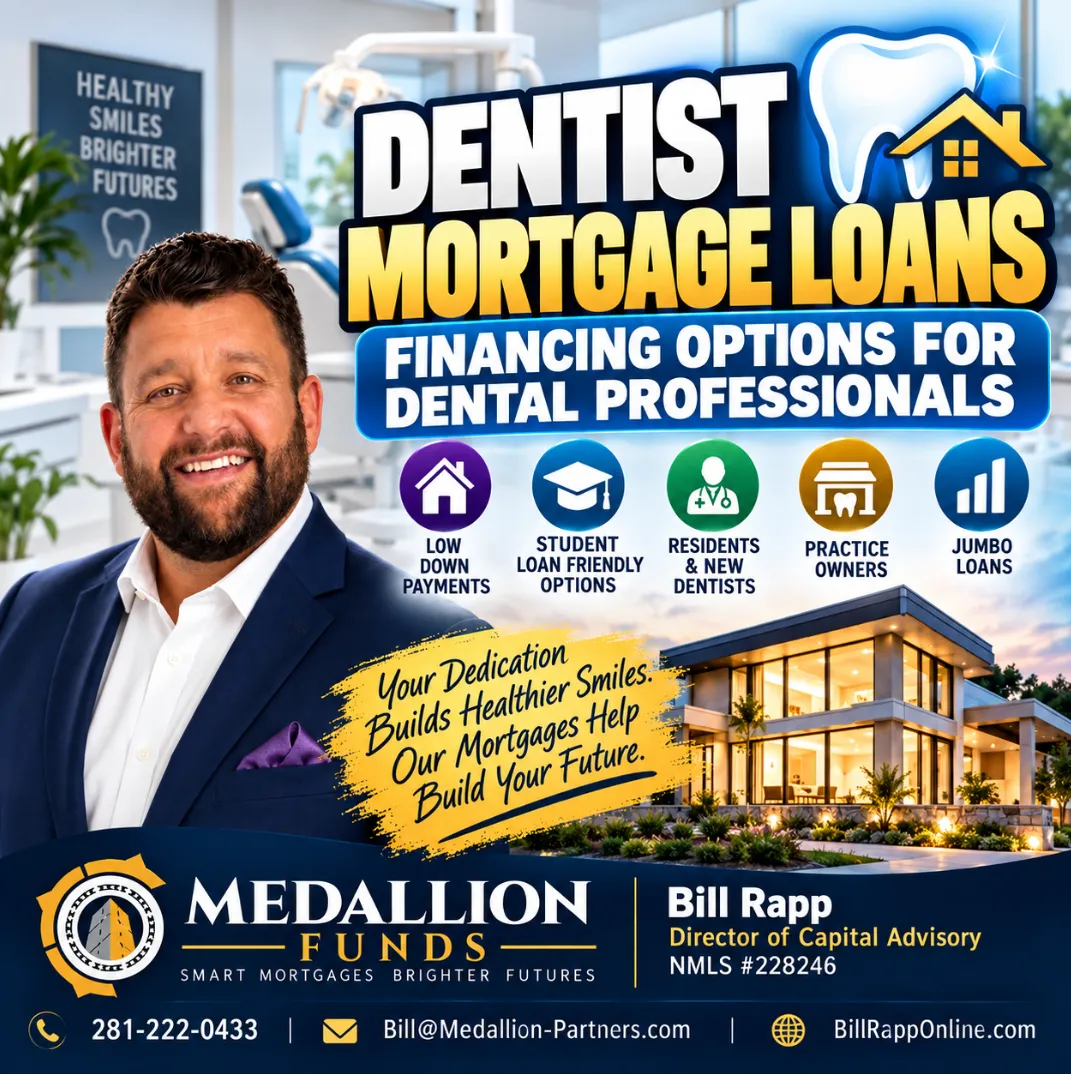
🦷🏡 Dentist Mortgage Loans: How Dental Professionals Can Finance a Home With Greater Flexibility 🔑
🦷🏡 Dentist Mortgage Loans: How Dental Professionals Can Finance a Home With Greater Flexibility 🔑
💰🦷 Dentist Home Loans Explained: Mortgage Options for Dentists, Residents & Practice Owners 🏠
________________________________________________________________________________
Dentist Mortgage Loans: Financing Options for Dental Professionals
Dentists often have a financial profile that looks very different from that of the typical homebuyer.
You may have substantial student loan debt, recently completed dental school or residency, be transitioning into private practice, or earn income through a combination of salary, bonuses, distributions, and business ownership.
On paper, those factors can make a conventional mortgage application more complicated.
That is where dentist mortgage loans and professional mortgage programs can potentially help.
At Medallion Funds, we help dental professionals evaluate mortgage options based on their career stage, income structure, assets, debts, and homeownership goals rather than assuming one mortgage program fits everyone.
Whether you're an associate dentist buying your first home, a specialist relocating for a new position, or an established practice owner looking for a jumbo mortgage, understanding your financing options can help you make a better decision.
What Is a Dentist Mortgage Loan?
A dentist mortgage loan generally refers to a mortgage program designed for dentists or other eligible medical professionals.
Depending on the lender and program, these loans may provide features such as:
·Higher loan amounts
·Lower down-payment options
·Different treatment of qualifying student loan debt
·More flexible consideration of employment contracts or future income
·Options designed for borrowers early in their professional careers
·Reduced or different mortgage-insurance requirements on certain programs
Eligibility, underwriting guidelines, loan limits, property requirements, and available benefits vary substantially by lender.
That last point matters.
There isn't one universal "dentist loan." Different lenders can have very different definitions of an eligible dental professional and very different underwriting requirements.
Why Dentists Can Face Mortgage Qualification Challenges
Dentists can earn excellent incomes while still presenting unusual underwriting challenges.
1. Student Loan Debt
Dental school can leave graduates with significant student loan balances.
Traditional mortgage underwriting may include a required monthly payment when calculating the borrower's debt-to-income ratio (DTI). How that payment is calculated depends on the mortgage program and loan guidelines.
Professional mortgage programs may treat qualifying student debt differently, making it important to compare programs rather than assuming a large student loan balance automatically prevents homeownership.
2. New Employment
A dentist may finish school, residency, or specialty training and immediately move into a substantially higher-paying position.
The challenge is that the borrower may not yet have years of income history at that new compensation level.
Some professional mortgage programs may allow eligible borrowers to qualify using an acceptable employment contract or offer letter, subject to the lender's guidelines and required documentation.
3. Practice Ownership
Established dentists frequently own all or part of their practices.
That creates another underwriting issue: self-employed income.
The amount appearing on a tax return isn't necessarily the same as the dentist's economic cash flow. Business deductions, depreciation, ownership distributions, and other factors can affect mortgage qualification.
Working with a mortgage professional who understands self-employed borrowers can therefore be especially important for dental practice owners.
Dentist Mortgage Loans vs. Conventional Mortgages
A dentist shouldn't automatically choose a dentist mortgage simply because one is available.
A conventional mortgage may still provide the better combination of interest rate, down payment, mortgage insurance, closing costs, and long-term economics.
The appropriate comparison may include:
Dentist/Professional Mortgage → Conventional → Jumbo → FHA → VA, when eligible → Other portfolio programs
Instead of asking only, "What is the lowest mortgage rate?", consider asking:
"Which financing structure gives me the best overall combination of cash-to-close, monthly payment, flexibility, and long-term cost?"
That's a much better mortgage question.
Can Dentists Get a Mortgage With Student Loans?
Potentially, yes.
Having student loans does not automatically prevent a dentist from qualifying for a mortgage.
However, student loans can influence the DTI calculation used during underwriting. The impact depends on the loan program, the documented payment, repayment status, and applicable underwriting rules.
This is one area where comparing multiple mortgage programs can be particularly valuable.
A borrower with a strong income but substantial dental-school debt could receive very different qualifying results depending on the program selected.
Mortgage Options for Dental Residents and New Dentists
Dentists early in their careers may benefit from exploring professional mortgage programs because their future earning potential can be considerably stronger than their historical income suggests.
For example, imagine a dentist completing specialty training and accepting a new position in another city.
They may have:
·Excellent professional earning potential
·A signed employment agreement
·Limited cash accumulated during training
·Significant student loans
·Little income history at their new salary
A standard underwriting approach may not always capture that financial trajectory effectively.
Certain professional mortgage programs are specifically designed with situations like these in mind.
Mortgage Options for Dental Practice Owners
Practice ownership creates a different set of considerations.
If you own a dental practice, mortgage underwriting may evaluate items such as:
·Personal tax returns
·Business tax returns
·K-1 income
·W-2 income from the practice
·Business ownership percentage
·Profit-and-loss statements
·Business liquidity
·Recurring versus nonrecurring expenses
·Existing business obligations
This makes pre-approval particularly important before shopping for a home.
Understanding how an underwriter will calculate your qualifying income before making an offer can reduce surprises later in the transaction.
Jumbo Mortgage Loans for Dentists
Successful dentists purchasing higher-priced homes may exceed conventional conforming loan limits.
That's where jumbo mortgage financing becomes relevant.
Jumbo underwriting can place greater emphasis on credit quality, liquidity, reserves, income stability, and the borrower's overall financial profile.
Dentists and practice owners may have strong net worth but hold a significant percentage of their assets inside their practice, retirement accounts, or investments.
A mortgage strategy should therefore consider more than the down payment.
It should also consider post-closing liquidity.
Putting substantially more money down isn't necessarily optimal if doing so leaves the borrower with inadequate liquidity for their practice, investments, emergencies, or other financial goals.
Buying a Home While Buying or Starting a Dental Practice
Dentists sometimes face two major financial decisions simultaneously:
Should I buy the home first—or acquire/start the dental practice first?
There isn't one answer for everyone.
Taking on new practice debt can affect personal mortgage qualification. Likewise, using substantial personal liquidity for a home purchase could reduce the capital available for a practice acquisition, expansion, or buildout.
The two transactions should therefore be considered together.
For dental professionals planning both, it may be beneficial to discuss the financing strategy before either transaction closes.
Questions Dentists Should Ask Before Choosing a Mortgage
Before selecting a mortgage, ask:
1.How will my student loans affect qualification?
2.Can my employment contract be considered?
3.How much do I actually need for a down payment?
4.Is mortgage insurance required?
5.How will my practice ownership affect qualifying income?
6.What cash reserves will I need after closing?
7.Would a conventional or jumbo mortgage be less expensive?
8.Are there restrictions associated with the professional mortgage program?
9.How will an upcoming practice purchase affect qualification?
10.What is the total cost of the financing—not simply the advertised rate?
These questions can uncover differences that aren't obvious from an interest-rate quote.
Why Work With a Mortgage Broker?
Dentists have complex financial profiles, and that's precisely where a mortgage broker can add value.
Rather than beginning with one loan product, the process should begin with the borrower.
At Medallion Funds, we can evaluate the circumstances surrounding your income, student debt, employment, practice ownership, liquidity, property, and financial objectives and then determine which available mortgage structures warrant consideration.
The objective isn't simply to get a mortgage.
It's to find a financing strategy that fits your broader financial picture.
Ready to Explore Your Dentist Mortgage Options?
Whether you're graduating from dental school, completing a residency, joining a practice, buying into a practice, relocating, or purchasing your next home, consider reviewing your mortgage options before you start making offers.
Bill Rapp
Partner & Director of Capital Advisory | Medallion Funds
Commercial Lending Nationwide
Residential Lending in AL, CA, CO, NV & TXBottom of Form
https://www.billrapponline.com/
https://findamortgagebroker.com/Profile/WilliamRappJr28883
https://billrapp.commloan.com/
https://billrapponline.com/financingfuturescre-houston-katy
https://houstoncommercialmortgage.com/
https://author.billrapponline.com
https://doctorvideo.billrapponline.com/
https://veteransvideo.billrapponline.com/
https://mortgageviking.billrapponline.com/
https://fha203h.billrapponline.com/
https://renovationvideo.billrapponline.com
https://medallionfunds.com/bill-rapp/
https://www.amazon.com/dp/B0F32Z5BH2
https://veed.cello.so/FOmzTty6oi9
https://buymeacoffee.com/vikingente3
https://creplaybookseries.billrapponline.com
https://creplaybook.billrapponline.com/
© Bill Rapp, Medallion Funds LLC, Director of Capital Advisory
10 Tips for First-Time Homebuyers
Buying your first home can be both exciting and nerve-wracking at the same time. With so many things to consider and....
How To Choose the Right Lender for You
Lorem Ipsum is simply dummy text of the printing and typesetting industry. Lorem Ipsum has been the industry's standard dummy
Refinancing youe loan and when to do it
Lorem Ipsum is simply dummy text of the printing and typesetting industry. Lorem Ipsum has been the industry's standard dummy
Copyright ©2021 | Mortgage Viking Team
Licensed to Do Business | NMLS # 228246
This is not an offer to enter into an agreement. Not all customers will qualify. Information, rates and programs are subject to change without notice. All products are subject to credit and property approval. Other restrictions and limitations may apply. Copyright © 2021 | Medallion Funds
Corporate | NMLS ID NMLS # 1825831
Corporate Address : 2651 N. Green Valley Pkwy STE. 101 Henderson, NV 89014
Corporate NMLS NMLS # 1825831 | Company Website: https://medallionfunds.com/bill-rapp/
Copyright ©2021 | Mortgage Viking Team Licensed to Do Business | NMLS # 228246
This is not an offer to enter into an agreement. Not all customers will qualify. Information, rates and programs are subject to change without notice. All products are subject to credit and property approval. Other restrictions and limitations may apply
Corporate | NMLS ID NMLS # 1825831
Corporate Address : 2651 N. Green Valley Pkwy STE. 101 Henderson, NV 89014 https://medallionfunds.com/bill-rapp/
Facebook
Instagram
X
LinkedIn
Youtube
TikTok