Low Rates.
Our rates are low, our application is quick and easy! We can get you clear to close in as little as 10 days!
Trusted By Agents With
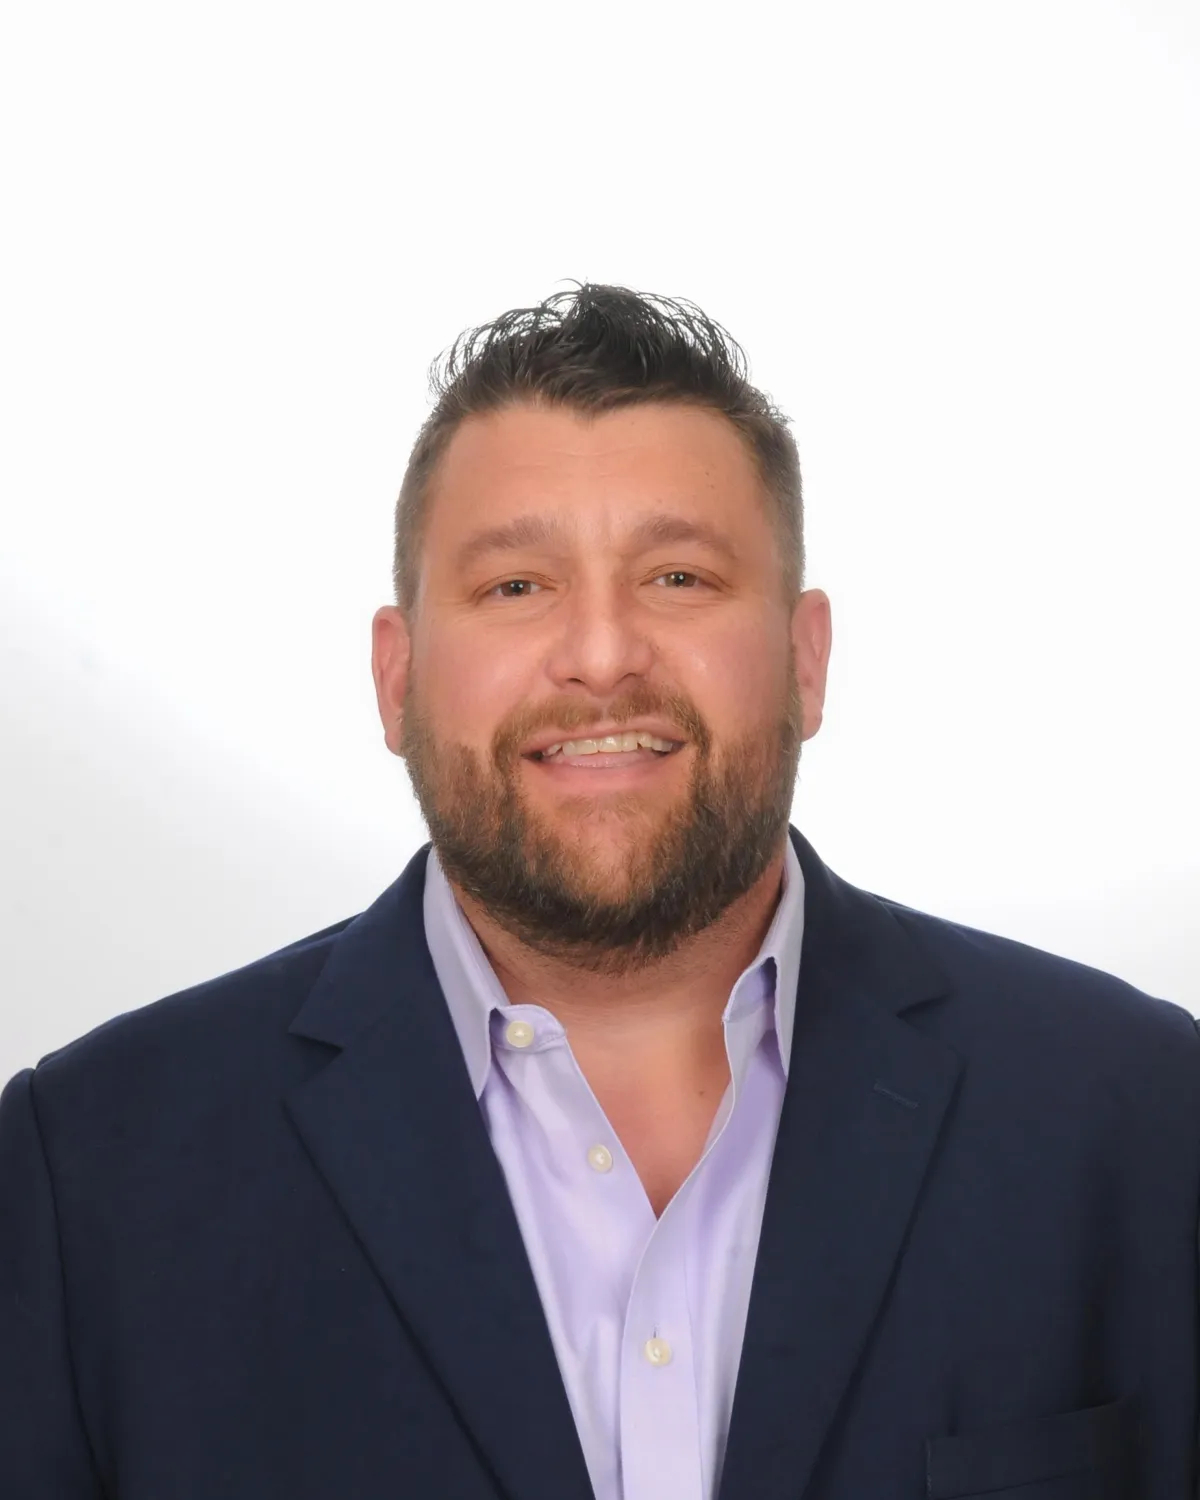
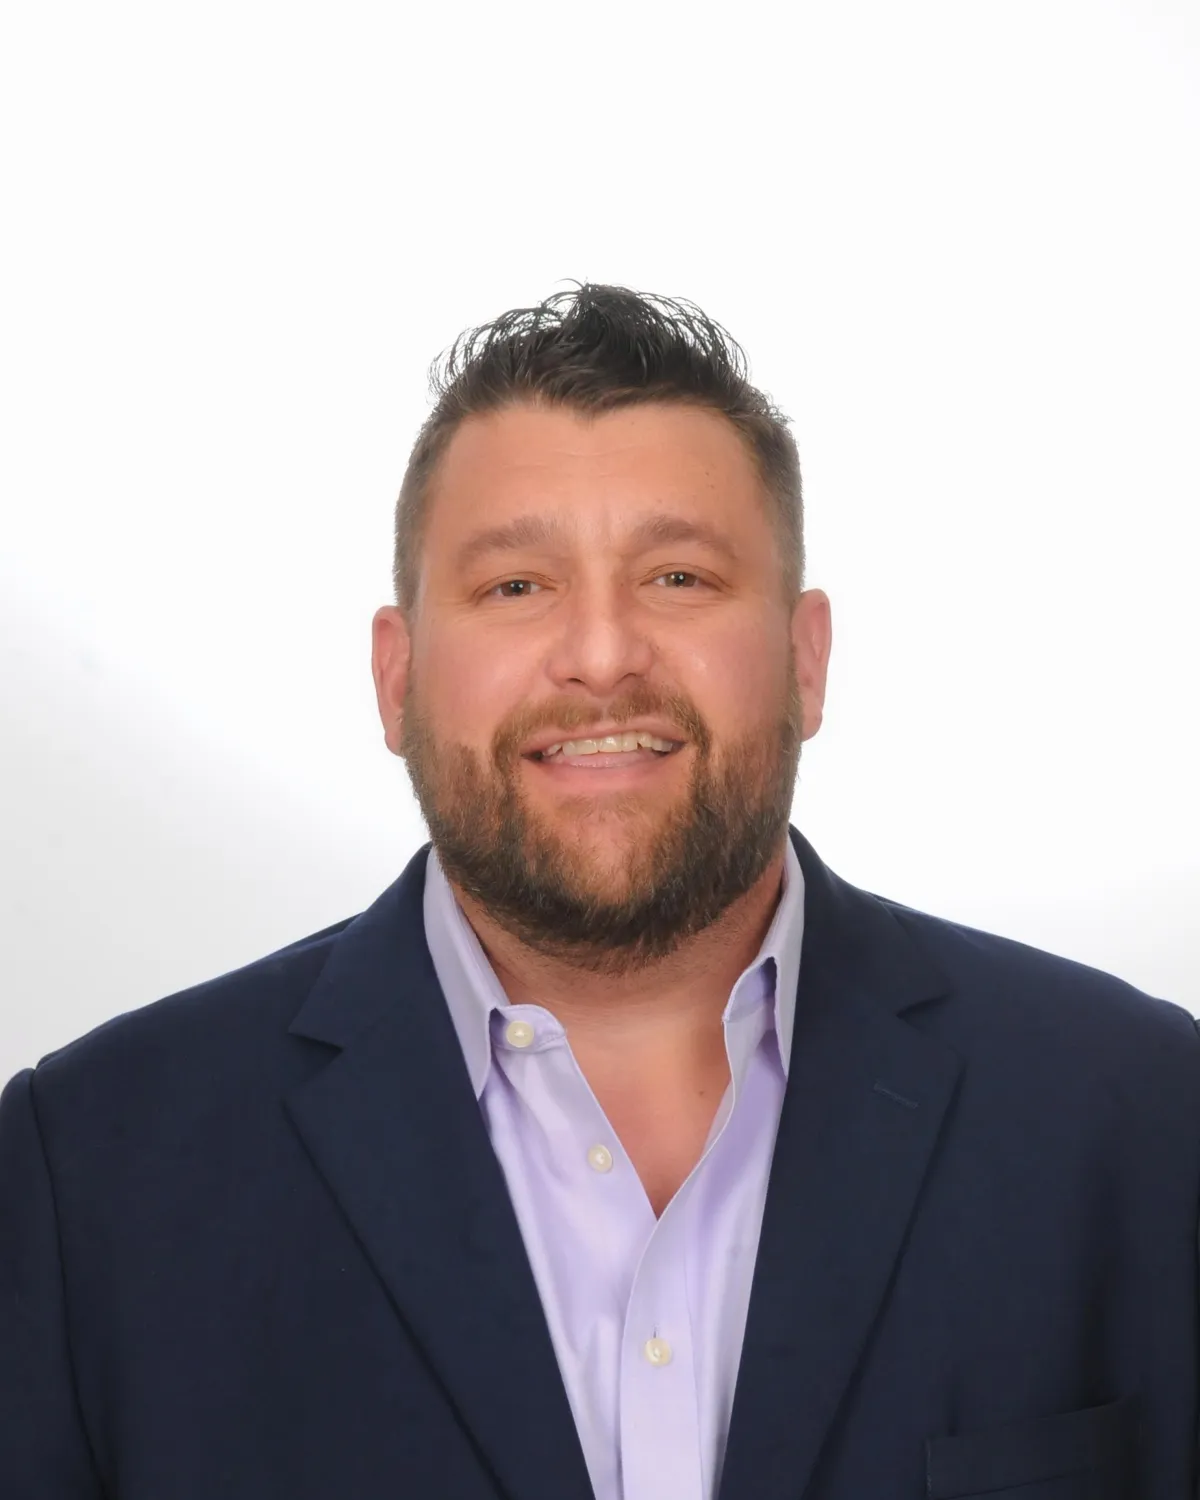
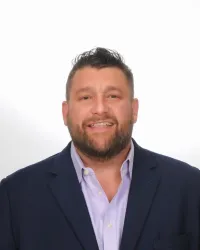
Meet Bill Rapp
NMLS ID # NMLS # 228246
Bill Rapp, CCIM is a Houston-based Capital Advisor at Medallion Funds, specializing in commercial real estate finance and strategic lending solutions. With over two decades of experience across brokerage and capital markets, Bill has worked with leading firms including eXp Commercial, NEXA Mortgage, Viking Enterprise LLC, and Sun Realty Houston.
A graduate of Texas A&M University with a BBA in Finance, Bill brings a disciplined, underwriting-first approach to every deal. His expertise spans commercial and residential financing, including asset-based lending, FHA financing, reverse mortgages, REO properties, and investment strategies for both single-family and commercial assets.
Known for his focus on structure over rate, Bill helps investors, business owners, and developers navigate complex transactions with clarity, precision, and a long-term wealth-building mindset.
The Client Experience
Great experience purchasing our first home! Bill was easy to reach and always able to answer any questions or concerns.

Loan Programs Available


Blogs
The Top 5 Mortgage Mistakes to Avoid
Buying your first home can be both exciting and nerve-wracking at the same time. With so many things to consider and....
Mortgage Do and
Do not list
Mortgages can be tricky, and it's easy to make mistakes that can end up costing you dearly. That's why we've put together this list....
Tips On How To Improve Your Credit Score
Let's talk about some ways you can improve your credit score! Your credit score is actually a big deal, and it can affect...
🦷 Dental Mortgage Loans: Dentist Homebuyer Guide 🏡
🦷 Dental Mortgage Loans: Dentist Homebuyer Guide 🏡
🏠 Dentist Mortgage Loans: Low Down Payment Options 🦷
_____________________________________________________________________________
🦷 Dental Mortgage Loans: The Complete Guide for Dentists and Dental Specialists
You spent years investing in your education and building your dental career. Shouldn't your mortgage recognize your earning potential?
For many dentists and dental specialists, buying a home presents a unique financial challenge.
You may earn a substantial income, have excellent long-term career prospects, and maintain strong credit. Yet traditional mortgage underwriting may not fully accommodate your circumstances.
Perhaps you're graduating from dental school with significant student loan debt. Maybe you're completing an orthodontic residency, joining a group practice, purchasing your first dental office, or transitioning into practice ownership.
Whatever your situation, dental mortgage loans and specialized dentist home financing programs may provide options that conventional mortgage guidelines cannot offer.
At Medallion Funds, we help dental professionals explore financing strategies tailored to their income, student debt, career transitions, and homeownership goals.
I'm Bill Rapp, CCIM, a mortgage and capital advisor with more than two decades of real estate and finance experience. My objective is straightforward: help you understand your options before making one of your largest financial commitments.
What Is a Dental Mortgage Loan?
A dental mortgage loan, sometimes called a dentist mortgage or physician-style mortgage for dentists, is a home financing program designed to accommodate the financial circumstances of eligible dental professionals.
Unlike a single standardized government-backed mortgage product, dentist mortgage programs are generally specialized offerings from participating banks and mortgage lenders.
Depending on the lender, they may provide:
·Low down payment options, potentially including 0% down for qualified borrowers.
·No monthly private mortgage insurance (PMI).
·Alternative treatment of student loan obligations.
·Eligibility using qualifying employment contracts or offer letters.
·Higher loan limits for eligible applicants.
·Flexibility for residents, fellows, and newly practicing dentists.
Important: These features are lender-specific. Not every dentist mortgage program offers all of them, and qualification depends on credit, income, debt obligations, property type, and other underwriting criteria.
Who Qualifies for Dentist Mortgage Programs?
Specialized dentist mortgage programs may be available to a broader range of dental professionals than many borrowers realize.
Dental profession | Potential financing consideration |
General dentists (DDS/DMD) | Professional income and student debt |
Orthodontists | Residency transitions and projected employment income |
Oral and maxillofacial surgeons | High loan amounts and specialty income |
Endodontists | Associate compensation and practice ownership |
Periodontists | Self-employment and business income |
Pediatric dentists | Early-career eligibility |
Prosthodontists | High-income and jumbo financing |
Dental residents and fellows | Employment contracts and future earnings |
Eligibility varies. Some programs restrict participation to specific professional degrees, employment arrangements, career stages, or licensing status.
1. Can Dentists Buy a Home With 0% Down?
One of the most attractive potential benefits of specialized dental mortgage loans is reduced upfront cash requirements.
Traditional conventional financing may require a down payment as low as 3% for eligible borrowers. Certain physician-style programs may offer even greater flexibility to qualified dentists.
Consider a $750,000 home purchase.
Illustrative down payment comparison
$0
0% down
Specialized program
$37,500
5% down
Low-down-payment loan
$150,000
20% down
Traditional benchmark
Illustration only. Actual program availability, rates, loan limits, closing costs, and qualification requirements vary.
A 0% down program could allow a qualifying dentist to preserve $150,000 compared with a 20% down payment.
That capital might otherwise be needed for practice acquisition expenses, equipment, emergency reserves, or long-term investments.
However, a smaller down payment also means a larger loan balance, potentially higher monthly payments, and greater exposure to home-price declines.
The goal is not necessarily to make the smallest down payment. It is to select the mortgage structure that best fits your financial plan.
2. How Dental School Student Loans Affect Mortgage Approval
Dental education can be expensive. Many dentists begin their careers with significant student loan balances.
Fortunately, having student debt does not automatically prevent mortgage qualification.
Lenders generally evaluate your debt-to-income ratio (DTI), which compares qualifying monthly debt payments with gross monthly income.
\[ \text{DTI}=\frac{\text{Monthly Debt Payments}}{\text{Gross Monthly Income}}\times100 \]
Consider a dentist earning $240,000 annually.
Example: Student debt and mortgage qualification
Gross monthly income | $20,000 |
Proposed housing payment (PITI) | $5,500 |
Student loan payment | $1,500 |
Other monthly debts | $500 |
Total monthly obligations | $7,500 |
Debt-to-income ratio | 37.5% |
That 37.5% DTI may fall within acceptable guidelines for some mortgage programs, subject to the full underwriting review.
Certain dentist mortgage lenders may use alternative student loan calculations when a borrower has an income-driven repayment plan or qualifying deferred obligations.
However, lenders do not universally exclude student loans. The treatment of deferred or income-driven payments depends on the specific program and its current underwriting requirements.
Before applying, ask how each lender calculates your student loan payments. This single detail can materially affect your borrowing capacity.
3. Can Dental Residents and New Graduates Qualify?
A common misconception is that dentists must establish several years of employment before purchasing a home.
Some specialized mortgage programs allow eligible dental graduates, residents, and newly employed dentists to qualify using documented future employment income.
A lender may consider a signed employment contract specifying salary, start date, and employment conditions.
For example, an orthodontist completing residency might receive an employment offer with a $275,000 annual base salary.
A participating lender may be able to consider that contract before the orthodontist receives the first paycheck, subject to the lender's employment-start, verification, reserve, and underwriting requirements.
This can be especially valuable for dental professionals relocating for a new position.
Not every contract qualifies. Commission-only compensation, variable production bonuses, and independent contractor arrangements may require additional documentation or a longer income history.
4. Dentist Mortgage Loans vs. Conventional and Jumbo Mortgages
A specialized dental mortgage is not automatically the best choice.
Dentists should compare several financing options rather than assuming their professional designation guarantees the most competitive terms.
Loan feature | Dentist mortgage | Conventional mortgage | Jumbo mortgage |
Low down payment | Potentially 0–5% | As low as 3% for eligible borrowers | Lender-specific |
Monthly PMI | May be waived | Generally required below 20% down, subject to exceptions | Often not required |
Student debt flexibility | May offer specialized treatment | Standard program rules | Lender-specific |
Employment contract income | May be accepted | Possible under qualifying guidelines | Lender-specific |
Loan amount | Program-dependent | Conforming limits apply | Above conforming limits |
Interest rate | Lender-specific | Market and borrower dependent | Market and borrower dependent |
A no-PMI dentist mortgage may still have a higher interest rate or different fees than a competing conventional loan.
Compare the annual percentage rate (APR), estimated cash to close, total monthly housing expense, reserves, and expected cost over your anticipated ownership period.
5. Mortgage Options for Self-Employed Dentists and Practice Owners
Dental practice owners face additional underwriting considerations.
A dentist earning $350,000 in practice revenue or owner distributions may not necessarily qualify using that amount as personal mortgage income.
Traditional lenders commonly evaluate tax returns, qualifying business income, add-backs, business liabilities, and income stability.
This creates challenges for dentists who:
·Recently purchased an existing practice.
·Opened a new dental office.
·Have substantial equipment financing.
·Claim legitimate business deductions.
·Receive income through an S corporation, partnership, or professional entity.
In these situations, alternative mortgage products may be worth reviewing.
Bank statement loans may use eligible personal or business bank deposits to establish qualifying income, subject to expense factors and lender requirements.
Non-QM mortgages may offer alternative income documentation or underwriting approaches, typically with different pricing and down payment requirements.
Jumbo mortgages may suit established dental specialists seeking higher-priced primary residences.
These options can help address documentation challenges, but they do not eliminate the lender's obligation to evaluate repayment capacity.
6. Should You Buy a Home Before Buying a Dental Practice?
This is one of the most important financial planning questions for an aspiring dental practice owner.
Imagine you're an associate dentist planning to purchase a $1.2 million practice within the next 18 months.
You also want to buy an $850,000 home.
Both transactions may be feasible individually, but the order can affect your liquidity, debt obligations, credit profile, and financing eligibility.
Buying a home first could reduce available capital for practice acquisition.
Purchasing the practice first could create a new self-employment income history that complicates residential mortgage qualification.
The right sequence depends on your financial position, financing terms, and business plans.
A coordinated strategy involving your mortgage advisor, commercial lender, CPA, and practice acquisition advisors can help identify conflicts before they arise.
At Medallion Funds, our broader capital advisory experience allows us to discuss both residential mortgage considerations and financing needs associated with dental practice ownership.
Residential and commercial financing remain separate transactions, with distinct underwriting requirements.
7. How Much House Can a Dentist Afford?
A lender's maximum approval amount is not necessarily your ideal housing budget.
Dental professionals should account for expenses that may not appear in a standard mortgage calculator.
These include professional liability coverage, continuing education, student loans, practice investment requirements, retirement contributions, and variable compensation.
A more useful affordability analysis considers:
\[ \text{Housing Budget} = \text{Sustainable Cash Flow} - \text{Other Financial Commitments} \]
Rather than relying exclusively on gross income, evaluate the monthly payment against actual after-tax cash flow and financial priorities.
Interactive dentist mortgage payment example
Estimated monthly housing payment
$5,928/mo
Principal, interest, estimated property taxes and insurance
Principal & interest $4,503
Taxes $1,125
Insurance $300
Home purchase price
$750,000
Down payment
5%
Illustrative interest rate
6.50%
Annual property tax rate1.8%
Monthly insurance$300
Loan amount
$712,500
Down payment cash
$37,500
Educational estimate based on a 30-year fixed-rate amortization. Rate is hypothetical, not a current lender quote. Excludes PMI, HOA dues, closing costs, maintenance, and potential additional taxes or insurance expenses. Actual lender pricing and qualifications vary.
8. How to Apply for a Dental Mortgage Loan
The process typically begins with a conversation about your career stage and financial objectives.
A mortgage advisor will generally review your professional credentials, employment or practice ownership, credit history, income documentation, student loans, and available assets.
For dental practice owners, additional tax returns and business financial statements may be required.
Once the preliminary review is complete, compare eligible financing programs before selecting a loan structure and moving toward formal preapproval.
A useful question to ask your lender: Do you offer a dedicated dentist mortgage program, and how does it compare with your conventional, jumbo, and alternative-documentation options?
9. Frequently Asked Questions About Dental Mortgage Loans
Can dentists qualify for a mortgage with no down payment?
Potentially. Certain specialized lender programs may offer 100% financing to eligible dental professionals, subject to loan amount, credit, employment, and other criteria.
Do dentist mortgages require PMI?
Some programs waive monthly PMI even with less than 20% down. This does not guarantee a lower overall borrowing cost.
Can dental residents purchase a home?
Some programs allow residents and newly graduating dentists to qualify with acceptable employment documentation or contracts.
Are orthodontists and oral surgeons eligible?
They may be eligible for specialized professional mortgage programs, depending on the lender's approved occupations and degree requirements.
Can a dentist qualify with $300,000 in student loan debt?
Possibly. The balance alone does not determine eligibility. The lender's qualifying monthly payment calculation, income, credit, and other debts matter.
Can self-employed dentists get a mortgage?
Yes. Conventional, jumbo, bank statement, and other eligible programs may be available, depending on documented income and the lender's guidelines.
Can a dentist use a professional mortgage to purchase an office building?
A residential dentist mortgage is generally intended for eligible residential property purchases, not commercial practice real estate. Dental office acquisitions typically require separate commercial financing.
Final Thoughts: Your Dental Career Deserves a Thoughtful Mortgage Strategy
A dentist's financial profile often looks different from that of a traditional salaried employee.
Student debt, residency income, practice ownership, production-based compensation, and substantial future earning potential all create unique considerations.
That is why comparing specialized dental mortgage loans with conventional, jumbo, and alternative financing options can be valuable.
The best mortgage is not necessarily the one offering the largest loan or smallest down payment. It is the one that supports your homeownership goals without undermining your long-term financial position.
Ready to Explore Your Dental Mortgage Options?
Contact Bill Rapp, CCIM, at Medallion Funds to discuss home financing for dentists, dental specialists, residents, and practice owners.
Bill Rapp
Partner & Director of Capital Advisory | Medallion Funds
Commercial Lending Nationwide
Residential Lending in AL, CA, CO, NV & TXBottom of Form
📞 Call or Text: 281-222-0433
🌐 Website: https://billrapponline.com
🎥 Subscribe to Mortgage Viking: https://www.youtube.com/@billrapp-medallion-funds
https://www.billrapponline.com/
https://findamortgagebroker.com/Profile/WilliamRappJr28883
https://billrapp.commloan.com/
https://billrapponline.com/financingfuturescre-houston-katy
https://houstoncommercialmortgage.com/
https://author.billrapponline.com
https://doctorvideo.billrapponline.com/
https://veteransvideo.billrapponline.com/
https://mortgageviking.billrapponline.com/
https://fha203h.billrapponline.com/
https://renovationvideo.billrapponline.com
https://medallionfunds.com/bill-rapp/
https://www.amazon.com/dp/B0F32Z5BH2
https://veed.cello.so/FOmzTty6oi9
https://buymeacoffee.com/vikingente3
https://creplaybookseries.billrapponline.com
https://creplaybook.billrapponline.com/
© Bill Rapp, Medallion Funds LLC, Director of Capital Advisory
10 Tips for First-Time Homebuyers
Buying your first home can be both exciting and nerve-wracking at the same time. With so many things to consider and....
How To Choose the Right Lender for You
Lorem Ipsum is simply dummy text of the printing and typesetting industry. Lorem Ipsum has been the industry's standard dummy
Refinancing youe loan and when to do it
Lorem Ipsum is simply dummy text of the printing and typesetting industry. Lorem Ipsum has been the industry's standard dummy
Copyright ©2021 | Mortgage Viking Team
Licensed to Do Business | NMLS # 228246
This is not an offer to enter into an agreement. Not all customers will qualify. Information, rates and programs are subject to change without notice. All products are subject to credit and property approval. Other restrictions and limitations may apply. Copyright © 2021 | Medallion Funds
Corporate | NMLS ID NMLS # 1825831
Corporate Address : 2651 N. Green Valley Pkwy STE. 101 Henderson, NV 89014
Corporate NMLS NMLS # 1825831 | Company Website: https://medallionfunds.com/bill-rapp/
Copyright ©2021 | Mortgage Viking Team Licensed to Do Business | NMLS # 228246
This is not an offer to enter into an agreement. Not all customers will qualify. Information, rates and programs are subject to change without notice. All products are subject to credit and property approval. Other restrictions and limitations may apply
Corporate | NMLS ID NMLS # 1825831
Corporate Address : 2651 N. Green Valley Pkwy STE. 101 Henderson, NV 89014 https://medallionfunds.com/bill-rapp/
Facebook
Instagram
X
LinkedIn
Youtube
TikTok