Low Rates.
Our rates are low, our application is quick and easy! We can get you clear to close in as little as 10 days!
Trusted By Agents With
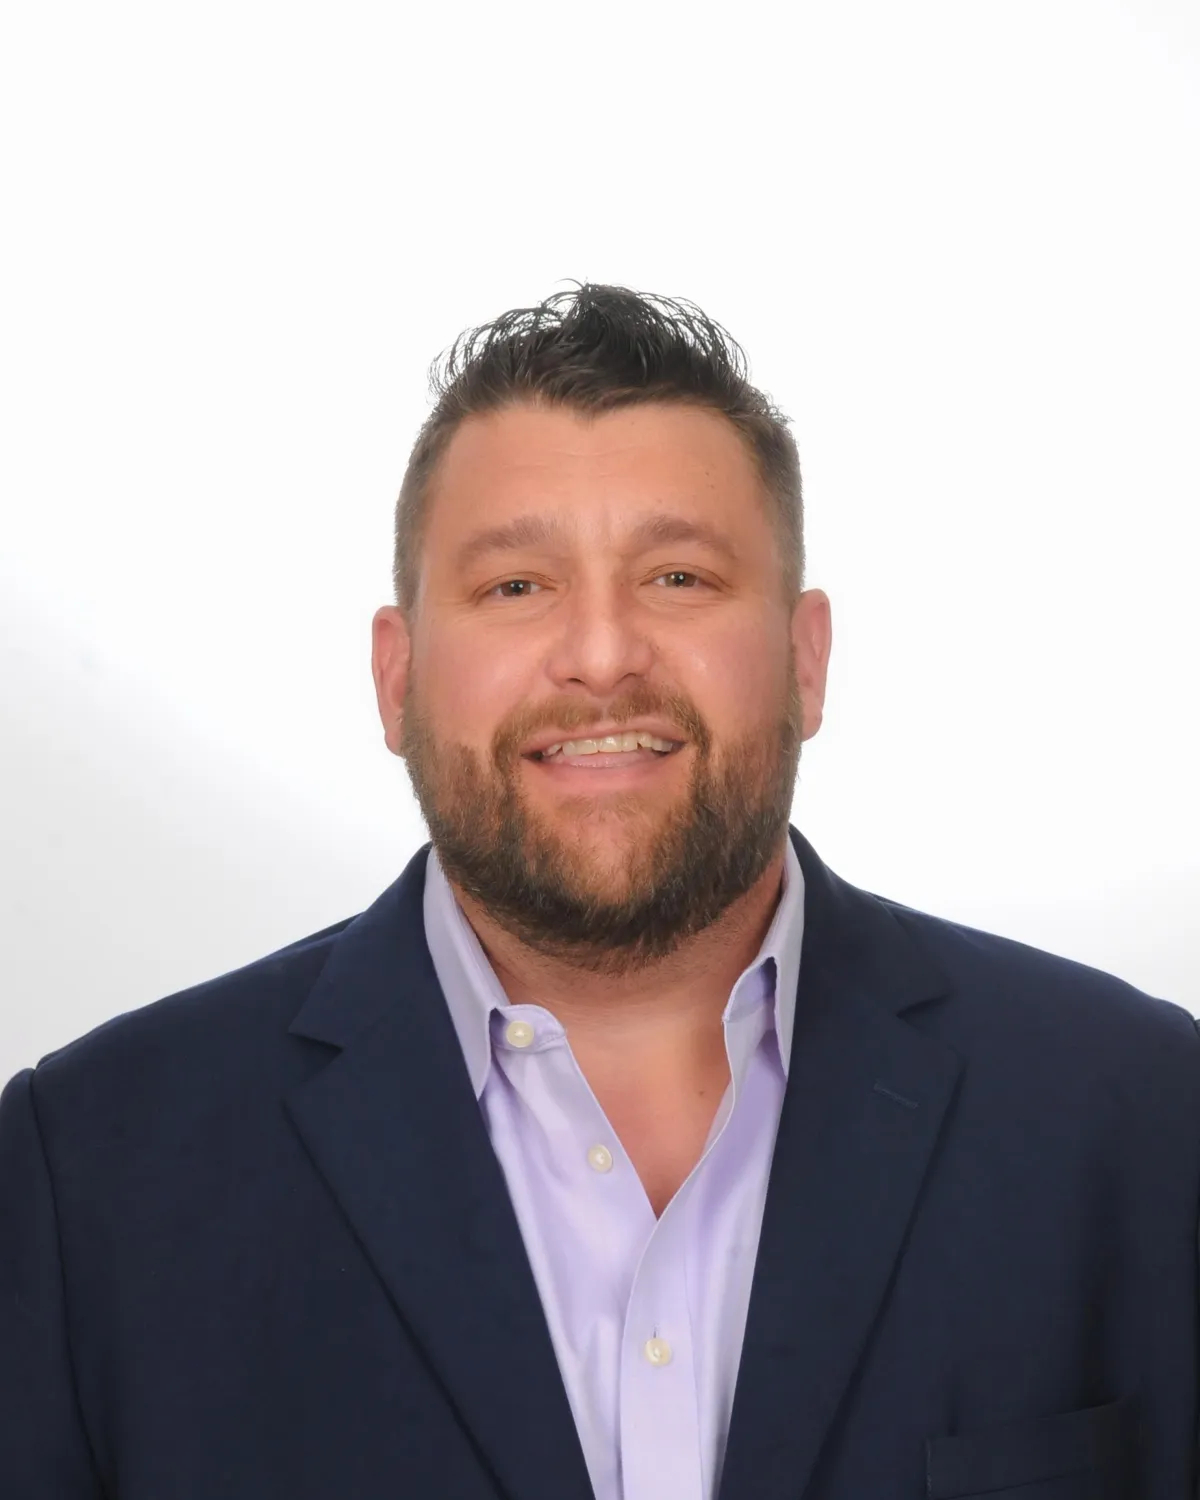
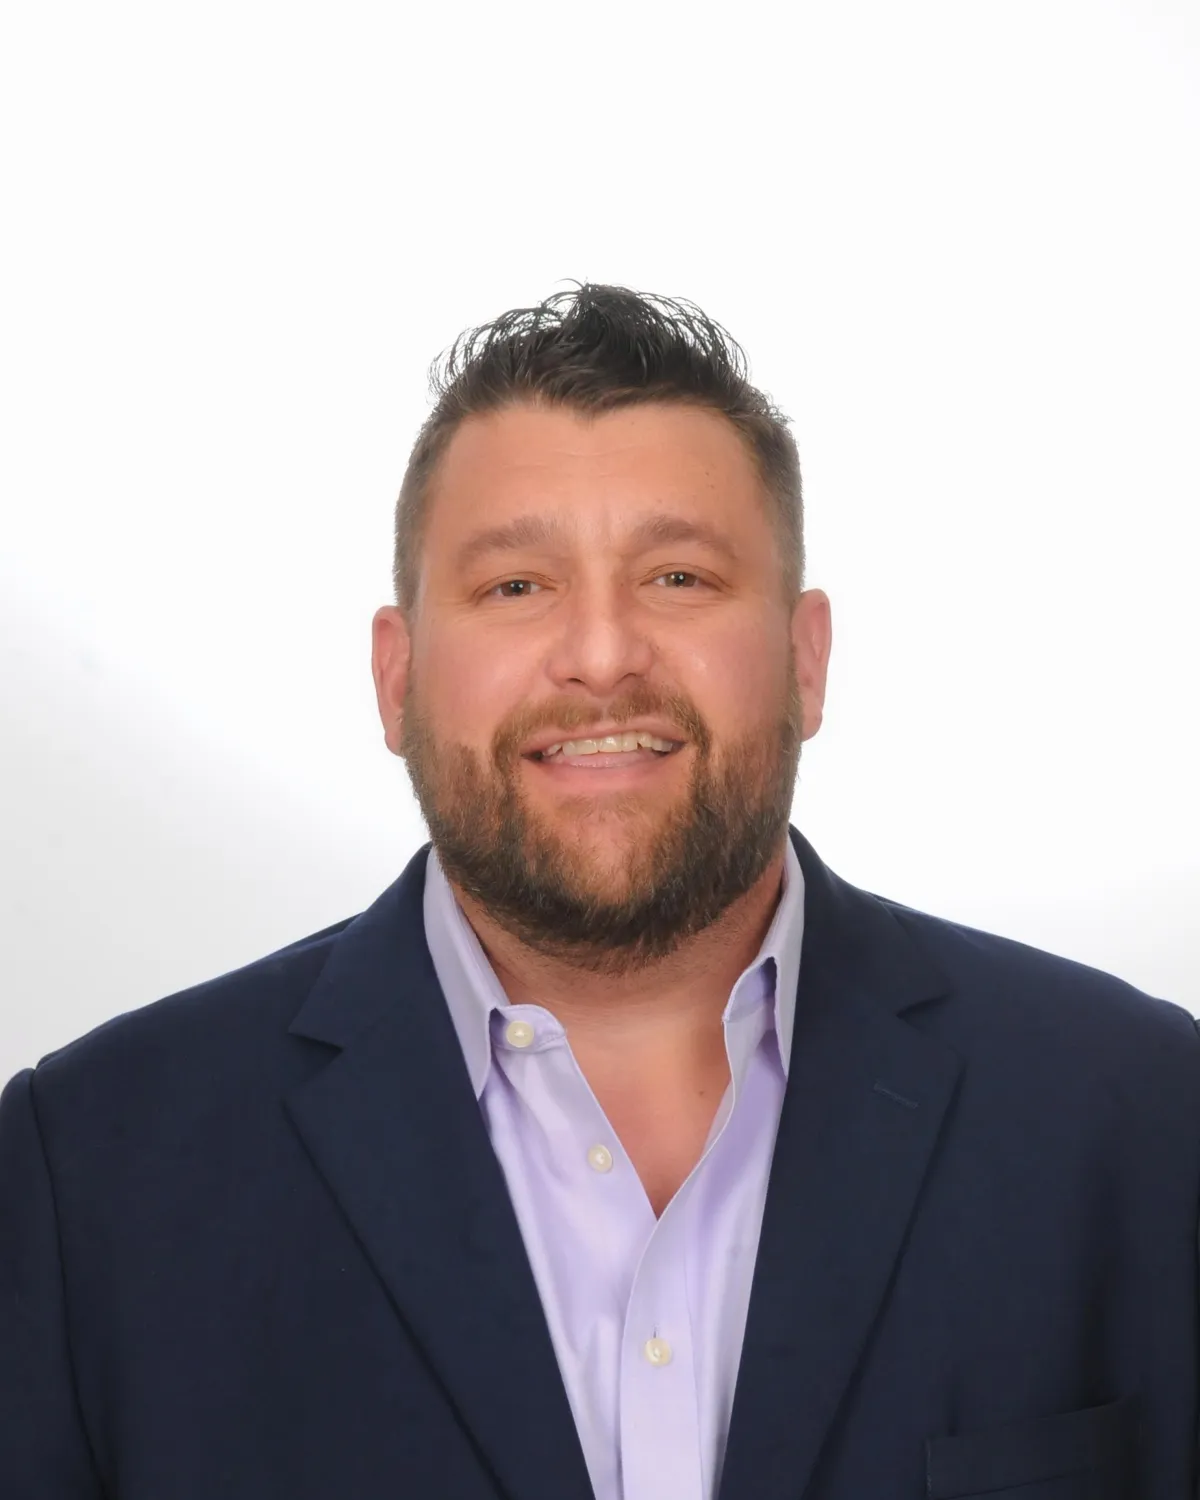
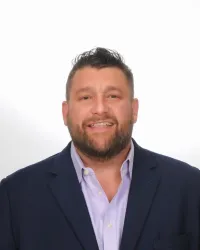
Meet Bill Rapp
NMLS ID # NMLS # 228246
Bill Rapp, CCIM is a Houston-based Capital Advisor at Medallion Funds, specializing in commercial real estate finance and strategic lending solutions. With over two decades of experience across brokerage and capital markets, Bill has worked with leading firms including eXp Commercial, NEXA Mortgage, Viking Enterprise LLC, and Sun Realty Houston.
A graduate of Texas A&M University with a BBA in Finance, Bill brings a disciplined, underwriting-first approach to every deal. His expertise spans commercial and residential financing, including asset-based lending, FHA financing, reverse mortgages, REO properties, and investment strategies for both single-family and commercial assets.
Known for his focus on structure over rate, Bill helps investors, business owners, and developers navigate complex transactions with clarity, precision, and a long-term wealth-building mindset.
The Client Experience
Great experience purchasing our first home! Bill was easy to reach and always able to answer any questions or concerns.

Loan Programs Available


Blogs
The Top 5 Mortgage Mistakes to Avoid
Buying your first home can be both exciting and nerve-wracking at the same time. With so many things to consider and....
Mortgage Do and
Do not list
Mortgages can be tricky, and it's easy to make mistakes that can end up costing you dearly. That's why we've put together this list....
Tips On How To Improve Your Credit Score
Let's talk about some ways you can improve your credit score! Your credit score is actually a big deal, and it can affect...
🏢 What Is Debt Yield in Commercial Real Estate? 💰
🏢 What Is Debt Yield in Commercial Real Estate? 💰
💰 Debt Yield: The Metric That Limits Your CRE Loan! 🏢
________________________________________________________________________________
What Is Debt Yield in Commercial Real Estate? How Lenders Determine Your Maximum Loan
When applying for a commercial real estate loan, most investors focus on interest rates, loan-to-value ratios, and monthly mortgage payments.
But there's another critical lending metric that could determine how much money you can actually borrow: debt yield.
Even if your property has strong cash flow, a favorable appraisal, and an acceptable debt service coverage ratio, your lender may reduce your loan amount because of its debt yield requirements.
Understanding debt yield in commercial real estate lending can help investors structure acquisitions, evaluate refinancing opportunities, negotiate financing terms, and avoid unexpected equity requirements at closing.
I'm Bill Rapp, CCIM, with CommLoan, and in this guide, I'll explain how debt yield works, why commercial mortgage lenders use it, and how you can use it to make smarter real estate investment decisions.
What Is Debt Yield in Commercial Real Estate?
Debt yield is a commercial real estate underwriting metric that measures a property's annual net operating income relative to the outstanding or proposed loan amount.
It helps lenders evaluate the income generated by a property in relation to their capital exposure.
Unlike debt service coverage ratio, debt yield does not directly depend on the loan's interest rate, amortization period, or monthly mortgage payment.
Unlike loan-to-value ratio, debt yield does not depend directly on the property's appraised value.
Instead, it answers a straightforward question:
How much annual operating income does this property generate relative to the amount of money the lender is financing?
A higher debt yield generally indicates stronger income coverage relative to the lender's loan exposure.
How to Calculate Debt Yield
The debt yield formula is:
Debt Yield = Annual Net Operating Income ÷ Loan Amount × 100
For example, suppose you are purchasing a commercial property with the following financial characteristics:
Purchase price: $5,000,000
Annual net operating income: $400,000
Requested commercial mortgage: $3,750,000
Your debt yield would be:
$400,000 ÷ $3,750,000 = 10.67%
The property generates annual net operating income equal to approximately 10.67% of the proposed loan balance.
This does not mean the lender earns a 10.67% interest rate. Debt yield is an underwriting measure of income relative to loan principal, not the lender's actual investment return.
Why Do Commercial Mortgage Lenders Use Debt Yield?
Commercial mortgage lenders use debt yield because it provides an additional way to evaluate credit risk without relying directly on interest rates or appraised property values.
Consider what happens when commercial real estate interest rates decline.
Lower interest rates can reduce annual debt service, allowing a property to qualify for a larger loan under traditional DSCR underwriting.
However, the property's actual operating income may not have increased.
Similarly, if commercial real estate values rise because capitalization rates compress, a lender relying heavily on loan-to-value calculations might approve a larger mortgage even though the property's income remains unchanged.
Debt yield helps lenders manage these risks by tying loan proceeds directly to property income.
It is particularly useful when evaluating:
Commercial mortgage-backed securities, or CMBS loans
Multifamily property financing
Industrial and warehouse loans
Retail shopping center mortgages
Office building financing
Hotel and hospitality loans
Commercial real estate refinancing
Bridge and transitional property financing
Not every lender uses debt yield in the same way. Some apply a strict minimum threshold, while others use it as one component of their broader credit analysis.
What Is a Good Debt Yield in Commercial Real Estate?
Many commercial real estate lenders evaluate debt yields in the approximate range of 8% to 12%, although requirements vary significantly depending on the property type, loan program, market, and lender's risk tolerance.
Illustrative underwriting thresholds might include:
Debt Yield | General Interpretation |
Below 8% | Higher leverage or weaker income relative to debt |
8%–10% | May be acceptable for certain stabilized properties |
10%–12% | Stronger income relative to loan exposure |
Above 12% | More conservative leverage, assuming reliable NOI |
These ranges are illustrative, not universal lending requirements.
A lender may accept a lower debt yield for a well-located, stabilized multifamily property with consistent occupancy and strong market fundamentals.
Conversely, a lender financing a hotel, transitional office building, or property with significant tenant rollover may require a higher debt yield.
The quality and durability of the property's income matter just as much as the calculated percentage.
Debt Yield vs. DSCR vs. LTV
Commercial mortgage lenders commonly evaluate three important underwriting metrics: debt yield, debt service coverage ratio, and loan-to-value ratio.
Each measures a different aspect of lending risk.
Debt Yield
Debt yield measures annual net operating income relative to the loan amount.
Formula: NOI ÷ Loan Amount
It helps determine whether the property's income supports the lender's overall capital exposure.
Debt Service Coverage Ratio (DSCR)
DSCR measures whether a property's net operating income can cover its annual mortgage payments.
Formula: NOI ÷ Annual Debt Service
For example, if a property generates $400,000 in annual NOI and has annual debt service of $320,000, its DSCR is 1.25x.
Many commercial lenders look for a DSCR of approximately 1.20x to 1.35x or higher, depending on the loan program and property risk.
Loan-to-Value Ratio (LTV)
LTV measures the loan amount relative to the property's value.
Formula: Loan Amount ÷ Property Value
A $3,750,000 mortgage on a $5,000,000 property represents a 75% LTV.
LTV helps lenders evaluate collateral coverage and the borrower's equity investment.
Why All Three Metrics Matter
A commercial property can satisfy a lender's LTV and DSCR requirements but still fail its minimum debt yield requirement.
When lenders apply all three tests, the most restrictive calculation generally determines the maximum available loan amount, subject to additional underwriting requirements.
How Debt Yield Determines Your Maximum Commercial Loan Amount
One of the most valuable applications of debt yield is calculating potential loan proceeds before submitting a financing application.
The formula is:
Maximum Loan Amount = Annual NOI ÷ Minimum Required Debt Yield
Assume you are purchasing a $5 million commercial property generating $400,000 in annual NOI.
Here's how different lender requirements could affect your maximum loan:
Required Debt Yield | Maximum Loan Amount | Equity Required Before Costs |
8% | $5,000,000 | $0 |
9% | $4,444,444 | $555,556 |
10% | $4,000,000 | $1,000,000 |
11% | $3,636,364 | $1,363,636 |
12% | $3,333,333 | $1,666,667 |
These calculations isolate the debt yield requirement. Actual loan proceeds would also be limited by LTV, DSCR, borrower qualifications, and other lender policies. The 8% example does not imply that 100% financing is available.
Notice how increasing the minimum debt yield from 10% to 12% reduces the potential loan amount by approximately $666,667.
That difference could significantly affect your required equity contribution, acquisition strategy, and projected investment returns.
Real-World Commercial Mortgage Underwriting Example
Let's assume you are acquiring a stabilized industrial property with the following characteristics:
Purchase price: $5,000,000
Annual NOI: $400,000
Requested loan: $3,750,000
Illustrative interest rate: 6.50%
Amortization: 25 years
Maximum LTV: 75%
Minimum DSCR: 1.25x
Minimum debt yield: 12%
The loan-to-value calculation supports a maximum mortgage of $3,750,000.
At a hypothetical 6.50% interest rate and 25-year amortization, annual debt service on that loan would be approximately $303,843, resulting in a DSCR of approximately 1.32x.
The loan passes both the LTV and DSCR tests.
However, the debt yield is:
$400,000 ÷ $3,750,000 = 10.67%
Because the lender requires a minimum debt yield of 12%, the requested loan does not qualify under that requirement.
The maximum loan based on debt yield would instead be:
$400,000 ÷ 12% = $3,333,333
The borrower would need approximately $416,667 in additional equity compared with the original financing request, excluding closing costs and reserves.
This is why understanding debt yield before negotiating a commercial real estate purchase is so important.
How Can Investors Improve Debt Yield?
There are several strategies commercial real estate investors can use to improve debt yield and potentially strengthen their financing options.
1. Increase Net Operating Income
Improving NOI is one of the most effective ways to strengthen debt yield.
Potential strategies include:
Increasing occupancy
Negotiating stronger lease terms
Reducing unnecessary operating expenses
Improving property management
Recovering eligible operating expenses from tenants
Increasing ancillary property income
Lenders will typically evaluate whether income improvements are documented, sustainable, and supported by market conditions.
2. Reduce the Requested Loan Amount
Because debt yield compares NOI with loan principal, reducing the requested mortgage amount increases debt yield.
This may require a larger down payment, additional investor equity, or a revised acquisition structure.
3. Purchase at a More Attractive Price
A lower purchase price does not automatically improve debt yield if the loan amount remains unchanged.
However, purchasing at a lower price may allow you to reduce the required mortgage while maintaining the same property income.
This can improve both debt yield and the overall investment economics.
4. Stabilize the Property Before Refinancing
Investors acquiring properties with vacancy, deferred maintenance, or operational challenges may benefit from a financing strategy that allows time for stabilization.
Bridge financing may be appropriate for certain transitional assets, followed by permanent financing once the property demonstrates stronger operating performance.
Borrowers should evaluate the cost of bridge financing, required reserves, renovation risks, and the feasibility of their permanent loan exit strategy.
5. Compare Multiple Commercial Mortgage Lenders
Different lenders may apply different debt yield requirements to the same commercial property.
A bank, credit union, CMBS lender, debt fund, or life insurance company may evaluate the property's income and risk differently.
Working with a commercial mortgage professional can help borrowers compare financing structures and identify lenders whose underwriting criteria align with the investment.
Debt Yield and Commercial Real Estate Refinancing
Debt yield becomes particularly important when refinancing an existing commercial mortgage.
Suppose you originally financed a property with a $4 million loan and annual NOI of $400,000.
Your original debt yield was 10%.
Several years later, the property's NOI declines to $350,000 because of higher operating expenses or increased vacancy.
If your new lender requires a 10% minimum debt yield, the maximum loan supported by that requirement would be $3.5 million.
If your existing loan payoff is still $4 million, you could face a $500,000 refinancing shortfall before closing costs.
Even if the property maintains its appraised value, the reduced operating income can limit your refinancing proceeds.
Commercial real estate investors should evaluate debt yield well before their loan maturity date to identify potential refinancing challenges.
Does Debt Yield Apply to Owner-Occupied Commercial Real Estate?
Debt yield is particularly common in income-producing investment property underwriting.
However, business owners purchasing owner-occupied commercial real estate may encounter different underwriting approaches.
For example, SBA 7(a), SBA 504, and conventional owner-occupied commercial mortgages often emphasize business cash flow, repayment ability, borrower creditworthiness, collateral, and guarantor financial strength.
Some lenders may evaluate debt yield or related income-based metrics, but traditional investment-property NOI calculations may not be the primary underwriting standard.
Doctors, dentists, manufacturers, retailers, and other business owners should compare financing programs based on their specific operating business and real estate ownership structure.
Frequently Asked Questions About Debt Yield
Is a higher debt yield better?
Generally, a higher debt yield indicates more property income relative to the loan amount, which may reduce lender risk. However, borrowers must balance conservative leverage against their equity requirements and investment return objectives.
Does debt yield include mortgage payments?
No. Debt yield uses net operating income before mortgage payments. Annual debt service is used in the DSCR calculation instead.
Is debt yield the same as a cap rate?
No. A capitalization rate compares NOI with property value or purchase price. Debt yield compares NOI with the loan amount.
For example, a property generating $400,000 in NOI with a $5 million value has an 8% cap rate. If the property has a $3.75 million mortgage, its debt yield is approximately 10.67%.
What NOI do lenders use to calculate debt yield?
Lenders generally use underwritten NOI rather than automatically accepting a seller's reported income or a borrower's projected pro forma.
They may adjust rental income, vacancy allowances, operating expenses, management fees, and reserves according to their underwriting policies.
Can debt yield change after closing?
Yes. Debt yield changes when property NOI or the outstanding loan balance changes. Increasing NOI or reducing principal generally improves debt yield.
Can a commercial loan be denied because of debt yield?
Yes. If a lender applies a minimum debt yield requirement and the proposed loan fails that test, the lender may reduce the loan amount, require additional equity, or decline the financing request.
Final Thoughts: Understand Debt Yield Before You Borrow
Debt yield is one of the most important commercial real estate lending metrics investors should understand.
It provides a direct relationship between property income and loan exposure, helping lenders evaluate risk and determine appropriate financing proceeds.
Before purchasing or refinancing commercial real estate, calculate your debt yield, review your DSCR, evaluate your LTV, and compare multiple financing options.
Remember: the maximum loan amount is not always determined by the property's appraised value or its ability to make monthly mortgage payments.
Sometimes, debt yield is the deciding factor.
Need Help Financing Your Next Commercial Real Estate Investment?
Whether you are purchasing an apartment complex, industrial warehouse, retail shopping center, medical office building, hotel, or another commercial property, the right financing structure can make a significant difference in your investment performance.
I'm Bill Rapp, CCIM, with CommLoan, helping commercial real estate investors and business owners explore financing solutions through a nationwide commercial lending marketplace.
Let's evaluate your property's cash flow, financing requirements, and investment objectives to identify potential lending options.
Top of Form
Bottom of Form
Bill Rapp, CCIM
Director | CommLoan
📞 281-222-0433
📧 [email protected]
🌐 https://billrapp.commloan.com/
🌐 https://HoustonCommercialMortgage.com/
Commercial Real Estate Financing Nationwide
https://billrapp.commloan.com/
https://author.billrapponline.com/
https://www.amazon.com/dp/B0F32Z5BH2
https://veed.cello.so/FOmzTty6oi9
https://buymeacoffee.com/vikingente3
https://creplaybookseries.billrapponline.com
https://creplaybook.billrapponline.com/
©Bill Rapp, CCIM - Director - CommLoan
10 Tips for First-Time Homebuyers
Buying your first home can be both exciting and nerve-wracking at the same time. With so many things to consider and....
How To Choose the Right Lender for You
Lorem Ipsum is simply dummy text of the printing and typesetting industry. Lorem Ipsum has been the industry's standard dummy
Refinancing youe loan and when to do it
Lorem Ipsum is simply dummy text of the printing and typesetting industry. Lorem Ipsum has been the industry's standard dummy
Copyright ©2021 | Mortgage Viking Team
Licensed to Do Business | NMLS # 228246
This is not an offer to enter into an agreement. Not all customers will qualify. Information, rates and programs are subject to change without notice. All products are subject to credit and property approval. Other restrictions and limitations may apply. Copyright © 2021 | Medallion Funds
Corporate | NMLS ID NMLS # 1825831
Corporate Address : 2651 N. Green Valley Pkwy STE. 101 Henderson, NV 89014
Corporate NMLS NMLS # 1825831 | Company Website: https://medallionfunds.com/bill-rapp/
Copyright ©2021 | Mortgage Viking Team Licensed to Do Business | NMLS # 228246
This is not an offer to enter into an agreement. Not all customers will qualify. Information, rates and programs are subject to change without notice. All products are subject to credit and property approval. Other restrictions and limitations may apply
Corporate | NMLS ID NMLS # 1825831
Corporate Address : 2651 N. Green Valley Pkwy STE. 101 Henderson, NV 89014 https://medallionfunds.com/bill-rapp/
Facebook
Instagram
X
LinkedIn
Youtube
TikTok