Low Rates.
Our rates are low, our application is quick and easy! We can get you clear to close in as little as 10 days!
Trusted By Agents With
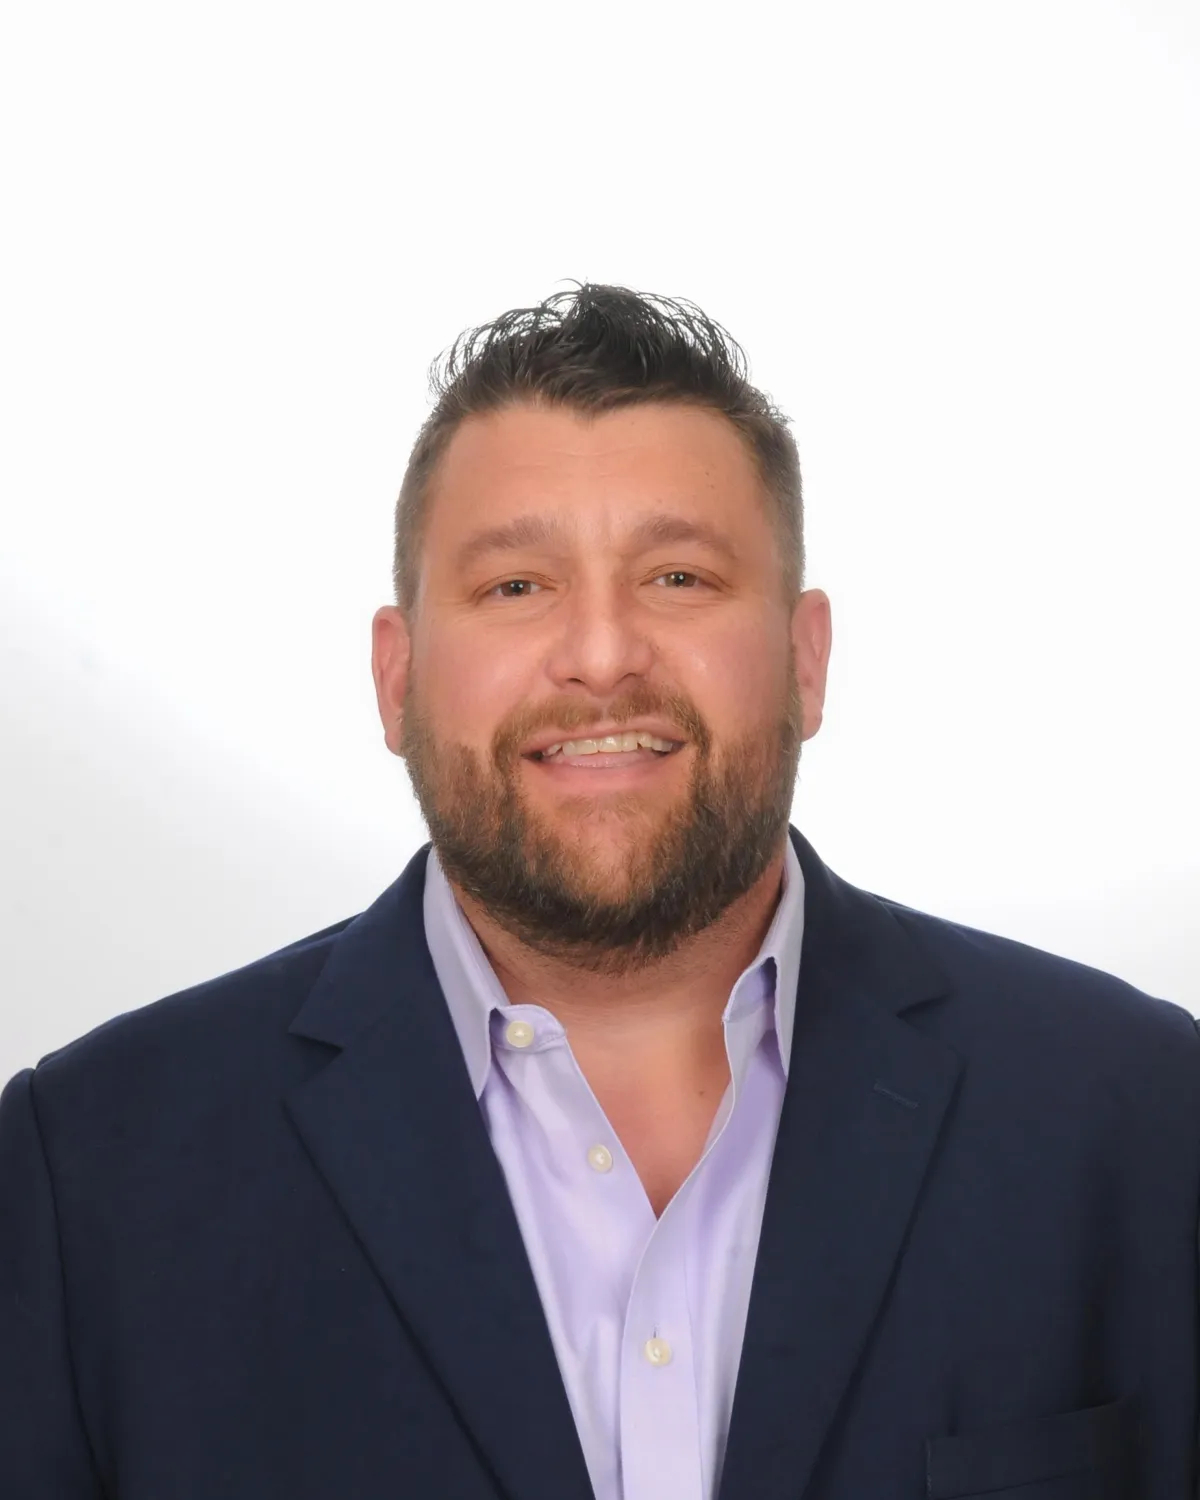
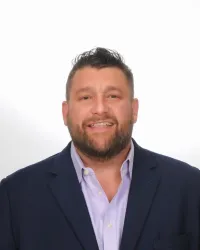
Meet Bill Rapp
NMLS ID # NMLS # 228246
Bill Rapp, CCIM is a Houston-based Capital Advisor at Medallion Funds, specializing in commercial real estate finance and strategic lending solutions. With over two decades of experience across brokerage and capital markets, Bill has worked with leading firms including eXp Commercial, NEXA Mortgage, Viking Enterprise LLC, and Sun Realty Houston.
A graduate of Texas A&M University with a BBA in Finance, Bill brings a disciplined, underwriting-first approach to every deal. His expertise spans commercial and residential financing, including asset-based lending, FHA financing, reverse mortgages, REO properties, and investment strategies for both single-family and commercial assets.
Known for his focus on structure over rate, Bill helps investors, business owners, and developers navigate complex transactions with clarity, precision, and a long-term wealth-building mindset.
The Client Experience
Great experience purchasing our first home! Bill was easy to reach and always able to answer any questions or concerns.

Loan Programs Available


Blogs
The Top 5 Mortgage Mistakes to Avoid
Buying your first home can be both exciting and nerve-wracking at the same time. With so many things to consider and....
Mortgage Do and
Do not list
Mortgages can be tricky, and it's easy to make mistakes that can end up costing you dearly. That's why we've put together this list....
Tips On How To Improve Your Credit Score
Let's talk about some ways you can improve your credit score! Your credit score is actually a big deal, and it can affect...
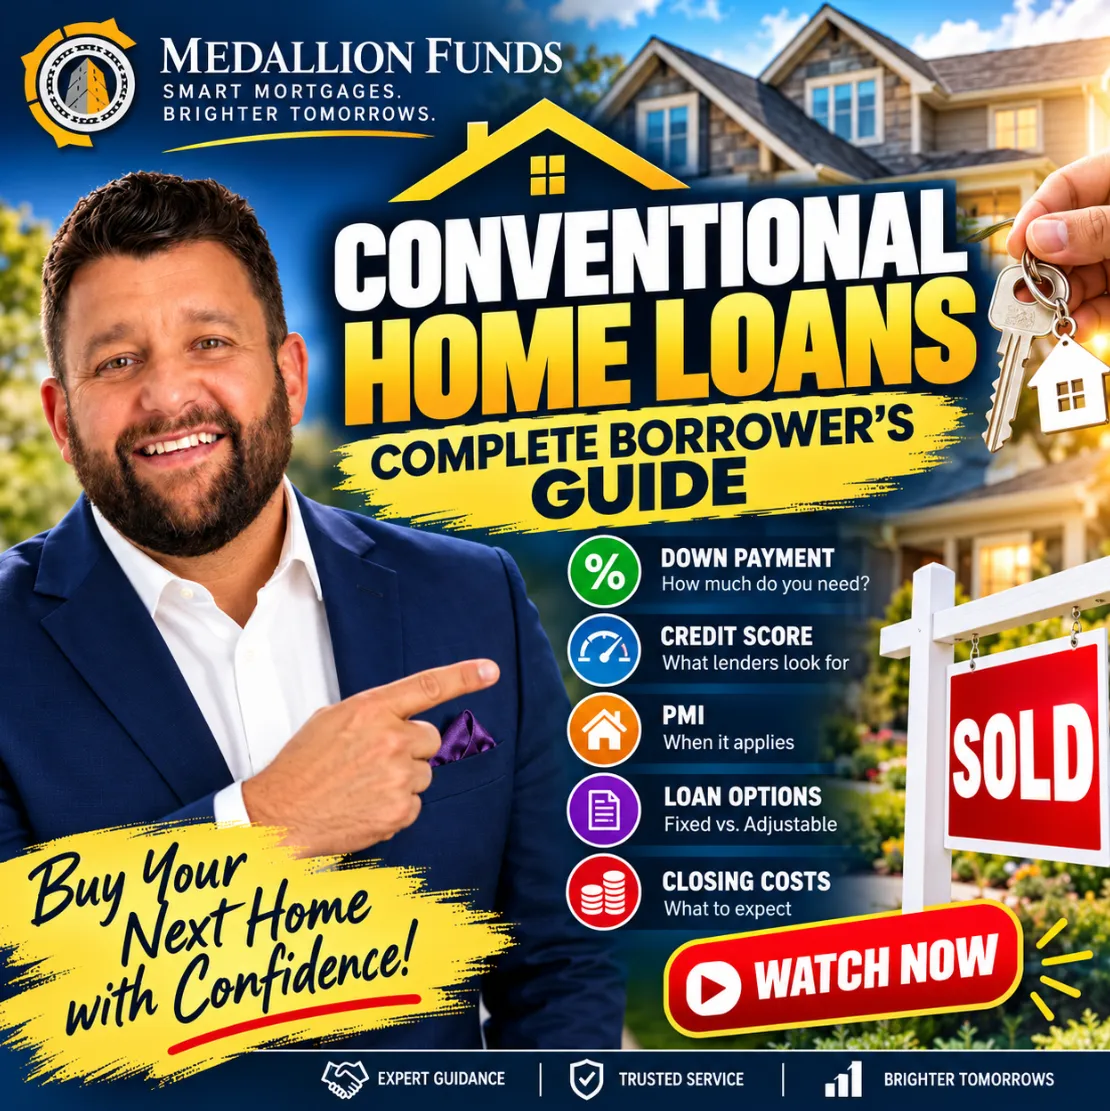
🏡 Conventional Home Loans Explained: The Complete Borrower’s Guide to Buying a Home 🔑
🏡 Conventional Home Loans Explained: The Complete Borrower’s Guide to Buying a Home 🔑
💰 Conventional Mortgage Guide 2026: Down Payments, Credit, PMI & How to Qualify 🏠
________________________________________________________________________________
Conventional Home Loans: Complete Borrower’s Guide
When most people think about getting a mortgage, they are often thinking about a conventional home loan.
Conventional mortgages are widely used because they can offer competitive rates, multiple down-payment options, fixed- and adjustable-rate structures, and financing for several types of residential properties. But “conventional” does not mean every conventional loan works the same way—or that it is automatically the best mortgage for every borrower.
Understanding how conventional financing works can help you make a more informed decision before you start shopping for a home.
At Medallion Funds, our approach is to look beyond the advertised mortgage rate and help borrowers evaluate the complete financing structure.
What Is a Conventional Home Loan?
A conventional mortgage is a residential mortgage that is not insured or guaranteed by a federal government agency such as the FHA, VA, or USDA.
Many conventional mortgages are structured to meet guidelines established by Fannie Mae or Freddie Mac. Loans falling within applicable conforming loan limits and other requirements are generally referred to as conforming conventional loans.
Conventional financing can potentially be used for:
·Primary residences
·Second homes
·Investment properties
·Single-family homes
·Eligible condominiums
·Eligible planned-unit developments
·Certain 2–4 unit residential properties
The exact requirements depend on the borrower, occupancy, property and loan program.
How Much Down Payment Do You Need?
One of the biggest misconceptions about conventional mortgages is that you always need 20% down.
You don't.
Certain qualifying borrowers and transactions may permit substantially smaller down payments. However, putting less than 20% down can affect mortgage insurance, monthly payments, reserves and underwriting.
Instead of asking only, “What's the minimum down payment?” consider a better question:
How much should I put down based on my cash reserves, monthly payment and long-term financial objectives?
Keeping additional liquidity after closing can sometimes be more valuable than putting every available dollar into the property.
What Is Private Mortgage Insurance?
If your conventional mortgage has a higher loan-to-value ratio, you may be required to carry private mortgage insurance (PMI).
PMI protects the lender—not the homeowner—against certain losses if the borrower defaults.
The cost can vary based on factors such as credit profile, loan-to-value ratio and mortgage structure.
PMI should therefore be included when comparing financing strategies. A smaller down payment may preserve cash but could result in a higher monthly housing expense.
What Credit Score Do You Need for a Conventional Mortgage?
Credit is an important part of conventional mortgage underwriting, but your score isn't evaluated in isolation.
Underwriters can also consider:
Income: Do you have sufficient qualifying income?
Debt: How much of your monthly income is already committed to other obligations?
Assets: Do you have enough money for the down payment, closing costs and required reserves?
Employment: Is your income and employment history acceptable under the applicable guidelines?
Property: Does the home satisfy the program's collateral requirements?
A borrower with excellent credit but excessive monthly obligations can still encounter qualification issues.
Understanding Debt-to-Income Ratio
Your debt-to-income ratio (DTI) compares qualifying monthly debt obligations with qualifying gross monthly income.
For example, suppose your applicable monthly debt obligations, including the proposed housing payment, total $5,000 and your qualifying gross monthly income is $12,500.
Your DTI would be:
$5,000 ÷ $12,500 = 40%
Actual underwriting is more nuanced, and acceptable DTI levels depend on the complete loan file and applicable program requirements.
This is one reason a proper mortgage pre-approval can be valuable before you start seriously shopping for homes.
Conventional Fixed-Rate vs. Adjustable-Rate Mortgages
A fixed-rate conventional mortgage keeps the interest rate fixed for the loan's term. This provides payment predictability for principal and interest.
An adjustable-rate mortgage (ARM) generally offers an initial rate for a specified period before the rate can adjust according to the loan's terms.
Neither structure should be evaluated solely on the initial rate.
Consider your anticipated holding period, future plans, available cash, risk tolerance and the loan's adjustment mechanics.
Conventional vs. FHA Loans
FHA and conventional mortgages can both be useful, but they operate differently.
FHA financing is government-insured and has its own credit, down-payment and mortgage-insurance rules. Conventional financing uses different underwriting and mortgage-insurance structures.
For some borrowers, FHA financing can provide a viable path to homeownership. For others, conventional financing may provide a better combination of monthly payment, mortgage insurance and long-term flexibility.
The comparison should be based on the total financing package, not simply the interest rate.
Conventional vs. VA Loans
Eligible veterans, active-duty service members and certain surviving spouses may have access to VA financing.
VA loans can provide substantial benefits to qualified borrowers, including the possibility of purchasing without a traditional down payment, subject to eligibility, underwriting and program requirements.
A VA-eligible borrower should generally understand both options rather than assuming conventional financing is preferable simply because it is more familiar.
What Closing Costs Should You Expect?
Your down payment isn't the only cash you may need at closing.
Depending on the transaction, costs can include lender charges, appraisal costs, title-related expenses, prepaid homeowners insurance, initial escrow funding, taxes and other third-party charges.
That makes cash to close different from down payment.
Understanding that distinction early can prevent an unpleasant surprise immediately before closing.
Why Mortgage Pre-Approval Matters
A strong pre-approval can accomplish several things before you make an offer.
It can help establish an appropriate purchase-price range, identify potential underwriting problems, estimate your required cash, compare mortgage strategies and strengthen your understanding of the payment associated with different home prices.
Getting pre-approved doesn't mean you should automatically spend the maximum amount you qualify to borrow.
Your mortgage should fit your broader financial plan.
Don't Shop for a Conventional Mortgage by Rate Alone
Interest rate matters—but it is only one component of mortgage financing.
When comparing conventional home loans, evaluate the interest rate, APR, points, lender credits, PMI, estimated closing costs, cash to close, monthly payment and loan structure together.
A seemingly lower interest rate can become less attractive if obtaining it requires significant upfront discount points.
Likewise, a slightly higher rate paired with lender credits might make sense for a borrower who expects to own the property for a relatively short period.
The right comparison depends on the numbers.
Should You Pay Mortgage Points?
Discount points allow borrowers to pay money upfront in exchange for a lower mortgage rate.
Whether that makes financial sense depends heavily on the break-even period.
Suppose paying additional points costs $4,000 and reduces your monthly payment by $80.
Your simple break-even period would be:
$4,000 ÷ $80 = 50 months
If you expect to refinance or sell before reaching that point, paying the additional upfront cost may be less attractive.
Common Conventional Mortgage Mistakes
Some of the most avoidable problems occur after borrowers have already started the mortgage process.
Opening new credit accounts, financing a vehicle, significantly increasing credit-card balances, changing employment structures or moving large undocumented sums of money can complicate underwriting.
Before making a significant financial change while your mortgage is in process, talk with your mortgage professional.
Is a Conventional Mortgage Right for You?
A conventional loan can be an excellent financing tool, but the decision depends on your specific circumstances.
Rather than beginning with, “Who has the lowest rate?”, start with:
“What mortgage structure makes the most sense for my financial situation and homeownership goals?”
That change in perspective can lead to a much more productive mortgage conversation.
At Medallion Funds, we help homebuyers evaluate mortgage options based on the entire financing picture—because the goal isn't simply getting a mortgage.
It's getting the right mortgage strategy for the borrower and transaction.
Bill Rapp
Partner & Director of Capital Advisory | Medallion Funds
Commercial Lending Nationwide
Residential Lending in AL, CA, CO, NV & TXBottom of Form
https://www.billrapponline.com/
https://findamortgagebroker.com/Profile/WilliamRappJr28883
https://billrapp.commloan.com/
https://billrapponline.com/financingfuturescre-houston-katy
https://houstoncommercialmortgage.com/
https://author.billrapponline.com
https://doctorvideo.billrapponline.com/
https://veteransvideo.billrapponline.com/
https://mortgageviking.billrapponline.com/
https://fha203h.billrapponline.com/
https://renovationvideo.billrapponline.com
https://medallionfunds.com/bill-rapp/
https://www.amazon.com/dp/B0F32Z5BH2
https://veed.cello.so/FOmzTty6oi9
https://buymeacoffee.com/vikingente3
https://creplaybookseries.billrapponline.com
https://creplaybook.billrapponline.com/
© Bill Rapp, Medallion Funds LLC, Director of Capital Advisory
10 Tips for First-Time Homebuyers
Buying your first home can be both exciting and nerve-wracking at the same time. With so many things to consider and....
How To Choose the Right Lender for You
Lorem Ipsum is simply dummy text of the printing and typesetting industry. Lorem Ipsum has been the industry's standard dummy
Refinancing youe loan and when to do it
Lorem Ipsum is simply dummy text of the printing and typesetting industry. Lorem Ipsum has been the industry's standard dummy
Copyright ©2021 | Mortgage Viking Team
Licensed to Do Business | NMLS # 228246
This is not an offer to enter into an agreement. Not all customers will qualify. Information, rates and programs are subject to change without notice. All products are subject to credit and property approval. Other restrictions and limitations may apply. Copyright © 2021 | Medallion Funds
Corporate | NMLS ID NMLS # 1825831
Corporate Address : 2651 N. Green Valley Pkwy STE. 101 Henderson, NV 89014
Corporate NMLS NMLS # 1825831 | Company Website: https://medallionfunds.com/bill-rapp/
Copyright ©2021 | Mortgage Viking Team Licensed to Do Business | NMLS # 228246
This is not an offer to enter into an agreement. Not all customers will qualify. Information, rates and programs are subject to change without notice. All products are subject to credit and property approval. Other restrictions and limitations may apply
Corporate | NMLS ID NMLS # 1825831
Corporate Address : 2651 N. Green Valley Pkwy STE. 101 Henderson, NV 89014 https://medallionfunds.com/bill-rapp/
Facebook
Instagram
X
LinkedIn
Youtube
TikTok