Low Rates.
Our rates are low, our application is quick and easy! We can get you clear to close in as little as 10 days!
Trusted By Agents With
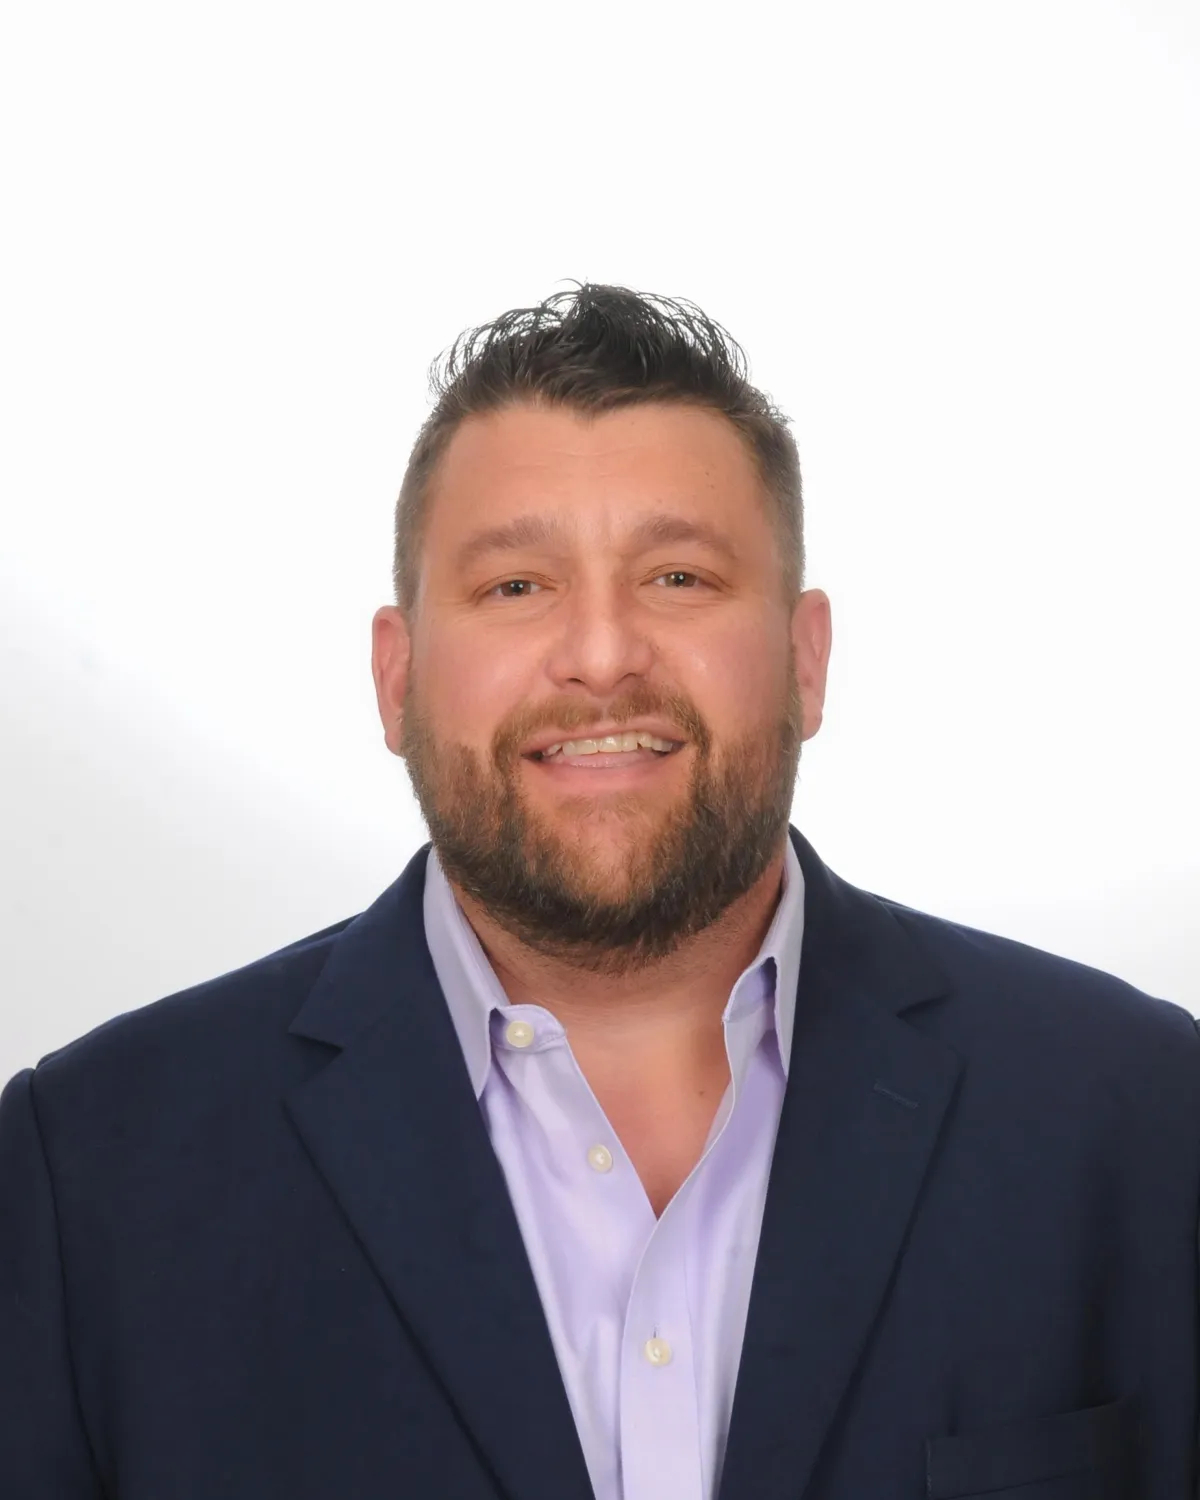
Meet Bill Rapp
NMLS ID # NMLS # 228246
Bill Rapp, CCIM is a Houston-based Capital Advisor at Medallion Funds, specializing in commercial real estate finance and strategic lending solutions. With over two decades of experience across brokerage and capital markets, Bill has worked with leading firms including eXp Commercial, NEXA Mortgage, Viking Enterprise LLC, and Sun Realty Houston.
A graduate of Texas A&M University with a BBA in Finance, Bill brings a disciplined, underwriting-first approach to every deal. His expertise spans commercial and residential financing, including asset-based lending, FHA financing, reverse mortgages, REO properties, and investment strategies for both single-family and commercial assets.
Known for his focus on structure over rate, Bill helps investors, business owners, and developers navigate complex transactions with clarity, precision, and a long-term wealth-building mindset.
The Client Experience
Great experience purchasing our first home! Bill was easy to reach and always able to answer any questions or concerns.

Loan Programs Available


Blogs
The Top 5 Mortgage Mistakes to Avoid
Buying your first home can be both exciting and nerve-wracking at the same time. With so many things to consider and....
Mortgage Do and
Do not list
Mortgages can be tricky, and it's easy to make mistakes that can end up costing you dearly. That's why we've put together this list....
Tips On How To Improve Your Credit Score
Let's talk about some ways you can improve your credit score! Your credit score is actually a big deal, and it can affect...
🏢 Commercial Real Estate Loan Broker: What Do They Do? 💰
🏢 Commercial Real Estate Loan Broker: What Do They Do? 💰
💼 What Does a Commercial Mortgage Broker Do? 🏦
_______________________________________________________________________________
Commercial Real Estate Loan Broker: What Does One Actually Do?
When you're purchasing a shopping center, refinancing an apartment complex, acquiring an industrial warehouse, or financing a building for your business, finding the right commercial real estate loan can be one of the most important decisions you'll make.
But here's something many investors and business owners don't realize:
The lender offering the lowest interest rate isn't necessarily offering the best financing solution.
Different commercial lenders evaluate properties, borrowers, cash flow, and risk differently. A loan that works perfectly for one lender might be rejected by another.
That's where a commercial real estate loan broker comes in.
A qualified commercial mortgage broker does more than submit loan applications. They help borrowers evaluate financing options, identify appropriate capital sources, structure transactions, negotiate terms, and navigate the commercial loan process.
Let's explore what commercial real estate loan brokers actually do, how they get paid, and when hiring one makes financial sense.
What Is a Commercial Real Estate Loan Broker?
A commercial real estate loan broker is a financing intermediary who connects commercial property investors and business owners with lenders offering financing for commercial real estate transactions.
Unlike a bank loan officer, who generally originates loans through their institution's available programs, an independent commercial mortgage broker may work with multiple capital providers.
These providers can include:
Commercial banks and credit unions
SBA 7(a) and SBA 504 lenders
Commercial mortgage-backed securities (CMBS) lenders
Fannie Mae and Freddie Mac multifamily lenders
Life insurance companies
Debt funds and private credit providers
Bridge and transitional lenders
Construction lenders
Specialty commercial finance companies
The objective isn't simply to find a lender willing to approve a loan.
It's to identify financing that aligns with the property's performance, the borrower's financial position, and the investor's long-term strategy.
1. A Commercial Loan Broker Evaluates Your Financing Needs
Before approaching lenders, an experienced commercial real estate loan broker should understand the transaction.
That starts with evaluating the property, borrower, and proposed financing structure.
Important considerations include:
Property type: Is the asset multifamily, retail, office, industrial, hospitality, self-storage, or another commercial property type?
Loan purpose: Are you purchasing, refinancing, renovating, developing, or accessing equity?
Property performance: What are the occupancy, rental income, operating expenses, and net operating income?
Borrower qualifications: What are the borrower's liquidity, credit history, experience, and financial strength?
Investment strategy: Are you planning to hold the property long-term, renovate and reposition it, or sell within several years?
For example, an investor purchasing a stabilized apartment building may benefit from a different financing structure than an investor acquiring a partially vacant retail center.
The right commercial mortgage broker understands these distinctions before presenting the transaction to lenders.
2. A Commercial Mortgage Broker Identifies Appropriate Lenders
One of the biggest challenges in commercial real estate financing is that lenders don't all operate under the same underwriting guidelines.
A traditional bank may prefer stabilized properties, strong borrowers, and conservative leverage.
A bridge lender may consider a property with significant vacancy if the borrower has a credible improvement strategy.
An SBA lender may finance an eligible owner-occupied commercial building that doesn't fit a conventional investment-property loan program.
A multifamily agency lender may offer attractive long-term financing for a qualifying apartment property.
The same property can receive dramatically different financing proposals depending on which lenders review the transaction.
An experienced broker helps borrowers avoid approaching lenders whose programs don't match their needs.
How CommLoan Helps Match Borrowers With Capital Sources
Through CommLoan's CUPID™ commercial lending technology, borrowers can be matched with potential financing programs based on their transaction characteristics.
Rather than relying exclusively on one bank's lending criteria, the platform supports a broader lender-matching and comparison process.
The objective is to identify relevant financing alternatives more efficiently and help borrowers make informed decisions.
Lender matches are potential options, not loan approvals or commitments.
3. A Commercial Real Estate Loan Broker Helps Structure the Loan
Commercial financing involves much more than choosing an interest rate.
An experienced commercial loan broker evaluates the entire loan structure.
Loan-to-Value Ratio (LTV)
LTV measures the loan amount relative to the property's appraised value.
For example:
Property value: $3,000,000
Proposed loan: $2,100,000
LTV: 70%
A lender may advertise 70% LTV financing, but that doesn't mean every qualifying property will receive that leverage.
Other underwriting requirements may limit the loan amount.
Debt Service Coverage Ratio (DSCR)
DSCR measures a property's ability to cover required debt payments from net operating income.
DSCR = Net Operating Income ÷ Annual Debt Service
Suppose a property generates $240,000 in annual NOI and has $180,000 in annual debt service.
DSCR = $240,000 ÷ $180,000 = 1.33x
That means the property generates approximately $1.33 in NOI for every $1.00 of required annual debt service.
Lenders establish different minimum DSCR requirements based on their programs and risk assessment.
Amortization and Loan Term
A commercial loan might have a five-year term with payments calculated using a 25-year amortization schedule.
Another lender might offer a 10-year term with 30-year amortization.
These differences affect monthly cash flow, balloon-payment exposure, and refinancing risk.
Recourse vs. Nonrecourse
Recourse financing generally allows the lender to pursue certain borrower or guarantor assets if the loan defaults, subject to applicable documents and law.
Nonrecourse financing generally limits recovery to specified collateral, although customary carveouts can create personal liability under certain circumstances.
Understanding these provisions is critical when evaluating commercial mortgage proposals.
4. A Commercial Loan Broker Compares Financing Proposals
A lower interest rate doesn't automatically mean a better commercial mortgage.
Consider two hypothetical financing options:
Loan Feature | Lender A | Lender B |
Loan amount | $2,000,000 | $2,000,000 |
Interest rate | 6.75% | 7.00% |
Amortization | 20 years | 30 years |
Loan term | 5 years | 10 years |
Prepayment terms | To be negotiated | To be negotiated |
Recourse | To be determined | To be determined |
Although Lender A has a lower interest rate, Lender B's longer amortization may provide lower monthly principal-and-interest payments.
However, Lender B may also result in slower principal repayment and higher interest expense over comparable periods.
A qualified broker evaluates the tradeoffs, including:
Monthly debt service
Total financing costs
Origination and lender fees
Prepayment penalties
Cash-flow flexibility
Recourse provisions
Required reserves
Closing timelines
Balloon-payment and refinancing exposure
The best loan depends on the borrower's objectives—not simply the advertised rate.
5. A Commercial Mortgage Broker Coordinates Underwriting and Closing
Once a financing option is selected, the work isn't finished.
Commercial mortgage transactions often require substantial documentation.
Common lender requests include:
Current rent roll
Historical operating statements
Trailing 12-month income and expenses
Business and personal tax returns
Personal financial statement
Schedule of real estate owned
Existing loan information
Entity formation documents
Property insurance information
Leases and tenant information
Appraisal, environmental, and property condition reports
A commercial loan broker helps organize these materials, communicate with the lender, address underwriting questions, and coordinate with the relevant transaction professionals.
Depending on the deal, those professionals may include the real estate broker, title company, attorney, appraiser, environmental consultant, insurance agent, and lender's closing team.
A good broker helps identify potential problems early rather than waiting until closing.
Real-World Example: Financing a $3 Million Shopping Center
Imagine an investor purchasing a neighborhood shopping center for $3 million.
The property generates $210,000 in annual net operating income.
The investor wants a $2.1 million loan, representing 70% LTV.
At first glance, that may seem reasonable.
But suppose the lender requires a minimum DSCR of 1.25x.
The maximum annual debt service supported by the property's NOI would be:
$210,000 ÷ 1.25 = $168,000 annually
Now assume a proposed 7% interest rate with 25-year amortization.
The annual principal-and-interest payments on a $2.1 million loan would be approximately $178,000.
That produces a DSCR of approximately 1.18x.
The property may meet the lender's LTV guideline while failing its DSCR requirement.
A commercial real estate loan broker could evaluate several alternatives:
1.Reduce the requested loan amount.
2.Compare lenders with different underwriting requirements.
3.Evaluate longer amortization where available.
4.Explore whether documented additional income or legitimate expense adjustments improve underwritten NOI.
5.Consider bridge financing if the property has a credible stabilization strategy.
The goal isn't to force a deal through underwriting.
It's to identify a responsible financing structure supported by the property's economics.
6. How Much Does a Commercial Real Estate Loan Broker Charge?
Commercial mortgage broker compensation varies based on the loan type, transaction size, complexity, and financing arrangement.
Some brokers receive a lender-paid fee, while others charge a borrower-paid origination or brokerage fee.
For illustration, a 1% brokerage fee on a $2 million commercial loan would equal $20,000.
However, that is only an example—not a universal fee schedule.
Borrowers should ask:
What brokerage or origination fees apply?
Who pays those fees?
Are there additional lender or third-party costs?
Is any fee due before closing?
Is the broker compensated differently depending on the lender selected?
Are any fees refundable?
Compensation and disclosure requirements depend on the transaction and applicable law.
Always request a clear written explanation of compensation before proceeding.
7. When Should You Hire a Commercial Real Estate Loan Broker?
Working with a commercial mortgage broker may be particularly valuable when:
You're purchasing commercial property. A broker can help compare financing structures before your purchase contract deadlines become critical.
You're refinancing an existing loan. A broker can assess maturity risk, cash flow, valuation, and replacement financing options.
Your bank declined the transaction. A broker may identify other lenders with different risk appetites, although alternative financing isn't guaranteed.
You're financing a specialized property. Hotels, churches, self-storage facilities, and certain owner-user properties may require specialized lenders.
You're acquiring a value-add property. Bridge or transitional financing may be more appropriate than permanent financing during stabilization.
You're a business owner buying your building. SBA and conventional owner-occupied financing options may offer different structures, eligibility rules, and equity requirements.
The earlier you evaluate financing, the more time you generally have to address potential obstacles.
8. How to Choose the Right Commercial Mortgage Broker
Not every commercial loan broker offers the same experience, lender access, or advisory capabilities.
Before choosing a broker, consider asking:
1.What commercial property types do you regularly finance?
2.Which lender categories can you access?
3.How do you evaluate DSCR, LTV, and borrower qualifications?
4.Can you compare multiple financing structures?
5.How are you compensated?
6.What happens if the first lender declines the transaction?
7.Who manages communication during underwriting and closing?
Look for someone who can explain the financial implications of each option—not just quote an interest rate.
The Bottom Line: A Commercial Loan Broker Is a Capital Strategy Partner
Commercial real estate financing isn't one-size-fits-all.
Two investors purchasing similar properties can qualify for different financing based on their experience, liquidity, income, business plans, and lender selection.
A commercial real estate loan broker helps bridge the gap between a borrower's financing objectives and the requirements of potential capital providers.
The value comes from understanding the transaction, identifying appropriate lenders, evaluating financing structures, and helping navigate the process through closing.
Let's Find the Right Commercial Financing Strategy
I'm Bill Rapp, CCIM, Director with CommLoan, and I help commercial real estate investors and business owners evaluate financing strategies across a wide range of commercial property types.
Through the CommLoan Empower Program and CUPID™ lender-matching technology, we help borrowers explore commercial lending options without relying on a single lender's underwriting guidelines.
Whether you're purchasing, refinancing, developing, or expanding your commercial real estate portfolio, let's discuss your financing objectives.
Explore your commercial financing options:
https://billrapp.commloan.com/
Top of Form
Bottom of Form
Bill Rapp, CCIM
Director | CommLoan
📞 281-222-0433
📧 [email protected]
🌐 https://billrapp.commloan.com/
🌐 https://HoustonCommercialMortgage.com/
Commercial Real Estate Financing Nationwide
https://billrapp.commloan.com/
https://author.billrapponline.com/
https://www.amazon.com/dp/B0F32Z5BH2
https://veed.cello.so/FOmzTty6oi9
https://buymeacoffee.com/vikingente3
https://creplaybookseries.billrapponline.com
https://creplaybook.billrapponline.com/
©Bill Rapp, CCIM - Director - CommLoan
10 Tips for First-Time Homebuyers
Buying your first home can be both exciting and nerve-wracking at the same time. With so many things to consider and....
How To Choose the Right Lender for You
Lorem Ipsum is simply dummy text of the printing and typesetting industry. Lorem Ipsum has been the industry's standard dummy
Refinancing youe loan and when to do it
Lorem Ipsum is simply dummy text of the printing and typesetting industry. Lorem Ipsum has been the industry's standard dummy
Copyright ©2021 | Mortgage Viking Team
Licensed to Do Business | NMLS # 228246
This is not an offer to enter into an agreement. Not all customers will qualify. Information, rates and programs are subject to change without notice. All products are subject to credit and property approval. Other restrictions and limitations may apply. Copyright © 2021 | Medallion Funds
Corporate | NMLS ID NMLS # 1825831
Corporate Address : 2651 N. Green Valley Pkwy STE. 101 Henderson, NV 89014
Corporate NMLS NMLS # 1825831 | Company Website: https://medallionfunds.com/bill-rapp/
Copyright ©2021 | Mortgage Viking Team Licensed to Do Business | NMLS # 228246
This is not an offer to enter into an agreement. Not all customers will qualify. Information, rates and programs are subject to change without notice. All products are subject to credit and property approval. Other restrictions and limitations may apply
Corporate | NMLS ID NMLS # 1825831
Corporate Address : 2651 N. Green Valley Pkwy STE. 101 Henderson, NV 89014 https://medallionfunds.com/bill-rapp/
Facebook
Instagram
X
LinkedIn
Youtube
TikTok