Low Rates.
Our rates are low, our application is quick and easy! We can get you clear to close in as little as 10 days!
Trusted By Agents With
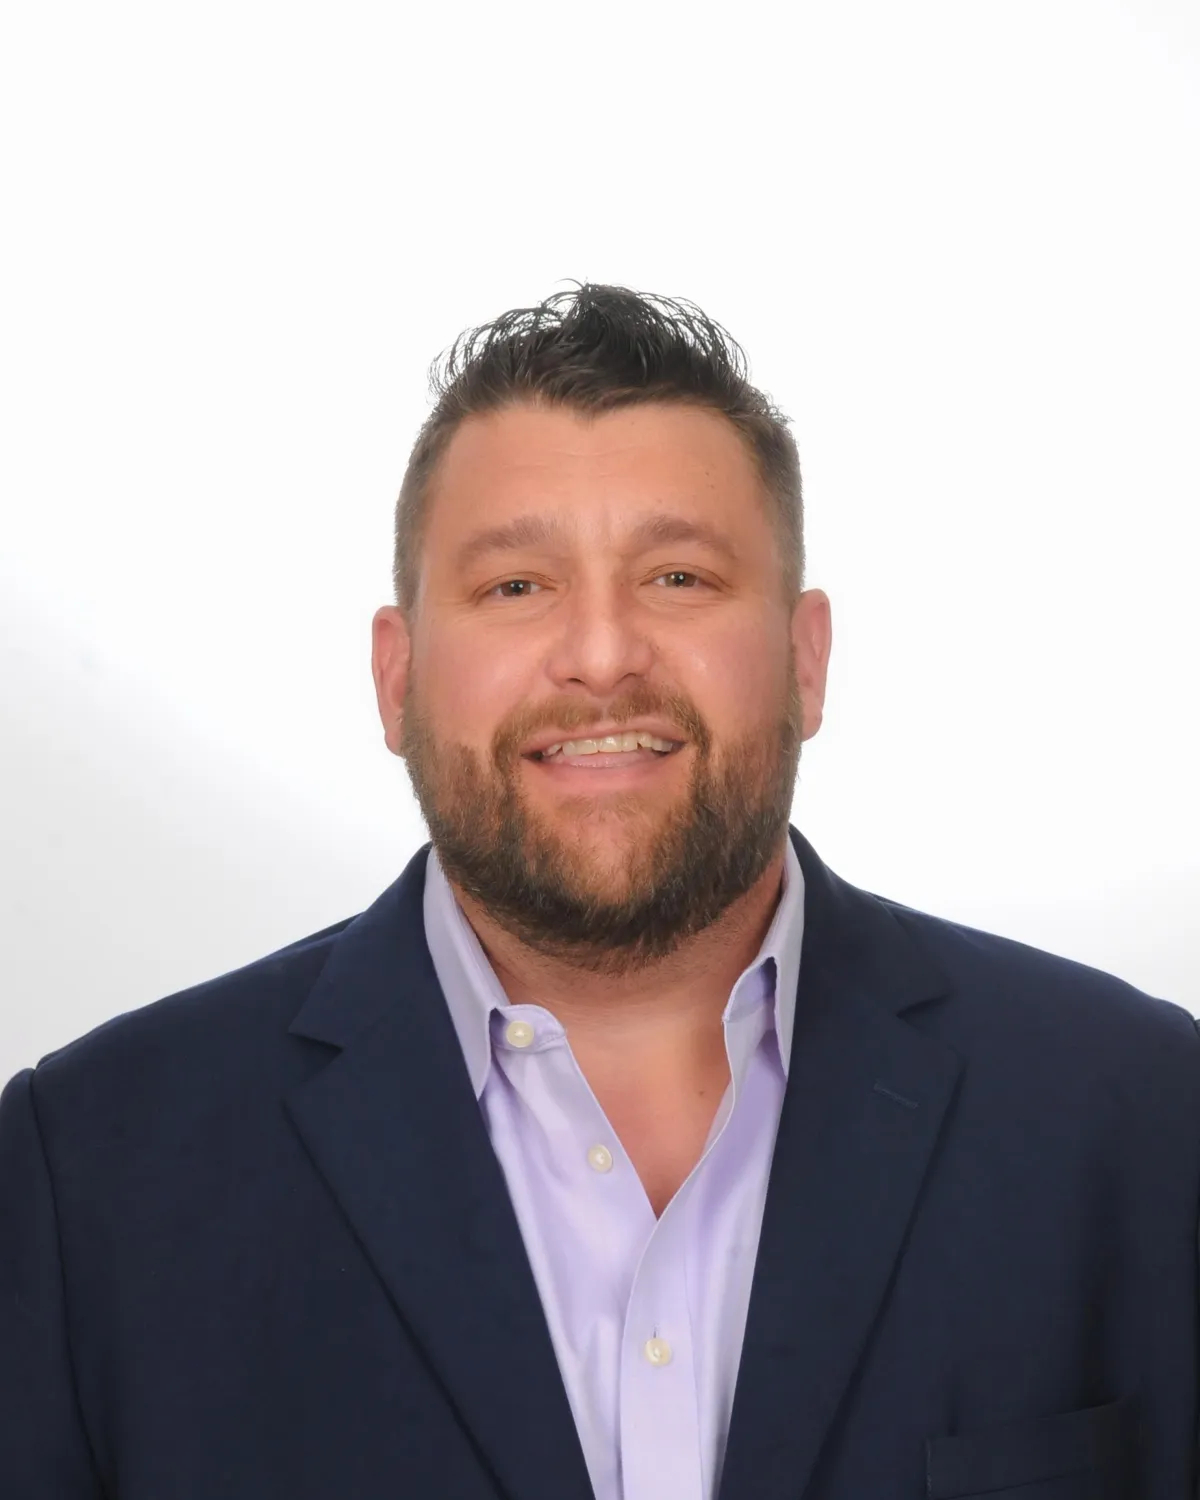
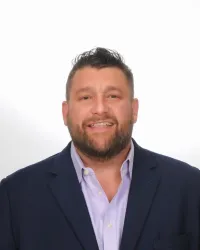
Meet Bill Rapp
NMLS ID # NMLS # 228246
Bill Rapp, CCIM is a Houston-based Capital Advisor at Medallion Funds, specializing in commercial real estate finance and strategic lending solutions. With over two decades of experience across brokerage and capital markets, Bill has worked with leading firms including eXp Commercial, NEXA Mortgage, Viking Enterprise LLC, and Sun Realty Houston.
A graduate of Texas A&M University with a BBA in Finance, Bill brings a disciplined, underwriting-first approach to every deal. His expertise spans commercial and residential financing, including asset-based lending, FHA financing, reverse mortgages, REO properties, and investment strategies for both single-family and commercial assets.
Known for his focus on structure over rate, Bill helps investors, business owners, and developers navigate complex transactions with clarity, precision, and a long-term wealth-building mindset.
The Client Experience
Great experience purchasing our first home! Bill was easy to reach and always able to answer any questions or concerns.

Loan Programs Available


Blogs
The Top 5 Mortgage Mistakes to Avoid
Buying your first home can be both exciting and nerve-wracking at the same time. With so many things to consider and....
Mortgage Do and
Do not list
Mortgages can be tricky, and it's easy to make mistakes that can end up costing you dearly. That's why we've put together this list....
Tips On How To Improve Your Credit Score
Let's talk about some ways you can improve your credit score! Your credit score is actually a big deal, and it can affect...
💰 Cash-Out Refinancing for Apartment Buildings: How Multifamily Investors Can Unlock Equity 🏢
💰 Cash-Out Refinancing for Apartment Buildings: How Multifamily Investors Can Unlock Equity 🏢
🏢 Turn Apartment Equity Into Investment Capital: A Guide to Multifamily Cash-Out Refinancing 💵
Cash-Out Refinancing for Apartment Buildings: How Multifamily Investors Can Unlock Equity
Apartment owners can sometimes find themselves in an enviable position: they own a property that has appreciated, rents have increased, operations have improved, and substantial equity has accumulated.
The question becomes: How can you access some of that equity without selling the apartment building?
One potential solution is a cash-out refinance.
Cash-out refinancing can allow multifamily investors to replace an existing mortgage with a new, larger loan and receive a portion of the difference in cash. That capital may then be available for another acquisition, renovations, reserves, partnership restructuring, or other investment and business purposes, subject to lender requirements.
But having significant equity does not automatically mean a lender will allow you to extract all of it.
For apartment buildings, the available loan proceeds are typically determined by a combination of property value, loan-to-value ratio, net operating income, debt service coverage ratio, debt yield, borrower strength, property performance, and lender guidelines.
Here is what apartment investors should understand before pursuing a cash-out refinance.
What Is a Cash-Out Refinance on an Apartment Building?
A cash-out refinance replaces an existing apartment loan with a new mortgage that is larger than the debt being paid off.
Consider a simplified example.
Assume an apartment building is worth $5,000,000 and has an existing mortgage balance of $2,500,000.
If a lender approves a new loan of $3,250,000, the transaction could potentially generate approximately $750,000 of gross cash-out proceeds before closing costs, reserves, escrows, prepayment charges, lender fees and other transaction expenses.
The basic calculation is:
New Loan Amount – Existing Loan Payoff – Transaction Costs = Potential Net Cash Proceeds
The calculation itself is easy.
Getting the property to support the desired new loan amount is where underwriting becomes important.
Why Apartment Owners Use Cash-Out Refinancing
One major advantage of owning commercial real estate is the potential ability to build equity while maintaining ownership of the asset.
Rather than selling an appreciated apartment property to access capital, an investor may refinance it.
Potential uses of cash-out proceeds can include:
·Funding the equity requirement for another apartment acquisition
·Renovating or repositioning an existing property
·Building liquidity or operating reserves
·Funding capital improvements
·Buying out an investment partner
·Consolidating certain obligations
·Recapturing capital invested into improvements
·Expanding a commercial real estate portfolio
The appropriate strategy depends on the investor's objectives, property performance, new debt service and overall portfolio.
How Much Cash Can You Take Out?
This is where investors need to distinguish between property equity and financeable equity.
Suppose your apartment building is worth $5 million and you owe only $2 million.
You technically have approximately $3 million of equity.
That does not mean a lender will allow you to borrow another $3 million.
The maximum loan is usually constrained by several underwriting metrics.
Loan-to-Value Ratio
Loan-to-value, or LTV, compares the loan amount with the property's appraised value.
The formula is:
Loan Amount ÷ Property Value = LTV
If a $5 million property qualifies for a 70% LTV loan, the theoretical maximum based solely on LTV would be:
$5,000,000 × 70% = $3,500,000
But that still does not guarantee a $3.5 million loan.
The property's cash flow also has to support the debt.
DSCR Can Reduce Your Maximum Loan Proceeds
Debt Service Coverage Ratio is one of the most important metrics in apartment financing.
DSCR compares the property's net operating income with its required debt service.
NOI ÷ Annual Debt Service = DSCR
For example, if an apartment building generates $400,000 of NOI and annual debt service is $300,000:
$400,000 ÷ $300,000 = 1.33x DSCR
A lender requiring a minimum DSCR will size the loan so the property's underwritten cash flow provides sufficient coverage.
That means an apartment property could satisfy the lender's maximum LTV requirement but still fail to support the same loan amount based on DSCR.
In that situation, cash flow rather than property value may determine the maximum proceeds.
Debt Yield May Also Matter
Debt yield measures property NOI relative to the loan amount:
NOI ÷ Loan Amount = Debt Yield
If an apartment building produces $400,000 of NOI and the proposed loan is $4 million:
$400,000 ÷ $4,000,000 = 10% debt yield
Debt yield provides lenders another way to evaluate leverage without relying on interest rate, amortization period or property value.
Depending on the lender and loan program, LTV, DSCR and debt yield can all influence the final loan amount.
Property Value Matters—But So Does NOI
One of the best ways apartment owners can improve their refinancing position is by improving sustainable NOI.
Apartment values are frequently analyzed using capitalization rates.
A simplified valuation formula is:
NOI ÷ Cap Rate = Estimated Property Value
For example:
$400,000 NOI ÷ 6.00% Cap Rate = $6,666,667
If sustainable NOI increases to $450,000 while the assumed cap rate remains unchanged:
$450,000 ÷ 6.00% = $7,500,000
That illustrates why operational improvements can have a significant effect on both apartment valuation and potential refinancing proceeds.
However, lenders and appraisers will determine which income and expenses they consider sustainable. Owners should not assume every recent rent increase or expense reduction will receive full underwriting credit.
What Will a Lender Review?
A multifamily cash-out refinance is fundamentally an underwriting exercise.
Expect lenders to evaluate items such as historical property operating statements, trailing-12-month financials, current rent roll, occupancy, leases, delinquency, property taxes, insurance, utilities, repairs and maintenance, management expenses, capital expenditures and market conditions.
They will also review the borrowing entity, ownership structure, sponsor experience, liquidity, net worth, credit profile and existing debt.
The stronger and more organized the credit package, the easier it becomes to determine which financing structures may be viable.
Apartment Cash-Out Refinance Loan Options
There isn't one universal apartment refinance product.
Depending on the property, borrower and transaction, potential financing sources can include banks, credit unions, agency multifamily programs, life insurance companies, CMBS lenders, debt funds, bridge lenders and other commercial real estate lenders.
Each lender may approach leverage, cash-out proceeds, reserves, recourse, amortization, prepayment provisions and sponsor requirements differently.
This is why comparing apartment refinance offers requires looking beyond interest rate.
Don't Compare Apartment Loans on Rate Alone
A lower rate is valuable, but it is only one component of the financing structure.
An investor should also evaluate:
Loan proceeds. Term. Amortization. Fixed versus floating rate. Recourse. Prepayment structure. Closing costs. Reserves. Covenants. Cash-out restrictions.
For an investor whose primary objective is accessing equity, a slightly lower interest rate may not compensate for substantially lower loan proceeds.
Conversely, maximizing cash-out may not make sense if doing so creates excessive debt service or weakens the property's financial flexibility.
The appropriate loan is the one that best fits the investor's strategy.
When Does a Cash-Out Refinance Make Sense?
Cash-out refinancing may be worth evaluating when a property has experienced meaningful appreciation, NOI has increased, existing debt is relatively low, renovations have increased property performance, or an investor has a productive use for additional capital.
It can be particularly powerful when equity trapped in one stabilized property can be redeployed into another investment opportunity.
But additional leverage creates additional risk.
Investors should stress-test the new debt against potential vacancy, expense increases, insurance costs, property taxes and future interest-rate conditions.
The Key Question Isn't Just “How Much Equity Do I Have?”
The better question is:
How much of my equity can the property responsibly support as debt under current lending standards?
That answer requires evaluating value, NOI, LTV, DSCR, debt yield and lender requirements together.
A property can have millions of dollars of equity and still generate substantially less cash-out than an owner initially expects.
Conversely, a strong apartment property with increasing NOI, conservative existing leverage and experienced sponsorship may present attractive refinancing opportunities.
Before You Refinance, Compare the Market
Commercial lending is not a one-size-fits-all business.
Different lenders can evaluate the same apartment building differently. One lender may be constrained by DSCR. Another may offer a different amortization schedule. Another may have stricter cash-out limitations or recourse requirements.
Through the CommLoan Empower Program, I help commercial real estate investors evaluate financing alternatives and compare structures based on more than the headline interest rate.
If you are considering a cash-out refinance for an apartment building, start by understanding what the property's current NOI, value and existing debt may support.
Top of Form
Bottom of Form
Bill Rapp, CCIM
Director | CommLoan
📞 281-222-0433
📧 [email protected]
🌐 https://billrapp.commloan.com/
🌐 https://HoustonCommercialMortgage.com/
Commercial Real Estate Financing Nationwide
https://billrapp.commloan.com/
https://author.billrapponline.com/
https://www.amazon.com/dp/B0F32Z5BH2
https://veed.cello.so/FOmzTty6oi9
https://buymeacoffee.com/vikingente3
https://creplaybookseries.billrapponline.com
https://creplaybook.billrapponline.com/
©Bill Rapp, CCIM - Director - CommLoan
10 Tips for First-Time Homebuyers
Buying your first home can be both exciting and nerve-wracking at the same time. With so many things to consider and....
How To Choose the Right Lender for You
Lorem Ipsum is simply dummy text of the printing and typesetting industry. Lorem Ipsum has been the industry's standard dummy
Refinancing youe loan and when to do it
Lorem Ipsum is simply dummy text of the printing and typesetting industry. Lorem Ipsum has been the industry's standard dummy
Copyright ©2021 | Mortgage Viking Team
Licensed to Do Business | NMLS # 228246
This is not an offer to enter into an agreement. Not all customers will qualify. Information, rates and programs are subject to change without notice. All products are subject to credit and property approval. Other restrictions and limitations may apply. Copyright © 2021 | Medallion Funds
Corporate | NMLS ID NMLS # 1825831
Corporate Address : 2651 N. Green Valley Pkwy STE. 101 Henderson, NV 89014
Corporate NMLS NMLS # 1825831 | Company Website: https://medallionfunds.com/bill-rapp/
Copyright ©2021 | Mortgage Viking Team Licensed to Do Business | NMLS # 228246
This is not an offer to enter into an agreement. Not all customers will qualify. Information, rates and programs are subject to change without notice. All products are subject to credit and property approval. Other restrictions and limitations may apply
Corporate | NMLS ID NMLS # 1825831
Corporate Address : 2651 N. Green Valley Pkwy STE. 101 Henderson, NV 89014 https://medallionfunds.com/bill-rapp/
Facebook
Instagram
X
LinkedIn
Youtube
TikTok