Low Rates.
Our rates are low, our application is quick and easy! We can get you clear to close in as little as 10 days!
Trusted By Agents With
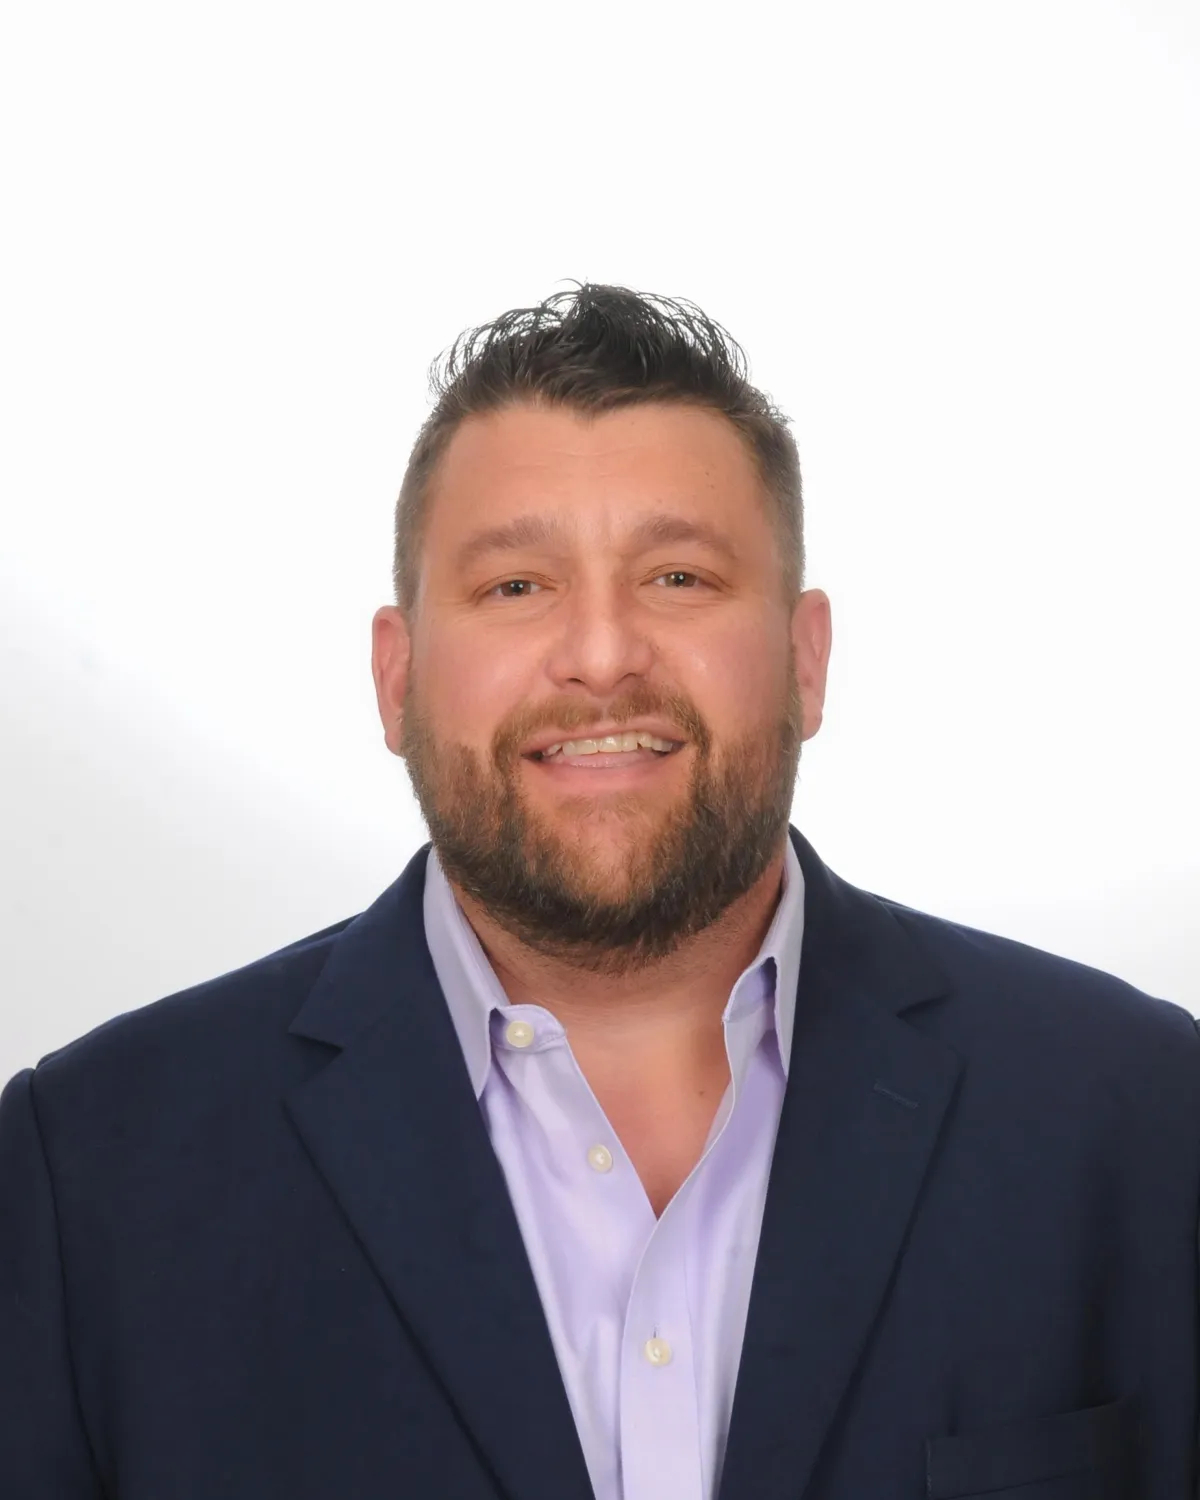
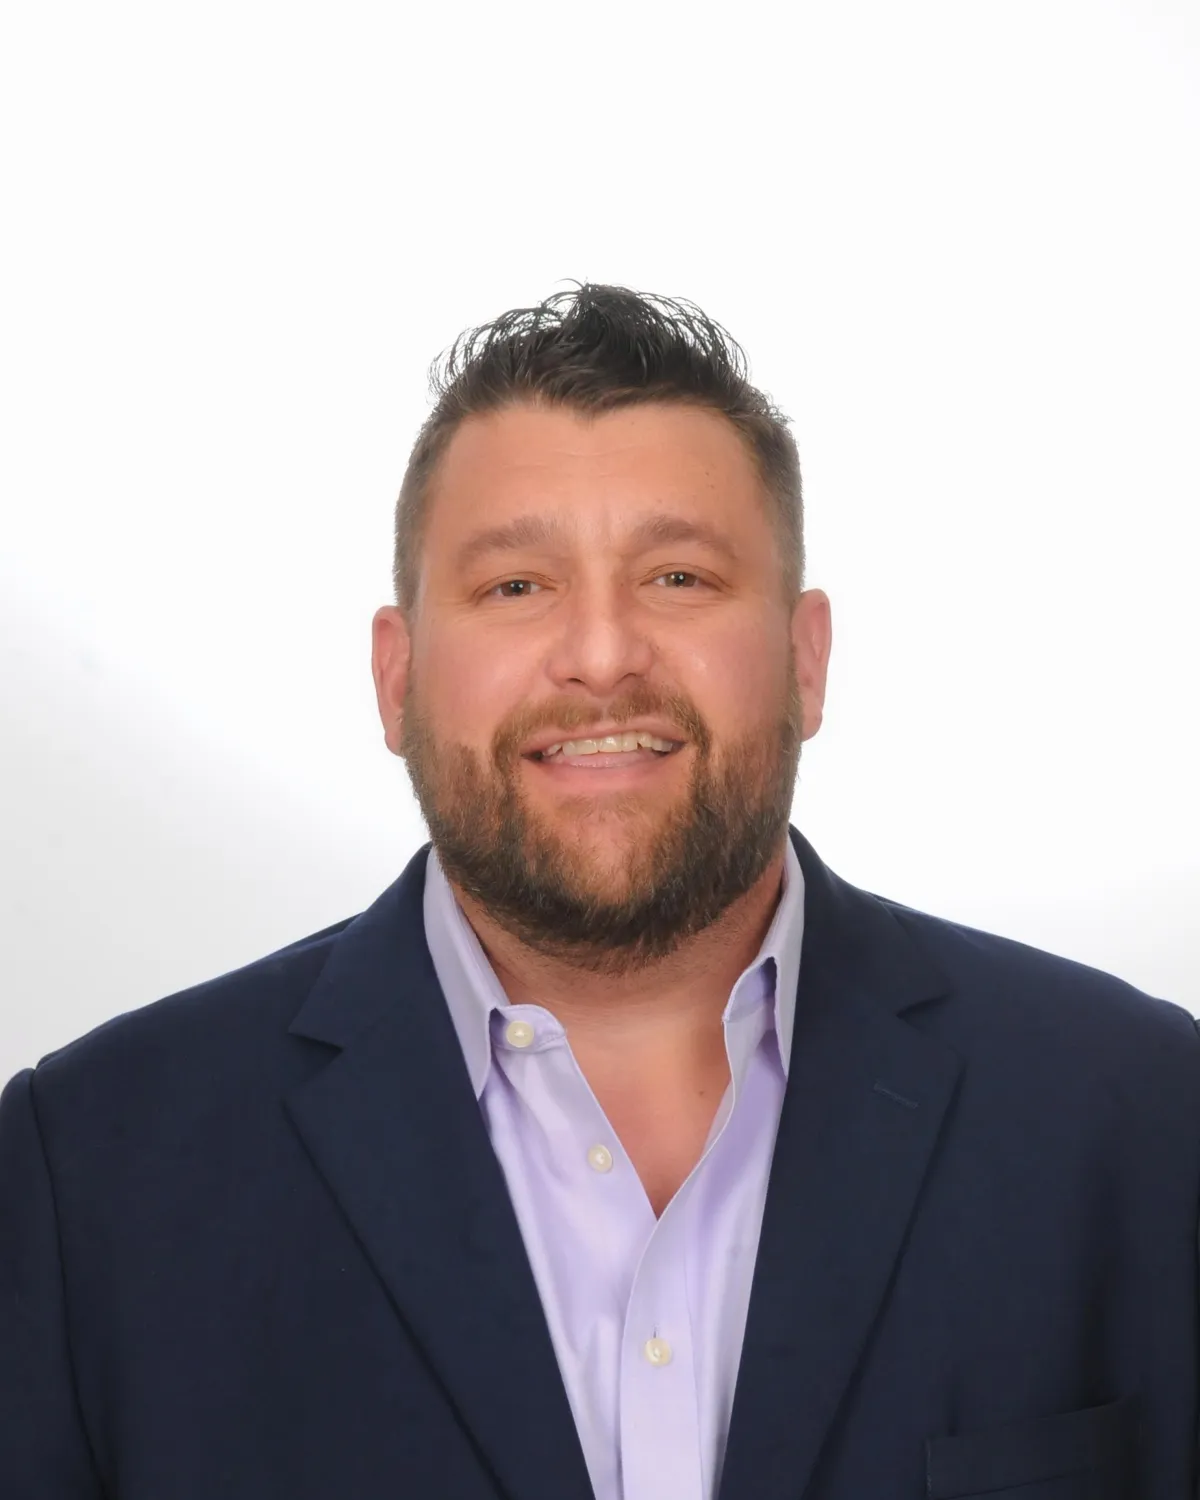
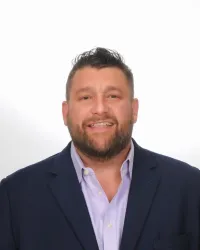
Meet Bill Rapp
NMLS ID # NMLS # 228246
Bill Rapp, CCIM is a Houston-based Capital Advisor at Medallion Funds, specializing in commercial real estate finance and strategic lending solutions. With over two decades of experience across brokerage and capital markets, Bill has worked with leading firms including eXp Commercial, NEXA Mortgage, Viking Enterprise LLC, and Sun Realty Houston.
A graduate of Texas A&M University with a BBA in Finance, Bill brings a disciplined, underwriting-first approach to every deal. His expertise spans commercial and residential financing, including asset-based lending, FHA financing, reverse mortgages, REO properties, and investment strategies for both single-family and commercial assets.
Known for his focus on structure over rate, Bill helps investors, business owners, and developers navigate complex transactions with clarity, precision, and a long-term wealth-building mindset.
The Client Experience
Great experience purchasing our first home! Bill was easy to reach and always able to answer any questions or concerns.

Loan Programs Available


Blogs
The Top 5 Mortgage Mistakes to Avoid
Buying your first home can be both exciting and nerve-wracking at the same time. With so many things to consider and....
Mortgage Do and
Do not list
Mortgages can be tricky, and it's easy to make mistakes that can end up costing you dearly. That's why we've put together this list....
Tips On How To Improve Your Credit Score
Let's talk about some ways you can improve your credit score! Your credit score is actually a big deal, and it can affect...
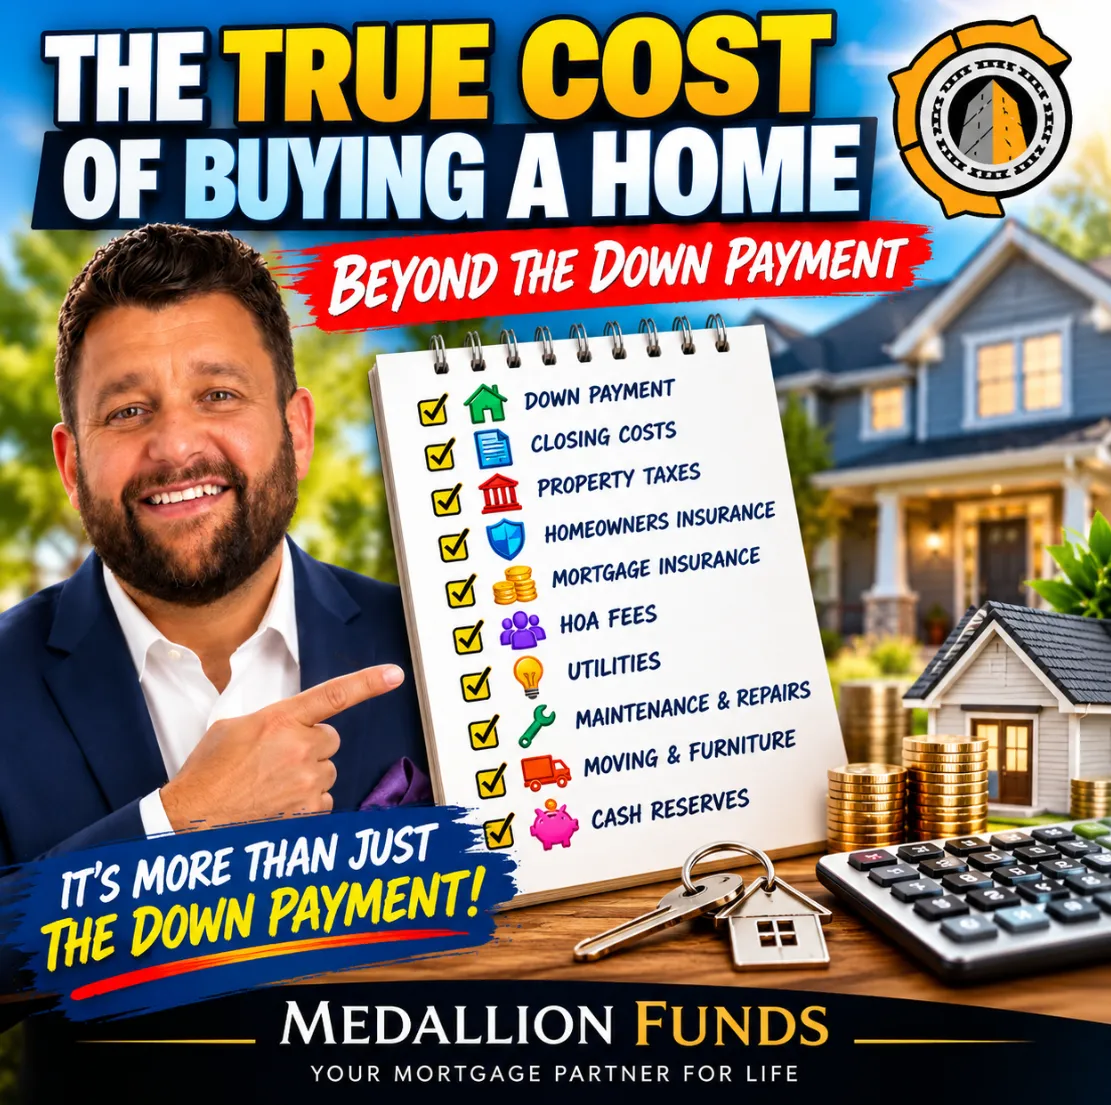
🏡 The True Cost of Buying a Home: 8 Expenses Beyond the Down Payment 💰
🏡 The True Cost of Buying a Home: 8 Expenses Beyond the Down Payment 💰
💵 Buying a Home in 2026? The Hidden Homeownership Costs Buyers Need to Budget For 🏠
________________________________________________________________________________
The True Cost of Buying a Home: Beyond the Down Payment
When preparing to buy a home, one number tends to get most of the attention: the down payment.
It is important—but it is only one part of the financial picture.
A buyer who saves enough for the down payment but overlooks closing costs, property taxes, homeowners insurance, prepaid expenses, moving costs, maintenance, utilities, and future repairs can quickly discover that buying a home costs more than expected.
That is why a strong mortgage strategy should answer a bigger question than simply:
“How much house can I qualify for?”
It should also help answer:
“How much home can I comfortably afford to own?”
At Medallion Funds, we help homebuyers evaluate the financing structure and the broader costs associated with purchasing a home so they can make a more informed decision.
Your Down Payment Is Only the Beginning
Your required down payment depends on the mortgage program, borrower qualifications, property type, occupancy, and other underwriting factors.
One of the biggest misconceptions among homebuyers is that every conventional mortgage requires 20% down.
It doesn't.
Depending on the program and borrower qualifications, some conventional mortgages allow substantially smaller down payments. FHA, VA, USDA, jumbo, doctor and other specialized mortgage programs have their own requirements.
But putting less money down doesn't eliminate the other expenses involved in buying and owning a home.
In fact, the better question is often:
How should I allocate the cash I have available between the down payment, closing costs, reserves and expenses after closing?
1. Closing Costs
In addition to the down payment, buyers should prepare for mortgage and transaction-related closing expenses.
Depending on the transaction, these can include items such as:
·Lender and third-party fees
·Appraisal
·Title-related charges
·Escrow expenses
·Recording charges
·Discount points, if applicable
·Prepaid interest
·Initial escrow deposits
The actual amount varies considerably by loan, property and transaction.
This is why buyers should review their Loan Estimate carefully rather than relying on a generic closing-cost percentage.
2. Property Taxes
Property taxes can have a significant impact on the true monthly cost of homeownership, particularly in markets such as Texas.
When comparing homes, don't evaluate the purchase price and mortgage payment alone.
Two similarly priced homes can have meaningfully different total housing payments because of differences in their property taxes.
If taxes are escrowed, your lender generally collects a portion with your monthly mortgage payment. Your escrow payment can also change as taxes and insurance costs change.
3. Homeowners Insurance
Your mortgage lender will generally require homeowners insurance.
Premiums can vary based on factors such as the home's location, construction, age, replacement cost, deductible, coverage and insurer.
Buyers should obtain insurance estimates before closing, especially when insurance costs could materially affect their monthly housing budget.
Depending on the property's location, additional coverage—such as flood insurance—may also need to be considered.
4. Mortgage Insurance
Depending on the mortgage program and financing structure, mortgage insurance may be another cost.
For example, conventional borrowers putting less than 20% down may be required to carry private mortgage insurance, commonly called PMI, although requirements and cancellation rules vary.
FHA financing has its own mortgage insurance structure.
Rather than automatically assuming mortgage insurance makes a loan unattractive, compare the complete strategy. A smaller down payment could allow you to retain more cash for reserves, repairs or other financial priorities.
5. HOA Fees
Buying in a community governed by a homeowners association can mean another recurring expense.
HOA assessments can range substantially depending on the community and amenities provided.
Ask about:
monthly or annual assessments, transfer fees, special assessments, pending increases and other association-related charges.
HOA dues aren't simply another expense to remember. Depending on the loan program, they can also factor into your debt-to-income analysis.
6. Moving, Furniture and Immediate Improvements
Closing day isn't necessarily the end of your spending.
New homeowners frequently incur expenses for moving, furniture, appliances, window treatments, security systems, landscaping and immediate improvements.
Individually, these expenses may seem manageable. Combined, they can consume thousands of dollars surprisingly quickly.
Build these expenses into your homebuying budget before deciding how much cash to commit to the down payment.
7. Maintenance and Repairs
Renters can generally call the landlord when the air conditioner fails.
Homeowners call the repair company—and receive the bill.
HVAC systems, roofs, plumbing, appliances, electrical systems and exterior components eventually require maintenance, repair or replacement.
There isn't one maintenance budget appropriate for every home. The property's age, size, condition and construction can dramatically affect potential expenses.
A newly constructed home and a 40-year-old home shouldn't necessarily have identical maintenance assumptions.
8. Your Emergency Reserve After Closing
One of the most overlooked homebuying numbers is:
How much money will you have left after closing?
A buyer might technically have enough money for the down payment and closing costs while leaving themselves with very little liquidity afterward.
That can create unnecessary financial pressure.
Instead, consider the entire transaction:
Cash available – down payment – closing expenses – moving/improvement costs = remaining reserves.
Your appropriate reserve depends on your circumstances, but the calculation should be made before closing.
Don't Shop for a Home Using Purchase Price Alone
Suppose two houses both cost $500,000.
That does not mean they cost the same to own.
One could have higher property taxes, higher insurance premiums, substantial HOA dues and aging mechanical systems. The other could have lower recurring expenses and newer major components.
The better comparison is the home's total monthly and long-term ownership cost.
This is where mortgage planning becomes particularly important.
Get Pre-Approved for a Payment—Not Just a Loan Amount
Mortgage pre-approval is frequently treated as a question of maximum purchasing power:
“What's the most I can qualify for?”
Consider turning that question around.
Ask:
“What purchase price and financing structure give me a monthly payment and post-closing cash position I'm comfortable with?”
Those are two very different questions.
The mortgage with the smallest down payment isn't automatically the right choice.
Neither is the mortgage with the largest down payment.
And the lowest advertised interest rate isn't automatically the best overall financing structure.
The objective should be to evaluate the complete mortgage strategy.
Build Your Homebuying Budget Before You Start Shopping
Before making an offer, estimate four numbers:
Cash to close: Down payment plus expected closing and prepaid expenses.
Total housing payment: Principal, interest, taxes, insurance, mortgage insurance and HOA dues when applicable.
Initial ownership expenses: Moving, furnishings, improvements and immediate repairs.
Post-closing reserves: The cash you expect to retain after completing the purchase.
When those numbers work together, you can approach homeownership with a much clearer financial picture.
The Bottom Line
The true cost of buying a home goes far beyond the down payment.
Closing expenses, taxes, insurance, mortgage insurance, HOA dues, maintenance, repairs, utilities, moving costs and reserves all matter.
That doesn't mean buying a home is a bad financial decision. It means buyers should understand the complete economics of homeownership before signing at the closing table.
At Medallion Funds, our goal is to help borrowers look beyond the advertised rate and down-payment percentage and evaluate the mortgage as part of their broader homebuying strategy.
Before you start shopping for your next home, understand the numbers behind the keys.
Bill Rapp
Partner & Director of Capital Advisory | Medallion Funds
Commercial Lending Nationwide
Residential Lending in AL, CA, CO, NV & TXBottom of Form
https://www.billrapponline.com/
https://findamortgagebroker.com/Profile/WilliamRappJr28883
https://billrapp.commloan.com/
https://billrapponline.com/financingfuturescre-houston-katy
https://houstoncommercialmortgage.com/
https://author.billrapponline.com
https://doctorvideo.billrapponline.com/
https://veteransvideo.billrapponline.com/
https://mortgageviking.billrapponline.com/
https://fha203h.billrapponline.com/
https://renovationvideo.billrapponline.com
https://medallionfunds.com/bill-rapp/
https://www.amazon.com/dp/B0F32Z5BH2
https://veed.cello.so/FOmzTty6oi9
https://buymeacoffee.com/vikingente3
https://creplaybookseries.billrapponline.com
https://creplaybook.billrapponline.com/
© Bill Rapp, Medallion Funds LLC, Director of Capital Advisory
10 Tips for First-Time Homebuyers
Buying your first home can be both exciting and nerve-wracking at the same time. With so many things to consider and....
How To Choose the Right Lender for You
Lorem Ipsum is simply dummy text of the printing and typesetting industry. Lorem Ipsum has been the industry's standard dummy
Refinancing youe loan and when to do it
Lorem Ipsum is simply dummy text of the printing and typesetting industry. Lorem Ipsum has been the industry's standard dummy
Copyright ©2021 | Mortgage Viking Team
Licensed to Do Business | NMLS # 228246
This is not an offer to enter into an agreement. Not all customers will qualify. Information, rates and programs are subject to change without notice. All products are subject to credit and property approval. Other restrictions and limitations may apply. Copyright © 2021 | Medallion Funds
Corporate | NMLS ID NMLS # 1825831
Corporate Address : 2651 N. Green Valley Pkwy STE. 101 Henderson, NV 89014
Corporate NMLS NMLS # 1825831 | Company Website: https://medallionfunds.com/bill-rapp/
Copyright ©2021 | Mortgage Viking Team Licensed to Do Business | NMLS # 228246
This is not an offer to enter into an agreement. Not all customers will qualify. Information, rates and programs are subject to change without notice. All products are subject to credit and property approval. Other restrictions and limitations may apply
Corporate | NMLS ID NMLS # 1825831
Corporate Address : 2651 N. Green Valley Pkwy STE. 101 Henderson, NV 89014 https://medallionfunds.com/bill-rapp/
Facebook
Instagram
X
LinkedIn
Youtube
TikTok