Low Rates.
Our rates are low, our application is quick and easy! We can get you clear to close in as little as 10 days!
Trusted By Agents With
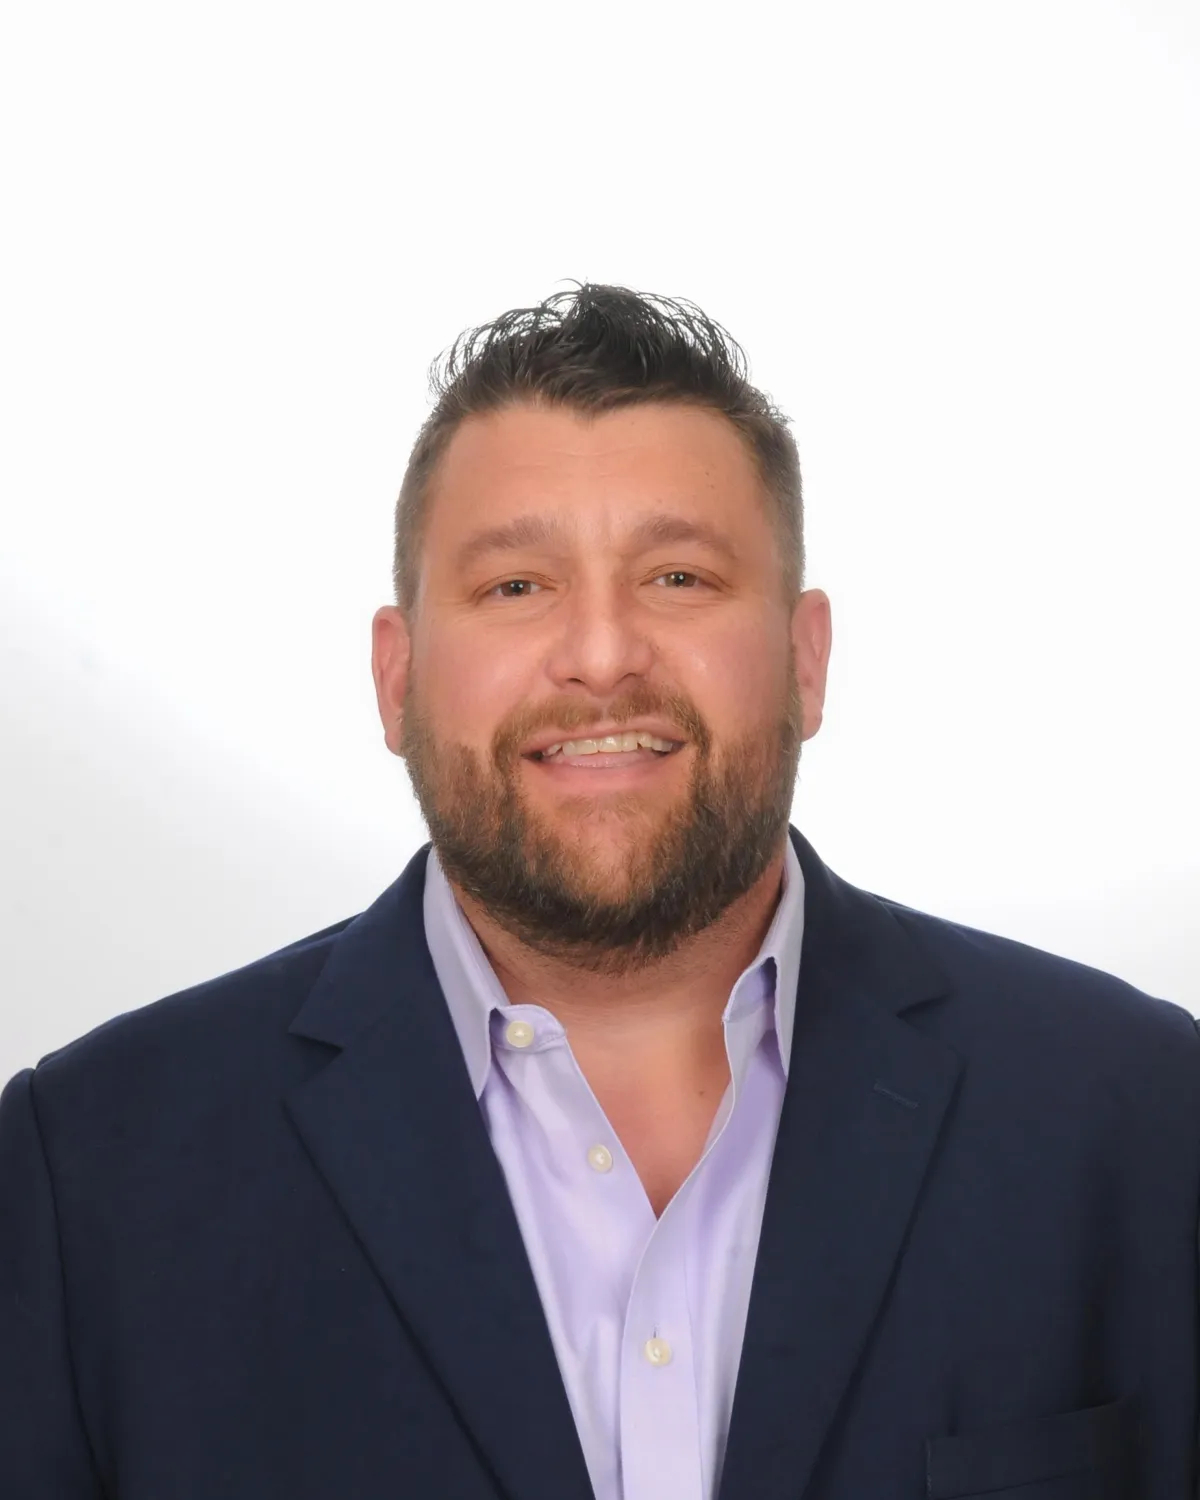
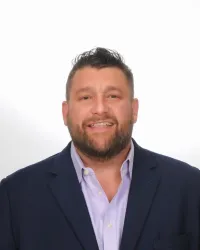
Meet Bill Rapp
NMLS ID # NMLS # 228246
Bill Rapp, CCIM is a Houston-based Capital Advisor at Medallion Funds, specializing in commercial real estate finance and strategic lending solutions. With over two decades of experience across brokerage and capital markets, Bill has worked with leading firms including eXp Commercial, NEXA Mortgage, Viking Enterprise LLC, and Sun Realty Houston.
A graduate of Texas A&M University with a BBA in Finance, Bill brings a disciplined, underwriting-first approach to every deal. His expertise spans commercial and residential financing, including asset-based lending, FHA financing, reverse mortgages, REO properties, and investment strategies for both single-family and commercial assets.
Known for his focus on structure over rate, Bill helps investors, business owners, and developers navigate complex transactions with clarity, precision, and a long-term wealth-building mindset.
The Client Experience
Great experience purchasing our first home! Bill was easy to reach and always able to answer any questions or concerns.

Loan Programs Available
Blogs
The Top 5 Mortgage Mistakes to Avoid
Buying your first home can be both exciting and nerve-wracking at the same time. With so many things to consider and....
Mortgage Do and
Do not list
Mortgages can be tricky, and it's easy to make mistakes that can end up costing you dearly. That's why we've put together this list....
Tips On How To Improve Your Credit Score
Let's talk about some ways you can improve your credit score! Your credit score is actually a big deal, and it can affect...
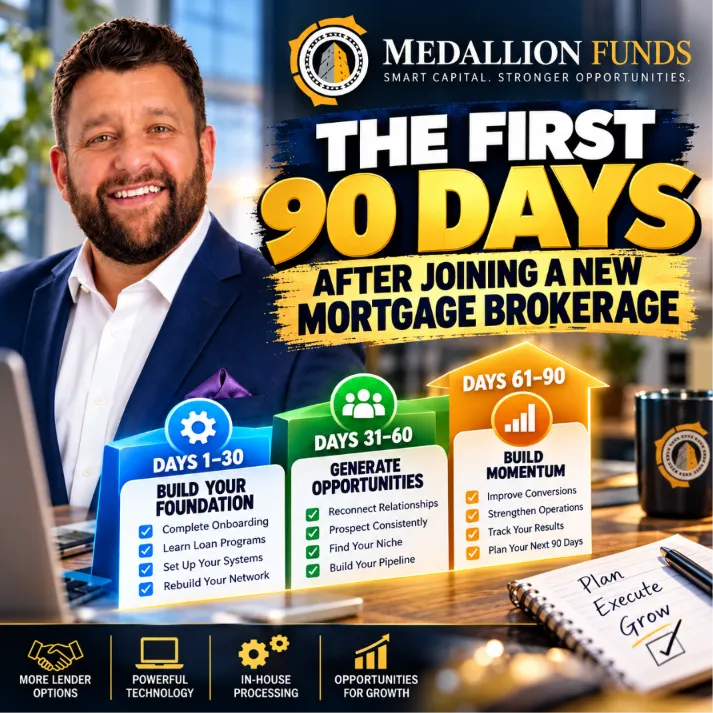
🚀 The First 90 Days at a New Mortgage Brokerage: Your Roadmap to Success 🏆
🚀 The First 90 Days at a New Mortgage Brokerage: Your Roadmap to Success 🏆
💼 Changing Mortgage Companies? 10 Steps to Build a Stronger Pipeline in Your First 90 Days 📈
________________________________________________________________________________
🚀 The First 90 Days at a New Mortgage Brokerage: Your Roadmap to Success
Changing mortgage companies can be one of the most important career decisions a loan officer makes.
Whether you're transitioning from a retail bank, leaving a correspondent lender, or joining a mortgage brokerage for the first time, your first 90 days can establish the foundation for your long-term success.
But here's something many mortgage professionals overlook:
Changing companies doesn't automatically change your production. Changing your strategy, systems, relationships, and execution does.
A new mortgage brokerage may offer access to more lenders, competitive loan programs, stronger technology, and greater flexibility. However, those advantages only create value when you know how to use them.
At Medallion Funds, we believe successful loan officers need more than a place to hang their license. They need the right tools, lender relationships, operational support, and a business development strategy designed for sustainable growth.
Here's a practical 90-day roadmap for making your transition successful.
Days 1–30: Build Your Foundation
Your first month should focus on understanding your new brokerage, learning its capabilities, and preparing your business for growth.
1. Complete Your Licensing and Compliance Transition
Before originating loans under your new brokerage, confirm that all required licensing, sponsorship, and regulatory requirements have been satisfied.
Your transition checklist should include:
·Confirming applicable NMLS sponsorship and state licensing requirements.
·Completing required onboarding and compliance training.
·Understanding advertising and marketing approval procedures.
·Reviewing company policies for borrower communication, disclosures, and data security.
·Establishing your business email, technology access, and document management systems.
Important: Never assume that joining a new company automatically authorizes you to originate loans. State licensing and sponsorship requirements must be satisfied before conducting regulated activities.
2. Learn Your New Mortgage Product Menu
One of the biggest potential advantages of joining a mortgage brokerage is gaining access to financing options beyond a single institution's products.
Depending on your brokerage's lender relationships, these may include:
Traditional residential mortgages
·Conventional loans
·FHA financing
·VA home loans
·USDA mortgages
·Jumbo financing
Specialty residential financing
·Doctor and dentist mortgage programs
·Bank statement loans
·Non-QM mortgages
·DSCR investment property loans
·Asset-utilization mortgages
·Bridge financing
Commercial financing opportunities
·SBA 7(a) and 504 financing
·Commercial investment property loans
·Multifamily mortgages
·Owner-occupied commercial financing
·Construction and development financing
Understanding these products can help you identify borrowers who may not fit conventional underwriting requirements.
Your goal during the first 30 days: Become proficient in identifying which loan programs fit which borrower scenarios.
3. Master Your Technology and Loan Origination Systems
Technology should improve your productivity—not become another obstacle.
Learn how to use your brokerage's:
·Customer relationship management (CRM) platform
·Loan origination system (LOS)
·Pricing and lender comparison tools
·Document collection and borrower portals
·Marketing automation capabilities
·Pipeline tracking and reporting
At Medallion Funds, our platform emphasizes technology, processing support, and access to a broad range of lending solutions.
For commercial opportunities, our relationship with the CommLoan Empower Program provides access to its CUPID™ commercial lending marketplace and a network of 700-plus lenders.
That expanded capability can help loan officers recognize opportunities beyond traditional residential mortgages, subject to licensing, program eligibility, and company procedures.
4. Communicate Your Transition to Your Professional Network
Your existing relationships may be among your most valuable business assets.
Develop a compliant communication strategy for:
·Real estate agents
·Builders
·Past clients
·Financial advisors
·CPAs
·Attorneys
·Business owners
·Commercial real estate professionals
Explain why you made the transition and, more importantly, how your expanded capabilities may benefit the people you serve.
Avoid making your announcement solely about compensation or your new company's name.
Instead, focus on the additional solutions and service you can provide.
30-Day Milestone: Complete onboarding, understand your lending platform, and establish a clear business development plan.
Days 31–60: Rebuild Relationships and Generate Opportunities
Once your systems are operational, the next priority is production activity.
5. Reconnect With Your Referral Partners
Successful mortgage originators rarely build sustainable businesses through occasional prospecting.
Consistent relationships drive opportunities.
Schedule conversations with your strongest referral partners and ask:
·What financing challenges are your clients experiencing?
·Which types of transactions are becoming more difficult to finance?
·Are you working with self-employed buyers or real estate investors?
·Do you have clients who may benefit from specialty loan programs?
·How can I make your transactions easier to manage?
The objective is to become a trusted financing resource—not simply another loan officer requesting referrals.
6. Develop Two or Three Specialized Lending Niches
Trying to market every mortgage product to everyone can dilute your message.
Instead, identify borrower segments that align with your expertise and local market.
Doctors and dentists: Specialty financing may help qualified healthcare professionals purchase homes while managing student loan obligations and preserving liquidity.
Self-employed borrowers: Bank statement and other Non-QM programs may offer alternative qualification approaches for borrowers with complex income documentation.
Real estate investors: DSCR loans and portfolio financing may provide solutions for qualifying rental property investments.
Veterans and military families: VA lending offers important benefits for eligible borrowers, including potentially no down payment and no monthly mortgage insurance.
Business owners: Commercial and SBA financing can create opportunities to help qualified borrowers purchase owner-occupied business real estate.
At Medallion Funds, we believe specialization can differentiate loan officers in a crowded mortgage market.
7. Establish a Consistent Marketing Strategy
Your marketing should reinforce your expertise and generate conversations.
Consider a weekly schedule that includes:
·Educational social media posts
·Short-form mortgage videos
·Referral partner outreach
·Mortgage program explainers
·Local networking
·Client follow-up
·Email newsletters
For example, a loan officer specializing in real estate investors could produce content explaining DSCR loans, blanket mortgages, cash-out refinancing, and rental property financing.
A loan officer targeting medical professionals might focus on physician mortgage programs, student debt considerations, and financing for practice owners.
60-Day Milestone: Establish a repeatable prospecting routine, reconnect with referral sources, and develop a measurable pipeline of qualified opportunities.
Days 61–90: Build Momentum and Optimize Your Business
By your third month, the focus should shift from learning the platform to improving your execution.
8. Evaluate Your Mortgage Pipeline
A healthy mortgage business requires more than a list of leads.
Review the performance of each stage:
1.New prospect inquiries
2.Initial borrower consultations
3.Applications received
4.Pre-approvals issued
5.Loans submitted
6.Loans approved
7.Loans closed and funded
Identify where opportunities are slowing down.
Are borrowers failing to complete applications? Are documentation issues delaying underwriting? Are referral partners sending leads that don't match your lending capabilities?
Understanding your conversion metrics can help you improve productivity without simply increasing your prospecting volume.
9. Strengthen Your Operational Relationships
A strong loan officer understands that closing loans is a team effort.
Build working relationships with:
·Loan processors
·Underwriters
·Account executives
·Closing coordinators
·Compliance personnel
·Brokerage leadership
Learn how to submit complete files, communicate expectations, and resolve problems early.
One of the most valuable qualities in a mortgage brokerage is the ability to get timely answers when a transaction becomes complicated.
Borrowers and referral partners remember the professionals who solve problems.
10. Create Your Next 90-Day Growth Plan
At the end of your first three months, review your progress and establish your next objectives.
Ask yourself:
·Which referral sources generated the strongest opportunities?
·Which loan programs attracted the most qualified borrowers?
·How many applications did I generate?
·What percentage of applications reached closing?
·Where did transactions experience delays?
·Which marketing activities produced meaningful conversations?
·What additional training would improve my performance?
Use those answers to build a business plan based on measurable activity and realistic production goals.
90-Day Milestone: Establish a repeatable business development system supported by clear performance metrics, strong operational relationships, and a growing pipeline.
Your First 90 Days: Sample Loan Officer Activity Scorecard
The following are illustrative activity targets—not production guarantees or industry benchmarks.
Activity | Days 1–30 | Days 31–60 | Days 61–90 |
Referral partner conversations | 15 | 25 | 30 |
Educational social posts | 8 | 12 | 12 |
Networking meetings | 4 | 6 | 8 |
Specialty program training sessions | 6 | 4 | 2 |
Pipeline reviews | Weekly | Weekly | Weekly |
Business development focus | Foundation | Prospecting | Conversion |
Adjust your targets based on your existing pipeline, market conditions, and business model.
The goal is to create consistency—not chase arbitrary numbers.
Why Mortgage Brokerage Platform Selection Matters
Not every mortgage brokerage provides the same resources.
When evaluating a new company, loan officers should look beyond compensation and consider the infrastructure supporting their business.
Important questions include:
Lender access: Does the brokerage offer financing solutions for a broad range of borrower scenarios?
Processing support: Will the operational structure help you deliver reliable service?
Technology: Does the company provide systems that simplify borrower communication and pipeline management?
Leadership: Can you access knowledgeable professionals when challenging situations arise?
Growth opportunities: Can you develop specialty lending niches or expand into commercial financing?
Business development: Does the company support the way you intend to build your mortgage business?
The best brokerage for one originator may not be the best fit for another.
The objective is to find a platform that supports your professional strengths and long-term business goals.
Why Consider Medallion Funds?
At Medallion Funds, our focus is helping mortgage professionals build sustainable businesses through lending options, technology, and operational support.
Our platform offers access to a range of residential and commercial mortgage solutions, including conventional financing, specialty residential lending, investment property financing, and commercial loan opportunities.
For originators interested in serving business owners and commercial real estate investors, our commercial lending relationships can provide additional opportunities to expand their expertise.
We believe that loan officers should be empowered to operate as knowledgeable financing advisors rather than simply quoting interest rates.
Whether you're an experienced loan officer considering a move or a mortgage professional exploring the brokerage model, the right environment can make a meaningful difference.
Frequently Asked Questions
How long does it take to become productive at a new mortgage brokerage?
The timeline varies based on licensing, existing referral relationships, pipeline transfers, product knowledge, and operational readiness. A structured 90-day plan can help establish productive habits, but it does not guarantee a particular funding timeline.
What should a loan officer do during the first 30 days?
Prioritize licensing and compliance, onboarding, product training, technology setup, and communication with your professional network.
Is moving from retail lending to mortgage brokerage difficult?
The transition can involve a learning curve, particularly when adapting to multiple wholesale lenders, different underwriting guidelines, and new technology. Strong training and operational support can help.
Can a mortgage broker offer more loan programs than a bank?
A mortgage broker may have access to multiple wholesale lenders and specialty programs, while a bank may primarily offer its own products. Actual options depend on the brokerage's lender relationships, licensing, and program availability.
Should new mortgage brokers specialize in a particular niche?
Specialization can improve marketing clarity and referral partner positioning. Doctors, dentists, self-employed borrowers, veterans, and real estate investors are examples of potentially valuable niches.
How should loan officers measure success during their first 90 days?
Track referral conversations, applications, qualified pipeline volume, conversion rates, closing performance, and business development activity—not just funded volume.
Final Thoughts: Your First 90 Days Can Shape Your Next Three Years
Joining a new mortgage brokerage represents an opportunity to rethink how you build your business.
But success requires more than a new logo, compensation agreement, or lender list.
It requires disciplined execution.
Days 1–30: Learn the platform and build your foundation.
Days 31–60: Reconnect, prospect, and generate opportunities.
Days 61–90: Improve conversion, strengthen operations, and build momentum.
The most successful transition is one that positions you to serve borrowers more effectively while developing a repeatable business model.
Ready to Explore a New Mortgage Brokerage Opportunity?
If you're considering changing mortgage companies and want to learn more about the opportunities available through Medallion Funds, let's have a conversation.
Bill Rapp
Partner & Director of Capital Advisory | Medallion Funds
Commercial Lending Nationwide
Residential Lending in AL, CA, CO, NV & TXBottom of Form
https://www.billrapponline.com/
https://findamortgagebroker.com/Profile/WilliamRappJr28883
https://billrapp.commloan.com/
https://billrapponline.com/financingfuturescre-houston-katy
https://houstoncommercialmortgage.com/
https://author.billrapponline.com
https://doctorvideo.billrapponline.com/
https://veteransvideo.billrapponline.com/
https://mortgageviking.billrapponline.com/
https://fha203h.billrapponline.com/
https://renovationvideo.billrapponline.com
https://medallionfunds.com/bill-rapp/
https://www.amazon.com/dp/B0F32Z5BH2
https://veed.cello.so/FOmzTty6oi9
https://buymeacoffee.com/vikingente3
https://creplaybookseries.billrapponline.com
https://creplaybook.billrapponline.com/
© Bill Rapp, Medallion Funds LLC, Director of Capital Advisory
10 Tips for First-Time Homebuyers
Buying your first home can be both exciting and nerve-wracking at the same time. With so many things to consider and....
How To Choose the Right Lender for You
Lorem Ipsum is simply dummy text of the printing and typesetting industry. Lorem Ipsum has been the industry's standard dummy
Refinancing youe loan and when to do it
Lorem Ipsum is simply dummy text of the printing and typesetting industry. Lorem Ipsum has been the industry's standard dummy
Copyright ©2021 | Mortgage Viking Team
Licensed to Do Business | NMLS # 228246
This is not an offer to enter into an agreement. Not all customers will qualify. Information, rates and programs are subject to change without notice. All products are subject to credit and property approval. Other restrictions and limitations may apply. Copyright © 2021 | Medallion Funds
Corporate | NMLS ID NMLS # 1825831
Corporate Address : 2651 N. Green Valley Pkwy STE. 101 Henderson, NV 89014
Corporate NMLS NMLS # 1825831 | Company Website: https://medallionfunds.com/bill-rapp/
Copyright ©2021 | Mortgage Viking Team Licensed to Do Business | NMLS # 228246
This is not an offer to enter into an agreement. Not all customers will qualify. Information, rates and programs are subject to change without notice. All products are subject to credit and property approval. Other restrictions and limitations may apply
Corporate | NMLS ID NMLS # 1825831
Corporate Address : 2651 N. Green Valley Pkwy STE. 101 Henderson, NV 89014 https://medallionfunds.com/bill-rapp/
Facebook
Instagram
X
LinkedIn
Youtube
TikTok