Low Rates.
Our rates are low, our application is quick and easy! We can get you clear to close in as little as 10 days!
Trusted By Agents With
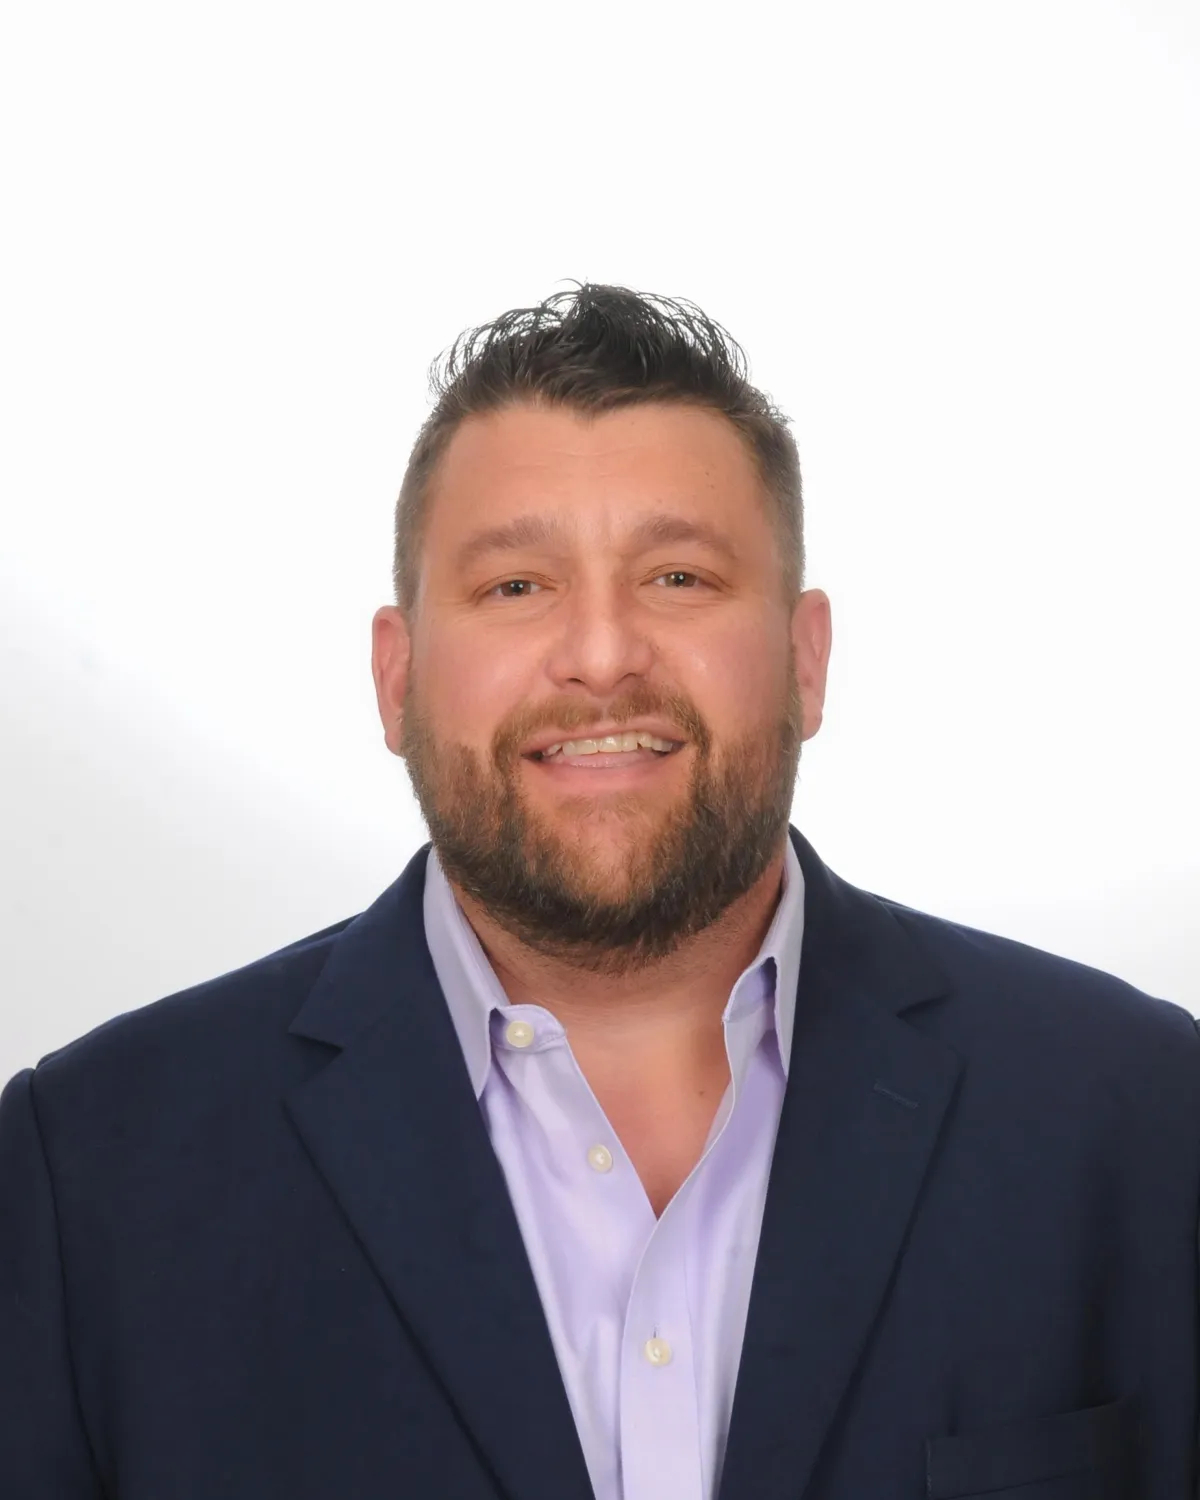
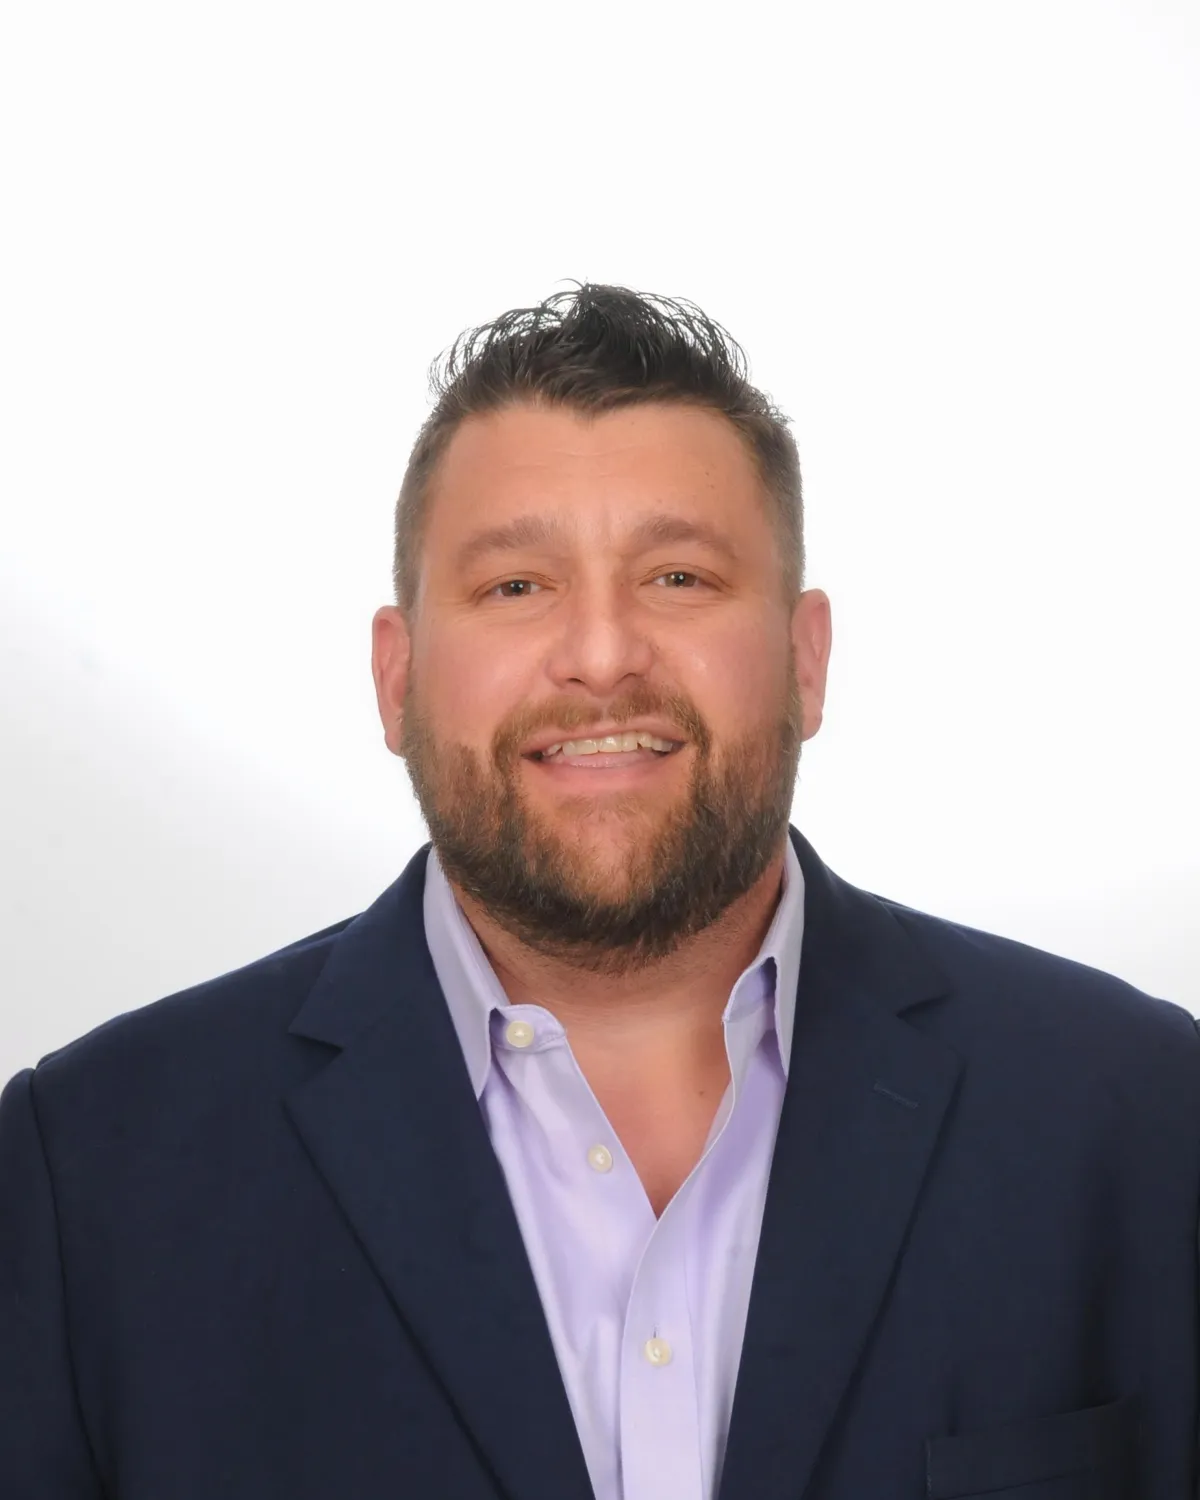
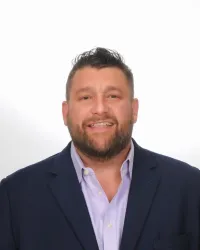
Meet Bill Rapp
NMLS ID # NMLS # 228246
Bill Rapp, CCIM is a Houston-based Capital Advisor at Medallion Funds, specializing in commercial real estate finance and strategic lending solutions. With over two decades of experience across brokerage and capital markets, Bill has worked with leading firms including eXp Commercial, NEXA Mortgage, Viking Enterprise LLC, and Sun Realty Houston.
A graduate of Texas A&M University with a BBA in Finance, Bill brings a disciplined, underwriting-first approach to every deal. His expertise spans commercial and residential financing, including asset-based lending, FHA financing, reverse mortgages, REO properties, and investment strategies for both single-family and commercial assets.
Known for his focus on structure over rate, Bill helps investors, business owners, and developers navigate complex transactions with clarity, precision, and a long-term wealth-building mindset.
The Client Experience
Great experience purchasing our first home! Bill was easy to reach and always able to answer any questions or concerns.

Loan Programs Available


Blogs
The Top 5 Mortgage Mistakes to Avoid
Buying your first home can be both exciting and nerve-wracking at the same time. With so many things to consider and....
Mortgage Do and
Do not list
Mortgages can be tricky, and it's easy to make mistakes that can end up costing you dearly. That's why we've put together this list....
Tips On How To Improve Your Credit Score
Let's talk about some ways you can improve your credit score! Your credit score is actually a big deal, and it can affect...
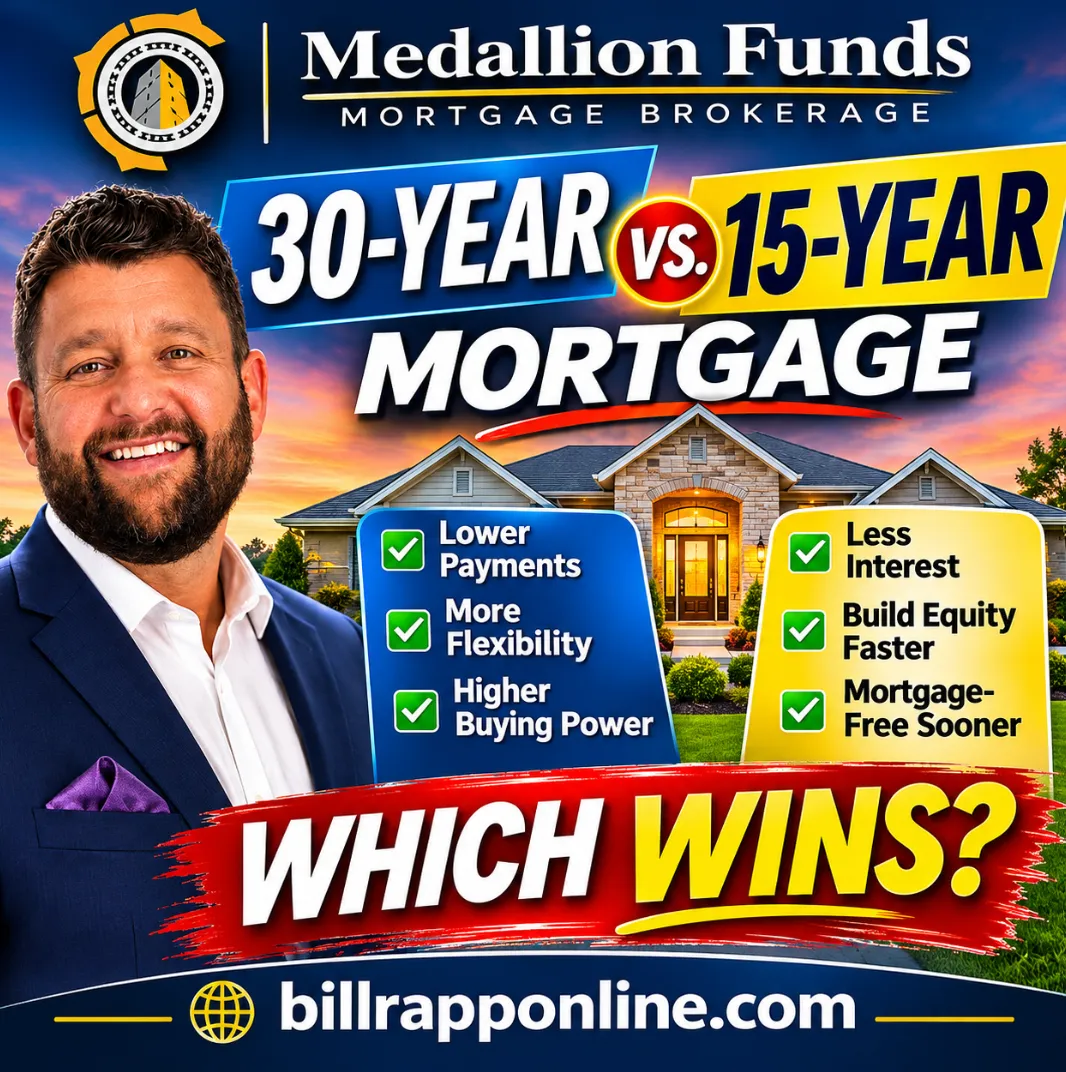
🏡 30-Year vs. 15-Year Mortgage: Which Is Better? 💰
🏡 30-Year vs. 15-Year Mortgage: Which Is Better? 💰
💵 15-Year vs. 30-Year Mortgage: Save Thousands? 🏠
_______________________________________________________________________________
🏡 30-Year vs. 15-Year Mortgage: Which Is Better?
Introduction: Is a Shorter Mortgage Really Better?
When buying a home or refinancing an existing mortgage, one of the biggest financial decisions you'll face is choosing between a 30-year mortgage and a 15-year mortgage.
At first glance, the decision seems simple.
A 30-year mortgage offers lower monthly payments, while a 15-year mortgage typically offers a lower interest rate and significantly less interest paid over the life of the loan.
But here's the question many homebuyers overlook:
Is paying off your mortgage faster always the smartest financial decision?
Not necessarily.
Your mortgage term affects more than your monthly payment. It influences your cash flow, purchasing power, financial flexibility, retirement planning, and ability to build wealth.
At Medallion Funds, I help homebuyers and homeowners evaluate mortgage options based on their financial objectives—not simply the lowest advertised interest rate.
Let's break down the tradeoffs.
1. What Is a 30-Year Fixed-Rate Mortgage?
A 30-year fixed-rate mortgage is a home loan repaid over 360 monthly payments, with an interest rate that remains unchanged throughout the loan term.
It is one of the most common mortgage structures in the United States.
Advantages of a 30-Year Mortgage
·Lower monthly payments: Spreading repayment over 30 years reduces the required principal and interest payment.
·Greater cash flow flexibility: More room in your monthly budget for savings, investments, emergencies, and other financial priorities.
·Potentially greater purchasing power: Lower required payments may allow some borrowers to qualify for a larger mortgage, subject to underwriting requirements.
·Predictable principal and interest: Your scheduled principal and interest payment stays consistent with a fixed-rate loan.
·Optional accelerated repayment: You can make additional principal payments to reduce the balance faster.
Disadvantages of a 30-Year Mortgage
·More interest paid over the full loan term, assuming the loan is held to maturity.
·Typically higher interest rates than comparable 15-year mortgages.
·Slower principal reduction during the early years.
·Greater potential for mortgage debt to extend into retirement.
Best suited for: First-time homebuyers, families prioritizing monthly affordability, borrowers with variable income, and homeowners who value financial flexibility.
2. What Is a 15-Year Fixed-Rate Mortgage?
A 15-year fixed-rate mortgage is repaid over 180 monthly payments.
Because the repayment period is shorter, the required monthly payment is substantially higher than that of a comparable 30-year mortgage.
However, 15-year mortgages often carry lower interest rates.
Advantages of a 15-Year Mortgage
·Lower total interest expense: A shorter repayment schedule can save substantial interest over the loan's lifetime.
·Faster equity accumulation: More of each payment goes toward principal reduction.
·Earlier mortgage payoff: Eliminate scheduled mortgage debt in half the time.
·Potentially lower interest rate: Lenders often price shorter-term fixed-rate mortgages more favorably.
·Retirement planning benefits: Paying off the mortgage before retirement can reduce future required living expenses.
Disadvantages of a 15-Year Mortgage
·Significantly higher monthly payments.
·Less room for unexpected expenses.
·Potentially reduced purchasing power.
·More cash committed to mortgage payments rather than other investments or priorities.
Best suited for: Homeowners with stable incomes, substantial emergency reserves, manageable debt obligations, and a strong desire to eliminate mortgage debt faster.
3. 30-Year vs. 15-Year Mortgage: Monthly Payment Comparison
Let's compare two hypothetical fixed-rate mortgages with the same $350,000 loan amount.
For illustration, assume:
·30-year mortgage interest rate: 6.50%
·15-year mortgage interest rate: 5.75%
These rates are hypothetical examples, not current lender quotes or advertised loan offers.
Mortgage Comparison | 30-Year Fixed | 15-Year Fixed |
Loan amount | $350,000 | $350,000 |
Interest rate | 6.50% | 5.75% |
Loan term | 360 months | 180 months |
Monthly principal & interest | $2,212 | $2,907 |
Total interest over full term | $446,442 | $173,108 |
Total principal & interest | $796,442 | $523,108 |
Illustrative figures are rounded. Actual loan terms, costs, and payments vary.
What Do These Numbers Mean?
The 15-year mortgage requires approximately $695 more per month.
However, over the full scheduled loan term, it saves approximately $273,334 in interest.
That's a substantial difference.
But here's the important consideration:
What else could you accomplish with an additional $695 in monthly cash flow?
That question should be part of your mortgage decision.
4. The Hidden Advantage of a 30-Year Mortgage: Financial Flexibility
A lower mortgage payment can provide meaningful financial flexibility.
For example, a homeowner choosing a 30-year mortgage may have additional monthly funds available for:
·Building emergency savings.
·Contributing to retirement accounts.
·Paying off higher-interest debt.
·Funding college education.
·Investing in income-producing assets.
·Managing unexpected household expenses.
A 30-year mortgage doesn't necessarily mean you must take 30 years to repay the loan.
You can choose a 30-year mortgage and voluntarily make additional principal payments.
This approach offers flexibility: accelerate repayment when your finances allow, while maintaining a lower required payment during challenging months.
However, the tradeoff matters.
If you select a 30-year mortgage and consistently make only the minimum payment, you'll generally accumulate equity more slowly and pay more interest than with a comparable 15-year loan.
Also, making additional payments toward a 30-year mortgage does not automatically recreate the interest savings of a 15-year mortgage with a lower interest rate.
5. Which Mortgage Builds Home Equity Faster?
A 15-year mortgage generally builds equity faster through scheduled principal repayment.
Home equity represents the difference between your property's market value and the outstanding mortgage balance.
For example, on the hypothetical $350,000 loans described above, after five years of scheduled payments:
·The 30-year mortgage would have approximately $328,000 remaining.
·The 15-year mortgage would have approximately $278,000 remaining.
That represents approximately $50,000 more principal reduction with the 15-year mortgage.
This difference comes from repayment, not appreciation. Both loans would benefit from the same hypothetical property appreciation, assuming the same home and starting balance.
Faster equity growth may help homeowners build long-term net worth, reduce leverage, or prepare for future financial needs.
However, equity is not the same as readily accessible cash. Accessing home equity generally requires selling the property or obtaining additional financing.
6. Should You Choose a 15-Year Mortgage to Save on Interest?
Saving interest is important, but it shouldn't be the only consideration.
Before selecting a 15-year mortgage, ask yourself:
Can I comfortably afford the higher payment?
A mortgage payment should leave room for everyday living expenses, property maintenance, savings, and unexpected financial events.
Do I have adequate emergency savings?
A lower loan balance provides financial benefits, but cash reserves may be more useful during a temporary loss of income or major repair.
Am I carrying higher-interest debt?
Paying off expensive revolving debt may deserve priority over accelerating a lower-rate mortgage.
Am I saving enough for retirement?
A shorter mortgage shouldn't automatically come at the expense of long-term retirement planning.
How long will I own the property?
If you expect to sell or refinance within several years, comparing interest costs and loan balances over your anticipated holding period may be more relevant than comparing lifetime interest totals.
7. Can You Pay Off a 30-Year Mortgage in 15 Years?
Yes.
A homeowner with a 30-year mortgage can often accelerate principal repayment by making additional payments.
Common approaches include:
·Adding a fixed amount to each monthly payment.
·Making an extra principal payment annually.
·Applying bonuses or other irregular income toward principal.
·Using a biweekly payment arrangement, where properly structured and applied.
For example, if you have a 30-year mortgage but receive a substantial annual bonus, you may choose to apply some of that income toward principal.
This can reduce future interest expense and shorten the effective repayment period.
Before making additional payments, confirm how your servicer applies them and whether any prepayment restrictions apply.
Importantly, a 30-year loan paid off in 15 years may still cost more in interest than a 15-year loan originally priced at a lower rate.
8. How Does Mortgage Term Affect Qualification?
Mortgage lenders evaluate several factors when determining eligibility, including:
·Credit history and credit scores.
·Gross qualifying income.
·Debt-to-income ratio (DTI).
·Down payment and available assets.
·Employment or business income documentation.
·Loan program requirements.
Because a 15-year mortgage has a higher required monthly payment, it may increase your debt-to-income ratio compared with a 30-year mortgage.
This can affect the loan amount for which you qualify.
However, qualifying for a larger mortgage does not automatically mean purchasing a more expensive home is financially appropriate.
Your comfortable housing budget should guide your loan decision—not simply the maximum amount a lender will approve.
9. Don't Forget Taxes, Insurance, and Mortgage Insurance
When comparing mortgage terms, principal and interest are only part of the equation.
Your total monthly housing payment may also include:
·Property taxes.
·Homeowners insurance.
·Flood insurance, where applicable.
·Mortgage insurance, where applicable.
·HOA dues.
These expenses may change over time, even with a fixed-rate mortgage.
This is especially important for Texas homebuyers, where property taxes and insurance can represent a meaningful portion of total housing costs.
Always compare the complete monthly housing obligation, not just the principal and interest payment.
10. Why Working With a Mortgage Broker Matters
Not every lender offers the same combination of interest rates, closing costs, loan programs, and underwriting requirements.
As a mortgage broker, my role is to help borrowers compare available financing options and understand how different loan structures affect their finances.
At Medallion Funds, we can evaluate options based on borrower eligibility and available lender programs, including:
·30-year fixed-rate mortgages.
·15-year fixed-rate mortgages.
·Conventional mortgage financing.
·FHA and VA home loans.
·Jumbo mortgages.
·Doctor and professional mortgage programs.
·Refinancing strategies.
A meaningful mortgage comparison should include interest rate, APR, lender fees, required monthly payment, expected loan balance, and the borrower's anticipated ownership timeline.
Final Verdict: Is a 15-Year or 30-Year Mortgage Better?
There is no universally superior mortgage term.
Choose a 30-year mortgage when: Lower required monthly payments, financial flexibility, cash reserves, and budget stability are priorities.
Consider a 15-year mortgage when: You can comfortably afford higher payments, want to reduce interest expense, and prioritize faster debt elimination.
For some homeowners, a 30-year mortgage combined with disciplined additional principal payments offers a useful middle ground.
For others, the lower interest rate and faster payoff associated with a 15-year mortgage may provide greater value.
The best mortgage is not necessarily the one with the shortest term or lowest interest rate.
It's the mortgage that supports your financial goals while remaining affordable through changing circumstances.
Ready to Compare Your Mortgage Options?
I'm Bill Rapp, CCIM, Director of Capital Advisory at Medallion Funds.
Whether you're buying your first home, moving into a larger property, or considering a refinance, I can help you evaluate the tradeoffs between mortgage terms and available financing options.
Bill Rapp
Partner & Director of Capital Advisory | Medallion Funds
Commercial Lending Nationwide
Residential Lending in AL, CA, CO, NV & TXBottom of Form
https://www.billrapponline.com/
https://findamortgagebroker.com/Profile/WilliamRappJr28883
https://billrapp.commloan.com/
https://billrapponline.com/financingfuturescre-houston-katy
https://houstoncommercialmortgage.com/
https://author.billrapponline.com
https://doctorvideo.billrapponline.com/
https://veteransvideo.billrapponline.com/
https://mortgageviking.billrapponline.com/
https://fha203h.billrapponline.com/
https://renovationvideo.billrapponline.com
https://medallionfunds.com/bill-rapp/
https://www.amazon.com/dp/B0F32Z5BH2
https://veed.cello.so/FOmzTty6oi9
https://buymeacoffee.com/vikingente3
https://creplaybookseries.billrapponline.com
https://creplaybook.billrapponline.com/
© Bill Rapp, Medallion Funds LLC, Director of Capital Advisory
10 Tips for First-Time Homebuyers
Buying your first home can be both exciting and nerve-wracking at the same time. With so many things to consider and....
How To Choose the Right Lender for You
Lorem Ipsum is simply dummy text of the printing and typesetting industry. Lorem Ipsum has been the industry's standard dummy
Refinancing youe loan and when to do it
Lorem Ipsum is simply dummy text of the printing and typesetting industry. Lorem Ipsum has been the industry's standard dummy
Copyright ©2021 | Mortgage Viking Team
Licensed to Do Business | NMLS # 228246
This is not an offer to enter into an agreement. Not all customers will qualify. Information, rates and programs are subject to change without notice. All products are subject to credit and property approval. Other restrictions and limitations may apply. Copyright © 2021 | Medallion Funds
Corporate | NMLS ID NMLS # 1825831
Corporate Address : 2651 N. Green Valley Pkwy STE. 101 Henderson, NV 89014
Corporate NMLS NMLS # 1825831 | Company Website: https://medallionfunds.com/bill-rapp/
Copyright ©2021 | Mortgage Viking Team Licensed to Do Business | NMLS # 228246
This is not an offer to enter into an agreement. Not all customers will qualify. Information, rates and programs are subject to change without notice. All products are subject to credit and property approval. Other restrictions and limitations may apply
Corporate | NMLS ID NMLS # 1825831
Corporate Address : 2651 N. Green Valley Pkwy STE. 101 Henderson, NV 89014 https://medallionfunds.com/bill-rapp/
Facebook
Instagram
X
LinkedIn
Youtube
TikTok