
The Top 5 Mortgage Mistakes to Avoid
Buying a home can be an exciting and rewarding experience, but it can also be a daunting and overwhelming process, especially for first-time homebuyers.
.
Mortgages are a significant financial commitment, and making mistakes during the process can have serious consequences. In this blog post, we'll explore the top 5 mortgage mistakes to avoid.
1. Failing to Check and Improve Your
Credit Score
Your credit score plays a significant role in determining your eligibility for a mortgage and the interest rate you'll receive. Many first-time homebuyers make the mistake of failing to check their credit score or not taking steps to improve it before applying for a mortgage.
,
To avoid this mistake, check your credit score and take steps to improve it if necessary. This may include paying off outstanding debts, making on-time payments, and disputing any errors on your credit report. A higher credit score can lead to a lower interest rate and a more favorable mortgage offer.
2. Ignoring
Closing Costs
Another common mistake is ignoring closing costs. Many first-time homebuyers are unaware of the various fees associated with closing a mortgage, such as attorney fees, title search fees, and appraisal fees. These costs can add up quickly and significantly impact the total cost of the mortgage.
.
To avoid this mistake, research the average closing costs in your area and budget accordingly. Be sure to factor in these costs when considering the overall cost of the home.
2. Ignoring Closing Costs
Another common mistake is ignoring closing costs. Many first-time homebuyers are unaware of the various fees associated with closing a mortgage, such as attorney fees, title search fees, and appraisal fees. These costs can add up quickly and significantly impact the total cost of the mortgage.
.
To avoid this mistake, research the average closing costs in your area and budget accordingly. Be sure to factor in these costs when considering the overall cost of the home.

3. Not Getting Pre-Approved
Getting pre-approved for a mortgage is an essential step in the home buying process. Pre-approval gives you a clear idea of how much you can afford to spend on a home and helps you avoid the disappointment of falling in love with a home you can't afford.
.
To avoid this mistake, get pre-approved for a mortgage before you start shopping for a home. This will help you narrow down your search to homes that are within your budget and prevent you from wasting time on homes that are out of reach.
4. Taking on Too Much Debt
Taking on too much debt before or during the mortgage process can have serious consequences. Lenders look at your debt-to-income ratio when determining your eligibility for a mortgage. If you have too much debt, you may not qualify for a mortgage or may be offered a higher interest rate.
.
To avoid this mistake, avoid taking on new debt before or during the mortgage process. This includes opening new credit cards, taking out a car loan, or making large purchases on existing credit cards.
4. Taking on Too
Much Debt
Taking on too much debt before or during the mortgage process can have serious consequences. Lenders look at your debt-to-income ratio when determining your eligibility for a mortgage. If you have too much debt, you may not qualify for a mortgage or may be offered a higher interest rate.
.
To avoid this mistake, avoid taking on new debt before or during the mortgage process. This includes opening new credit cards, taking out a car loan, or making large purchases on existing credit cards.
5. Choosing the Wrong Mortgage
Choosing the wrong mortgage can be a costly mistake. There are various types of mortgages available, and each has its pros and cons. Choosing the wrong mortgage can lead to higher interest rates, higher monthly payments, and a more significant financial burden in the long run.
.
To avoid this mistake, research the different types of mortgages available and choose the one that best fits your financial situation and goals. Don't be afraid to ask your lender questions and seek advice from a financial advisor.
Blogs
The Top 5 Mortgage Mistakes to Avoid
Buying your first home can be both exciting and nerve-wracking at the same time. With so many things to consider and....
Mortgage Do and
Do not list
Mortgages can be tricky, and it's easy to make mistakes that can end up costing you dearly. That's why we've put together this list....
Tips On How To Improve Your Credit Score
Let's talk about some ways you can improve your credit score! Your credit score is actually a big deal, and it can affect...
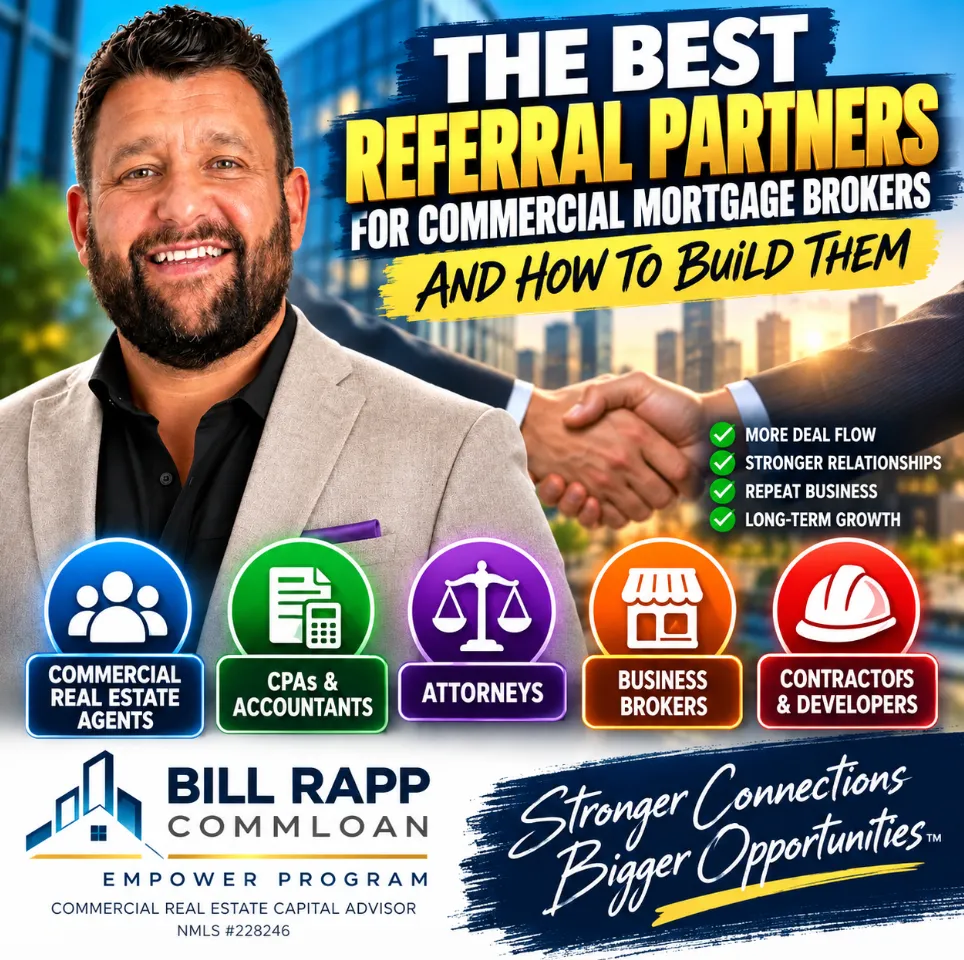
🏢 The Best Referral Partners for Commercial Mortgage Brokers—and How to Build Them 🤝
🏢 The Best Referral Partners for Commercial Mortgage Brokers—and How to Build Them 🤝
🤝 Commercial Mortgage Broker Lead Generation: Build Referral Partners Who Create More Deal Flow 📈
________________________________________________________________________________
The Best Referral Partners for Commercial Mortgage Brokers—and How to Build Them
Commercial mortgage brokerage is fundamentally a relationship business.
Technology can help identify lenders. Marketing can generate inquiries. Advertising can create awareness. But some of the strongest commercial real estate financing opportunities still originate from something much simpler: a trusted professional making an introduction.
For commercial mortgage brokers, building a strong referral network can create a consistent pipeline of borrowers who already have a degree of trust before the first financing conversation begins.
The key is not simply meeting more people. It is developing relationships with professionals who regularly encounter commercial real estate owners, investors and business owners who need capital.
Why Referral Partners Matter in Commercial Mortgage Brokerage
Commercial financing needs often emerge during another transaction or business decision.
An investor may be preparing to acquire a property. A business owner may be considering buying the building they currently lease. An accountant may identify an upcoming balloon payment. An attorney may be working on a partnership restructuring. A commercial real estate broker may have a buyer who needs financing before submitting an offer.
In each situation, someone else may recognize the financing need before the borrower ever contacts a commercial mortgage broker.
That makes referral relationships an important component of commercial mortgage broker lead generation.
A productive referral network can potentially provide:
·More qualified introductions
·Earlier involvement in transactions
·Better-prepared borrowers
·More consistent deal flow
·Opportunities for repeat business
·Stronger professional relationships
The objective should not be collecting contacts. It should be becoming a useful financing resource to professionals whose clients periodically need capital.
1. Commercial Real Estate Brokers
Commercial real estate brokers can be natural referral partners because financing and real estate transactions are closely connected.
Investment sales brokers may have buyers who need acquisition financing. Tenant representatives may work with business owners considering an owner-occupied purchase. Listing brokers may encounter buyers who need help understanding financing before making an offer.
A capital advisor can add value by helping evaluate questions such as:
How much can the property support?
What DSCR will a lender require?
How much equity will the borrower need?
Would conventional, SBA, bridge or another financing structure make sense?
The earlier these questions are addressed, the easier it may be to identify potential financing obstacles before they threaten the transaction.
2. CPAs and Accountants
CPAs often have extensive visibility into their clients' businesses, investments and financial objectives.
They may know when a client is preparing to purchase a building, refinance debt, acquire another business, expand operations or make a major capital investment.
That makes accountants potentially valuable referral partners for commercial mortgage brokers.
The relationship should be reciprocal in value. Rather than repeatedly asking a CPA for referrals, become a resource who can help their clients understand commercial financing options, lender requirements and the financial implications of different capital structures.
3. Commercial Real Estate Attorneys
Commercial real estate attorneys are frequently involved in transactions long before financing closes.
They may assist with purchase agreements, entity formation, partnership agreements, title matters, leases and transaction structuring.
These situations can reveal financing requirements.
Building relationships with commercial real estate attorneys can therefore create opportunities for introductions while also giving the mortgage broker a trusted legal resource when borrowers need appropriate counsel.
4. Business Brokers
Business acquisitions frequently involve more than simply purchasing a company.
A transaction may include real estate, equipment, inventory, goodwill, renovations or working capital.
That creates opportunities for financing structures such as SBA 7(a), SBA 504, conventional commercial financing and other business-purpose loan programs.
A commercial mortgage broker who understands the complete capital stack can become a useful partner for business brokers trying to get acquisitions across the finish line.
5. Contractors, Builders and Developers
Construction and development projects create financing needs at multiple stages.
A client might need land financing, construction financing, bridge capital, permanent financing or a refinance after stabilization.
Contractors and developers frequently know about these projects well before a lender becomes involved.
Commercial mortgage brokers who develop relationships within the construction and development community may gain access to financing opportunities earlier in the project's lifecycle.
6. Residential Mortgage Professionals
Residential mortgage professionals can also be valuable commercial referral partners.
Their clients may own rental portfolios, operate businesses, purchase commercial properties or need financing outside the residential lender's product scope.
Instead of turning those opportunities away, a residential mortgage professional can refer the commercial transaction to a trusted commercial financing specialist while maintaining the original client relationship.
The same principle works in reverse. Commercial mortgage brokers routinely encounter clients who need residential financing and can refer those opportunities back.
7. Bankers and Credit Union Relationship Managers
This one surprises some people.
Banks can be excellent referral sources for commercial mortgage brokers.
A bank may like the borrower but be unable to approve a particular transaction because of property type, loan size, leverage, concentration limits, geographic restrictions, underwriting policy or another credit parameter.
A commercial mortgage broker with access to a broader lender marketplace may be able to explore alternatives.
Maintaining relationships with bankers can therefore create a mutually beneficial solution: the banker preserves the broader relationship while the borrower gets another avenue for financing.
How Do You Actually Build Strong Referral Partnerships?
The first principle is simple:
Do not build the relationship around asking for leads. Build it around creating value.
Learn what your referral partner does, who they serve and what types of problems they regularly encounter.
Then make yourself useful.
Share relevant financing information. Explain changes in lender requirements. Help evaluate difficult scenarios. Make introductions when appropriate. Refer business when possible.
Most importantly, protect their relationship with the client.
If someone refers a borrower to you, communicate professionally, respond quickly and keep the referring professional informed when appropriate and authorized.
Your performance reflects on the person who made the introduction.
Make It Easy to Refer Business to You
Referral partners need to understand exactly what you do.
"I'm a commercial mortgage broker" may be too broad.
Instead, clearly explain the types of financing situations you can evaluate.
For example:
Commercial real estate acquisitions. Refinances. Cash-out transactions. Owner-occupied properties. Investment properties. Multifamily. SBA financing. Bridge loans. Construction and other business-purpose real estate financing.
The clearer your positioning, the easier it becomes for someone to recognize an opportunity and think of you.
Become a Resource Before You Need the Referral
One of the strongest ways to build referral relationships is to provide value before asking for anything.
If a commercial broker has a buyer who is unsure how much they can borrow, help analyze the financing.
If a CPA has a client facing a balloon payment, help estimate refinance proceeds.
If a business broker has a complicated acquisition, help evaluate the capital stack.
Not every conversation will become a loan.
That is okay.
Consistently demonstrating expertise can build the credibility that produces future introductions.
Use Technology Without Losing the Relationship
Technology can dramatically improve commercial mortgage brokerage.
Through the CommLoan Empower Program, I can use technology and lender-marketplace resources to evaluate commercial financing opportunities across a broad range of potential capital sources.
But technology does not replace relationships.
It strengthens what an advisor can do after the introduction occurs.
The referral partner provides trust and context. The financing platform expands the ability to evaluate potential lending solutions. The advisor connects the two.
The Compounding Effect of a Referral Network
A strong referral network does not have to contain hundreds of people.
A smaller group of productive relationships can generate meaningful deal flow.
Imagine developing strong relationships with several commercial real estate brokers, CPAs, attorneys, business brokers, bankers and developers.
Each professional works with numerous clients throughout the year.
Instead of constantly searching for individual borrowers, you are building relationships with people who regularly encounter borrowers.
That is where referral-based commercial mortgage lead generation can begin to compound.
Final Takeaway
The best referral partners for commercial mortgage brokers are not simply people with large contact lists.
They are professionals who regularly encounter commercial real estate investors and business owners at the moment a financing need develops.
Build those relationships by becoming useful.
Understand their business. Provide financing expertise. Communicate well. Protect their client relationships. Refer opportunities back when appropriate.
Over time, strong professional partnerships can produce something far more valuable than a single transaction:
a repeatable source of relationships, introductions and commercial loan opportunities.
Need Help Evaluating a Commercial Financing Opportunity?
I'm Bill Rapp with the CommLoan Empower Program.
If you are a commercial real estate professional, CPA, attorney, business broker, banker, developer—or simply have a client who needs commercial financing—I would be happy to evaluate the scenario and help identify potential financing options.
Top of Form
Bottom of Form
Bill Rapp, CCIM
Director | CommLoan
📞 281-222-0433
📧 [email protected]
🌐 https://billrapp.commloan.com/
🌐 https://HoustonCommercialMortgage.com/
Commercial Real Estate Financing Nationwide
https://billrapp.commloan.com/
https://author.billrapponline.com/
https://www.amazon.com/dp/B0F32Z5BH2
https://veed.cello.so/FOmzTty6oi9
https://buymeacoffee.com/vikingente3
https://creplaybookseries.billrapponline.com
https://creplaybook.billrapponline.com/
©Bill Rapp, CCIM - Director - CommLoan
10 Tips for First-Time Homebuyers
Buying your first home can be both exciting and nerve-wracking at the same time. With so many things to consider and....
How To Choose the Right Lender for You
Lorem Ipsum is simply dummy text of the printing and typesetting industry. Lorem Ipsum has been the industry's standard dummy
Refinancing youe loan and when to do it
Lorem Ipsum is simply dummy text of the printing and typesetting industry. Lorem Ipsum has been the industry's standard dummy
🧮 Renovation ROI Calculator
🛠️ Renovation ROI Calculator 💰
Copyright ©2021 | Mortgage Viking Team
Licensed to Do Business | NMLS # 228246
This is not an offer to enter into an agreement. Not all customers will qualify. Information, rates and programs are subject to change without notice. All products are subject to credit and property approval. Other restrictions and limitations may apply. Copyright © 2021 | Medallion Funds
Corporate | NMLS ID NMLS # 1825831
Corporate Address : 2651 N. Green Valley Pkwy STE. 101 Henderson, NV 89014
Corporate NMLS NMLS # 1825831 | Company Website: https://medallionfunds.com/bill-rapp/
Copyright ©2021 | Mortgage Viking Team Licensed to Do Business | NMLS # 228246
This is not an offer to enter into an agreement. Not all customers will qualify. Information, rates and programs are subject to change without notice. All products are subject to credit and property approval. Other restrictions and limitations may apply
Corporate | NMLS ID NMLS # 1825831
Corporate Address : 2651 N. Green Valley Pkwy STE. 101 Henderson, NV 89014 https://medallionfunds.com/bill-rapp/