
The Top 5 Mortgage Mistakes to Avoid
Buying a home can be an exciting and rewarding experience, but it can also be a daunting and overwhelming process, especially for first-time homebuyers.
.
Mortgages are a significant financial commitment, and making mistakes during the process can have serious consequences. In this blog post, we'll explore the top 5 mortgage mistakes to avoid.
1. Failing to Check and Improve Your
Credit Score
Your credit score plays a significant role in determining your eligibility for a mortgage and the interest rate you'll receive. Many first-time homebuyers make the mistake of failing to check their credit score or not taking steps to improve it before applying for a mortgage.
,
To avoid this mistake, check your credit score and take steps to improve it if necessary. This may include paying off outstanding debts, making on-time payments, and disputing any errors on your credit report. A higher credit score can lead to a lower interest rate and a more favorable mortgage offer.
2. Ignoring
Closing Costs
Another common mistake is ignoring closing costs. Many first-time homebuyers are unaware of the various fees associated with closing a mortgage, such as attorney fees, title search fees, and appraisal fees. These costs can add up quickly and significantly impact the total cost of the mortgage.
.
To avoid this mistake, research the average closing costs in your area and budget accordingly. Be sure to factor in these costs when considering the overall cost of the home.
2. Ignoring Closing Costs
Another common mistake is ignoring closing costs. Many first-time homebuyers are unaware of the various fees associated with closing a mortgage, such as attorney fees, title search fees, and appraisal fees. These costs can add up quickly and significantly impact the total cost of the mortgage.
.
To avoid this mistake, research the average closing costs in your area and budget accordingly. Be sure to factor in these costs when considering the overall cost of the home.

3. Not Getting Pre-Approved
Getting pre-approved for a mortgage is an essential step in the home buying process. Pre-approval gives you a clear idea of how much you can afford to spend on a home and helps you avoid the disappointment of falling in love with a home you can't afford.
.
To avoid this mistake, get pre-approved for a mortgage before you start shopping for a home. This will help you narrow down your search to homes that are within your budget and prevent you from wasting time on homes that are out of reach.
4. Taking on Too Much Debt
Taking on too much debt before or during the mortgage process can have serious consequences. Lenders look at your debt-to-income ratio when determining your eligibility for a mortgage. If you have too much debt, you may not qualify for a mortgage or may be offered a higher interest rate.
.
To avoid this mistake, avoid taking on new debt before or during the mortgage process. This includes opening new credit cards, taking out a car loan, or making large purchases on existing credit cards.
4. Taking on Too
Much Debt
Taking on too much debt before or during the mortgage process can have serious consequences. Lenders look at your debt-to-income ratio when determining your eligibility for a mortgage. If you have too much debt, you may not qualify for a mortgage or may be offered a higher interest rate.
.
To avoid this mistake, avoid taking on new debt before or during the mortgage process. This includes opening new credit cards, taking out a car loan, or making large purchases on existing credit cards.
5. Choosing the Wrong Mortgage
Choosing the wrong mortgage can be a costly mistake. There are various types of mortgages available, and each has its pros and cons. Choosing the wrong mortgage can lead to higher interest rates, higher monthly payments, and a more significant financial burden in the long run.
.
To avoid this mistake, research the different types of mortgages available and choose the one that best fits your financial situation and goals. Don't be afraid to ask your lender questions and seek advice from a financial advisor.
Blogs
The Top 5 Mortgage Mistakes to Avoid
Buying your first home can be both exciting and nerve-wracking at the same time. With so many things to consider and....
Mortgage Do and
Do not list
Mortgages can be tricky, and it's easy to make mistakes that can end up costing you dearly. That's why we've put together this list....
Tips On How To Improve Your Credit Score
Let's talk about some ways you can improve your credit score! Your credit score is actually a big deal, and it can affect...
🏡 Texas Housing Market 2027: Buy Now or Wait?
🏡 Texas Housing Market 2027: Buy Now or Wait?
🚨 Texas Home Prices Fall, Mortgage Rates Rise: Now What?
______________________________________________________________________________
🏡 Texas Housing Market 2027: Should You Buy Now or Wait?
What happens if Texas home prices fall in 2027, but mortgage rates rise? The answer could change your homebuying strategy.
For homebuyers across Houston, Katy, Fulshear, Dallas, Austin, San Antonio, and other Texas markets, one question continues to dominate conversations:
Should I buy a house now or wait until 2027?
Some buyers expect home prices to decline. Others believe mortgage rates will fall, creating better affordability. But what happens if the market moves in opposite directions?
Imagine buying a home for less money next year, only to discover that your monthly mortgage payment is actually higher.
That scenario is entirely possible.
I'm Bill Rapp, CCIM, Capital Advisor with Medallion Funds. I work with homebuyers, homeowners, and real estate investors to evaluate mortgage financing options and make informed real estate decisions.
Let's examine the numbers behind buying a Texas home in late 2026 versus waiting until 2027.
Texas Housing Market Outlook: What Could Happen in 2027?
Texas housing markets are not moving in perfect synchronization.
Houston, Dallas–Fort Worth, Austin, and San Antonio have different housing inventories, employment trends, construction activity, and neighborhood-level supply-and-demand conditions.
Three factors will be particularly important heading into 2027:
1. Housing inventory: More available homes can give buyers additional negotiating leverage, particularly when properties remain listed longer.
2. Mortgage interest rates: Even relatively small rate changes can materially affect purchasing power and monthly payments.
3. Local home prices: Prices may soften in some neighborhoods while remaining stable or increasing in others.
The key is understanding that lower home prices do not automatically translate into more affordable homeownership.
Buy Now vs. Wait Until 2027: The $400,000 Texas Home Example
Let's compare two hypothetical purchasing scenarios.
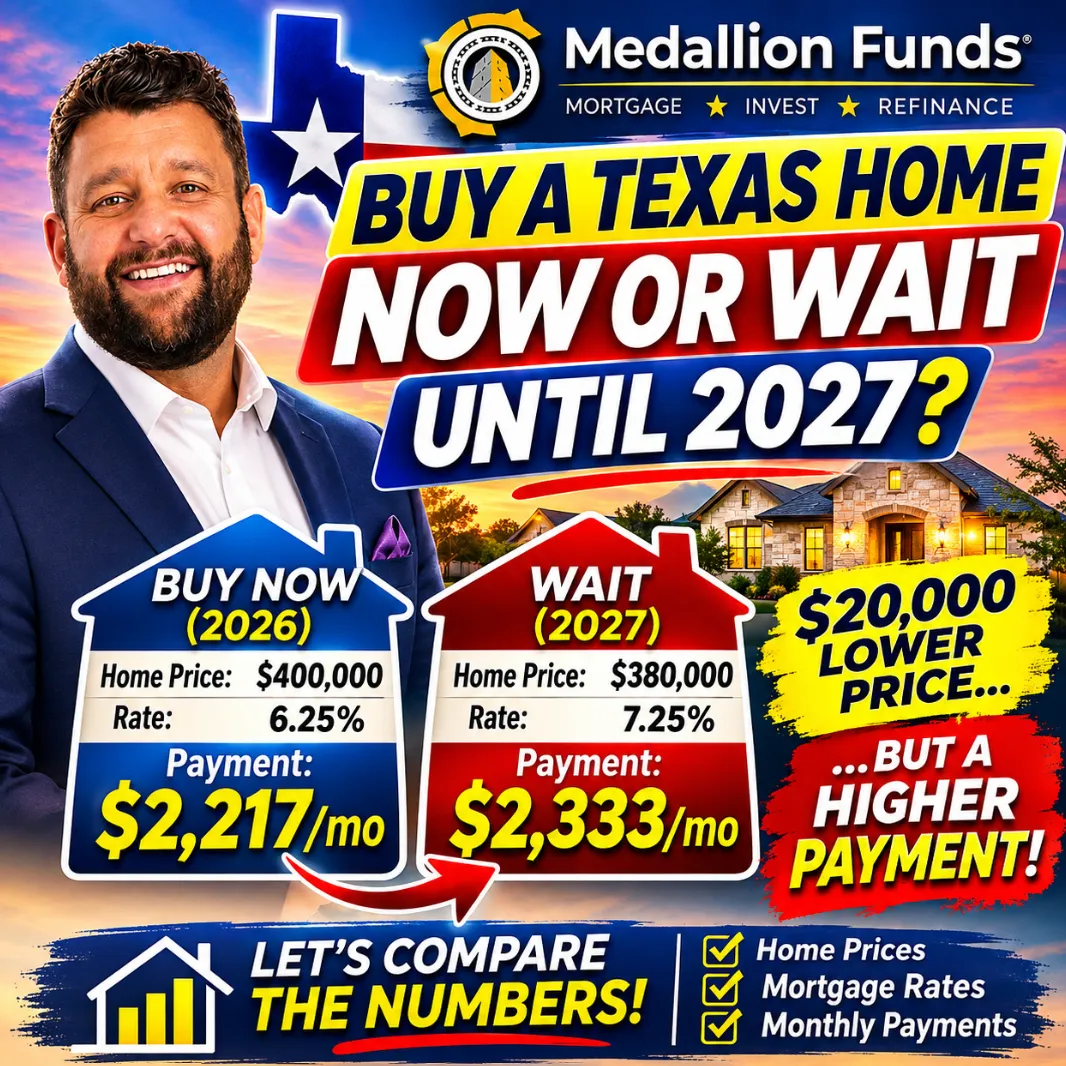
Scenario A: Buy a Texas Home in 2026
Assume you purchase a home with these terms:
·Purchase price: $400,000
·Down payment: 10%, or $40,000
·Mortgage amount: $360,000
·Interest rate: 6.25%
·Loan term: 30-year fixed
Your estimated monthly principal and interest payment would be approximately $2,217.
Scenario B: Wait Until 2027
Now imagine home prices decline by 5%, but mortgage rates increase to 7.25%.
·Purchase price: $380,000
·Down payment: 10%, or $38,000
·Mortgage amount: $342,000
·Interest rate: 7.25%
·Loan term: 30-year fixed
Your estimated monthly principal and interest payment would be approximately $2,333.
Despite paying $20,000 less for the property, you would have a monthly principal and interest payment approximately $116 higher.
That's roughly $1,392 more per year.
These are illustrative scenarios, not predictions or current rate quotes. Actual payments depend on the loan terms, borrower qualifications, and applicable financing costs.
Why Mortgage Rates Matter More Than Many Buyers Realize
When shopping for a home, buyers naturally focus on the purchase price.
But mortgage rates influence how much that home costs to finance.
A higher rate can offset the benefit of a lower purchase price, especially when financing most of the purchase.
Conversely, lower mortgage rates can sometimes improve affordability even when home prices remain unchanged.
The important distinction is between purchase price, monthly payment, and total cost of ownership.
All three matter.
A lower price can reduce the down payment and potentially the property tax assessment over time. But a higher mortgage rate can increase financing expenses substantially.
That is why buyers should compare complete financing scenarios instead of making decisions based on headlines.
What If Texas Home Prices and Mortgage Rates Both Fall?
This would generally be a favorable scenario for buyers.
For example, imagine that a $400,000 home declines to $380,000 while mortgage rates decrease from 6.25% to 5.75%.
With 10% down, the new mortgage amount would be $342,000.
The estimated monthly principal and interest payment would decline to approximately $1,996.
That represents a reduction of roughly $221 per month compared with the original $400,000 purchase scenario.
However, there is another consideration.
If lower mortgage rates attract more buyers into the market, competition could increase.
More competition may lead to fewer seller concessions, shorter negotiation windows, and upward pressure on prices in desirable neighborhoods.
Waiting can create opportunities, but it also introduces uncertainty.
Texas Property Taxes and Insurance: The Hidden Affordability Factors
In Texas, the mortgage payment is only part of the homeownership equation.
Buyers must also evaluate:
·Property taxes and applicable exemptions
·Homeowners insurance premiums
·Flood insurance where appropriate or required
·Mortgage insurance, if applicable
·HOA fees
·Maintenance and repair expenses
For example, a $400,000 property with an illustrative effective property tax rate of 2% would generate approximately $8,000 in annual property taxes before considering exemptions or other adjustments.
That is approximately $667 per month.
Property tax rates, taxable values, exemptions, and special assessments vary significantly by location.
Insurance costs can also vary based on property characteristics, roof condition, claims history, and weather exposure.
In areas such as Katy, Fulshear, Richmond, and West Houston, buyers should evaluate the property's specific tax districts, potential MUD assessments, and insurance requirements before making an offer.
The best mortgage decision considers the complete monthly housing expense—not just principal and interest.
Should Move-Up Buyers Wait Until 2027?
Move-up buyers face an additional challenge.
They are not simply purchasing a new home. They may also be selling an existing property and replacing an older mortgage with a new one.
Suppose you purchased your current home several years ago with a 3% mortgage rate.
Selling that property and purchasing a larger home with a higher-rate mortgage could substantially increase your monthly payment.
But mortgage rates are not the only factor.
You may need additional bedrooms, a better location, more space for your family, or a home that better accommodates your lifestyle.
Before deciding to move, evaluate:
Your existing equity: How much money will remain after paying off your mortgage and selling expenses?
Your replacement mortgage: What would the new monthly payment look like after applying your available equity?
Your current interest rate: How much additional financing expense would you incur by replacing your existing mortgage?
Your timeline: Is the move optional, or does your household need different housing now?
For some homeowners, waiting makes financial sense.
For others, the lifestyle benefits and availability of a suitable property may justify moving sooner.
Can You Buy Now and Refinance Later?
Potentially, but refinancing should never be treated as guaranteed.
If mortgage rates decline after purchasing, homeowners may have an opportunity to refinance into a lower rate.
However, refinancing depends on several factors:
·Future mortgage rates
·Credit and income qualifications
·Property value and available equity
·Closing costs
·Loan program requirements
A refinance can also restart or extend the repayment period, which may increase total interest costs even when the monthly payment falls.
Buy based on a payment you can comfortably afford today—not one that requires a future refinance to work.
Mortgage Strategies That Could Help Texas Homebuyers
At Medallion Funds, we help buyers evaluate mortgage options based on their financial circumstances.
Depending on eligibility and program availability, those options may include:
Conventional mortgages: Financing options for qualified borrowers, including certain low-down-payment programs.
FHA loans: Government-insured mortgages with flexible qualifying criteria for eligible buyers.
VA loans: Valuable financing options for eligible veterans, active-duty service members, and certain surviving spouses.
Doctor and dentist loans: Specialized programs that may offer flexible down payment or student loan treatment for qualifying medical professionals.
Jumbo mortgages: Financing for higher-priced homes that exceed applicable conforming loan limits.
Bank statement loans: Alternative income documentation programs that may benefit qualified self-employed borrowers.
Seller concessions and temporary rate buydowns: Negotiated structures that may help eligible buyers manage upfront costs or initial payments, subject to program restrictions.
The right financing structure can sometimes have a greater impact on your purchasing decision than attempting to predict the market.
Five Questions to Ask Before Buying a Texas Home
Before deciding whether to buy now or wait until 2027, ask yourself:
1.Can I comfortably afford the complete monthly payment today?
2.Do I have sufficient cash for my down payment, closing costs, and emergency reserves?
3.How long do I realistically expect to own this home?
4.What happens to my budget if insurance, taxes, or maintenance costs increase?
5.Am I buying because the property fits my needs, or because I am trying to time the market?
These questions help separate a sound financial decision from speculation about future prices and rates.
Final Verdict: Buy Now or Wait Until 2027?
There is no universal answer.
Buying now may make sense if you find the right property, have stable income, can comfortably afford the payment, and expect to remain in the home long enough to justify the transaction costs.
Waiting may make sense if you need to improve your credit, build additional savings, reduce debt, or gain greater financial stability.
The biggest mistake is assuming that falling home prices will automatically make homes more affordable.
A cheaper home with a higher mortgage rate can cost more every month.
Instead of trying to predict the perfect time to buy, focus on the purchase price, financing structure, complete housing expense, and long-term ownership strategy.
Ready to Compare Your Mortgage Options?
I'm Bill Rapp, CCIM, Capital Advisor with Medallion Funds.
Whether you're buying your first Texas home, relocating, or considering a move-up purchase, I can help you evaluate financing options and compare realistic monthly payment scenarios.
Bill Rapp
Partner & Director of Capital Advisory | Medallion Funds
Commercial Lending Nationwide
Residential Lending in AL, CA, CO, NV & TXBottom of Form
📞 Call or Text: 281-222-0433
🌐 Website: https://billrapponline.com
🎥 Subscribe to Mortgage Viking: https://www.youtube.com/@billrapp-medallion-funds
https://www.billrapponline.com/
https://findamortgagebroker.com/Profile/WilliamRappJr28883
https://billrapp.commloan.com/
https://billrapponline.com/financingfuturescre-houston-katy
https://houstoncommercialmortgage.com/
https://author.billrapponline.com
https://doctorvideo.billrapponline.com/
https://veteransvideo.billrapponline.com/
https://mortgageviking.billrapponline.com/
https://fha203h.billrapponline.com/
https://renovationvideo.billrapponline.com
https://medallionfunds.com/bill-rapp/
https://www.amazon.com/dp/B0F32Z5BH2
https://veed.cello.so/FOmzTty6oi9
https://buymeacoffee.com/vikingente3
https://creplaybookseries.billrapponline.com
https://creplaybook.billrapponline.com/
© Bill Rapp, Medallion Funds LLC, Director of Capital Advisory
10 Tips for First-Time Homebuyers
Buying your first home can be both exciting and nerve-wracking at the same time. With so many things to consider and....
How To Choose the Right Lender for You
Lorem Ipsum is simply dummy text of the printing and typesetting industry. Lorem Ipsum has been the industry's standard dummy
Refinancing youe loan and when to do it
Lorem Ipsum is simply dummy text of the printing and typesetting industry. Lorem Ipsum has been the industry's standard dummy
🧮 Renovation ROI Calculator
🛠️ Renovation ROI Calculator 💰
Copyright ©2021 | Mortgage Viking Team
Licensed to Do Business | NMLS # 228246
This is not an offer to enter into an agreement. Not all customers will qualify. Information, rates and programs are subject to change without notice. All products are subject to credit and property approval. Other restrictions and limitations may apply. Copyright © 2021 | Medallion Funds
Corporate | NMLS ID NMLS # 1825831
Corporate Address : 2651 N. Green Valley Pkwy STE. 101 Henderson, NV 89014
Corporate NMLS NMLS # 1825831 | Company Website: https://medallionfunds.com/bill-rapp/
Copyright ©2021 | Mortgage Viking Team Licensed to Do Business | NMLS # 228246
This is not an offer to enter into an agreement. Not all customers will qualify. Information, rates and programs are subject to change without notice. All products are subject to credit and property approval. Other restrictions and limitations may apply
Corporate | NMLS ID NMLS # 1825831
Corporate Address : 2651 N. Green Valley Pkwy STE. 101 Henderson, NV 89014 https://medallionfunds.com/bill-rapp/