The Top 5 Mortgage Mistakes to Avoid
Buying a home can be an exciting and rewarding experience, but it can also be a daunting and overwhelming process, especially for first-time homebuyers.
.
Mortgages are a significant financial commitment, and making mistakes during the process can have serious consequences. In this blog post, we'll explore the top 5 mortgage mistakes to avoid.
1. Failing to Check and Improve Your
Credit Score
Your credit score plays a significant role in determining your eligibility for a mortgage and the interest rate you'll receive. Many first-time homebuyers make the mistake of failing to check their credit score or not taking steps to improve it before applying for a mortgage.
,
To avoid this mistake, check your credit score and take steps to improve it if necessary. This may include paying off outstanding debts, making on-time payments, and disputing any errors on your credit report. A higher credit score can lead to a lower interest rate and a more favorable mortgage offer.
2. Ignoring
Closing Costs
Another common mistake is ignoring closing costs. Many first-time homebuyers are unaware of the various fees associated with closing a mortgage, such as attorney fees, title search fees, and appraisal fees. These costs can add up quickly and significantly impact the total cost of the mortgage.
.
To avoid this mistake, research the average closing costs in your area and budget accordingly. Be sure to factor in these costs when considering the overall cost of the home.
2. Ignoring Closing Costs
Another common mistake is ignoring closing costs. Many first-time homebuyers are unaware of the various fees associated with closing a mortgage, such as attorney fees, title search fees, and appraisal fees. These costs can add up quickly and significantly impact the total cost of the mortgage.
.
To avoid this mistake, research the average closing costs in your area and budget accordingly. Be sure to factor in these costs when considering the overall cost of the home.
3. Not Getting Pre-Approved
Getting pre-approved for a mortgage is an essential step in the home buying process. Pre-approval gives you a clear idea of how much you can afford to spend on a home and helps you avoid the disappointment of falling in love with a home you can't afford.
.
To avoid this mistake, get pre-approved for a mortgage before you start shopping for a home. This will help you narrow down your search to homes that are within your budget and prevent you from wasting time on homes that are out of reach.
4. Taking on Too Much Debt
Taking on too much debt before or during the mortgage process can have serious consequences. Lenders look at your debt-to-income ratio when determining your eligibility for a mortgage. If you have too much debt, you may not qualify for a mortgage or may be offered a higher interest rate.
.
To avoid this mistake, avoid taking on new debt before or during the mortgage process. This includes opening new credit cards, taking out a car loan, or making large purchases on existing credit cards.
4. Taking on Too
Much Debt
Taking on too much debt before or during the mortgage process can have serious consequences. Lenders look at your debt-to-income ratio when determining your eligibility for a mortgage. If you have too much debt, you may not qualify for a mortgage or may be offered a higher interest rate.
.
To avoid this mistake, avoid taking on new debt before or during the mortgage process. This includes opening new credit cards, taking out a car loan, or making large purchases on existing credit cards.
5. Choosing the Wrong Mortgage
Choosing the wrong mortgage can be a costly mistake. There are various types of mortgages available, and each has its pros and cons. Choosing the wrong mortgage can lead to higher interest rates, higher monthly payments, and a more significant financial burden in the long run.
.
To avoid this mistake, research the different types of mortgages available and choose the one that best fits your financial situation and goals. Don't be afraid to ask your lender questions and seek advice from a financial advisor.
Blogs
The Top 5 Mortgage Mistakes to Avoid
Buying your first home can be both exciting and nerve-wracking at the same time. With so many things to consider and....
Mortgage Do and
Do not list
Mortgages can be tricky, and it's easy to make mistakes that can end up costing you dearly. That's why we've put together this list....
Tips On How To Improve Your Credit Score
Let's talk about some ways you can improve your credit score! Your credit score is actually a big deal, and it can affect...
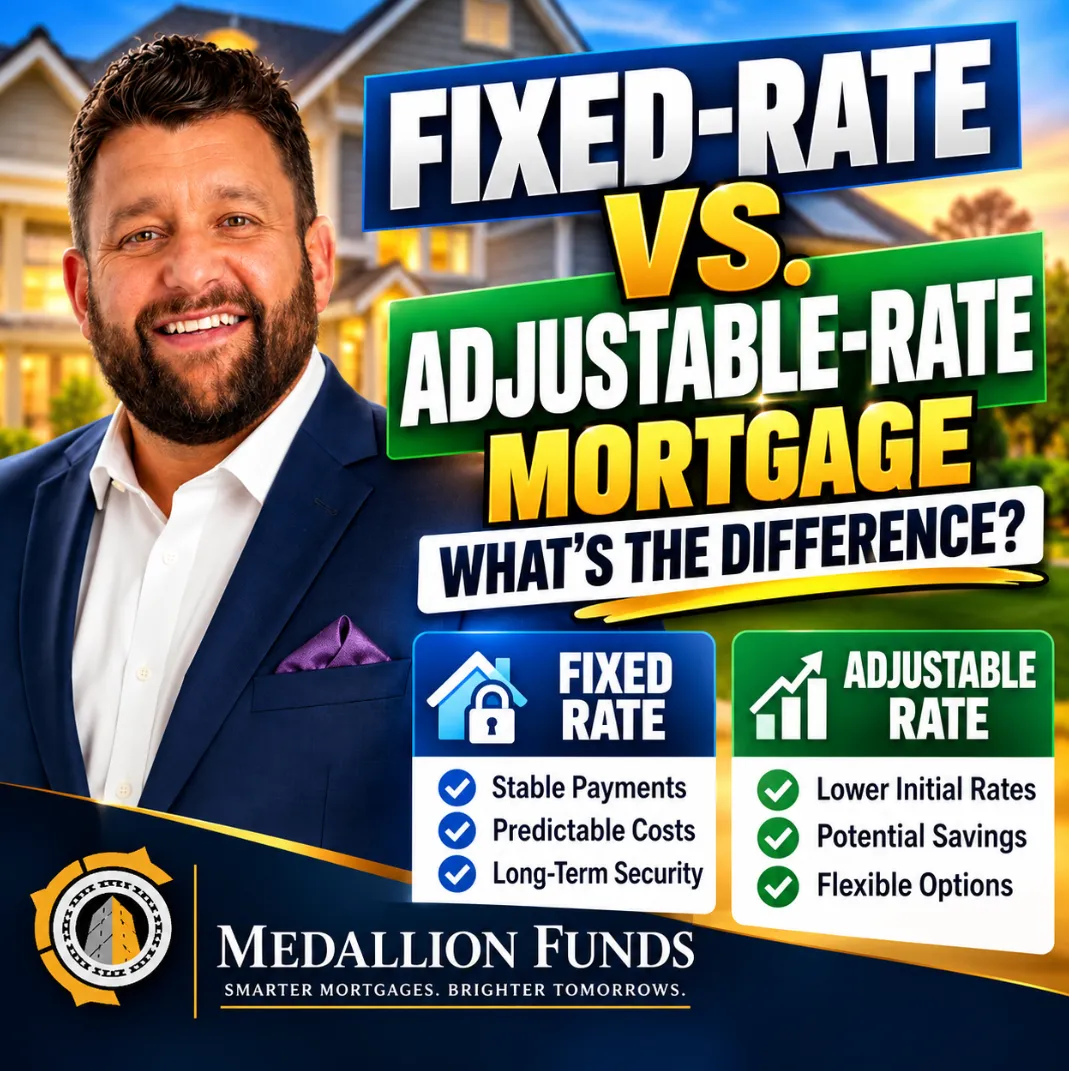
🏡 Fixed-Rate vs. Adjustable-Rate Mortgage: Which Home Loan Saves You More Money? 💰
🏡 Fixed-Rate vs. Adjustable-Rate Mortgage: Which Home Loan Saves You More Money? 💰
💵 Fixed vs. Adjustable Mortgage Rates: 7 Things Every Homebuyer Should Know Before Choosing 🏠
____________________________________________________________________________
Fixed-Rate vs. Adjustable-Rate Mortgage: Which Home Loan Saves You More Money?
When you're shopping for a mortgage, one of the most important decisions you'll make is whether to choose a fixed-rate mortgage or an adjustable-rate mortgage (ARM).
Both options can help you purchase a home, but they work differently. One offers predictable monthly principal and interest payments, while the other may offer a lower introductory interest rate in exchange for uncertainty later.
So which mortgage is better for you?
The answer depends on your financial goals, how long you expect to own the home, your budget, and your tolerance for changing interest rates.
At Medallion Funds, we help homebuyers understand their financing options so they can make informed decisions rather than simply choosing the loan with the lowest advertised rate.
Let's break down the differences.
What Is a Fixed-Rate Mortgage?
A fixed-rate mortgage is a home loan with an interest rate that remains unchanged throughout the entire loan term.
Whether you choose a 15-year, 20-year, or 30-year fixed-rate mortgage, your interest rate stays the same unless you refinance or otherwise modify the loan.
Advantages of a Fixed-Rate Mortgage
·Predictable payments: Your monthly principal and interest payment stays the same.
·Protection against rising interest rates: Market rate increases won't change your existing mortgage rate.
·Easier long-term budgeting: You know the scheduled principal and interest payment for the life of the loan.
·Long-term stability: Particularly attractive for homeowners planning to remain in their homes for many years.
Disadvantages of a Fixed-Rate Mortgage
·The initial interest rate may be higher than the introductory rate on an ARM.
·You may pay more interest during the early years compared with a lower-rate ARM.
·Taking advantage of falling market rates generally requires refinancing, which may involve closing costs and qualification requirements.
Important: Even with a fixed-rate mortgage, your total housing payment may change because of property taxes, homeowners insurance, mortgage insurance, or escrow adjustments.
What Is an Adjustable-Rate Mortgage?
An adjustable-rate mortgage, commonly called an ARM, generally begins with a fixed introductory interest rate for a specified period.
After that initial period, the interest rate can adjust periodically based on a financial index plus a lender-defined margin, subject to the loan's adjustment caps.
Common ARM structures include:
·5/1 ARM: Fixed interest rate for five years, then adjustments generally once per year.
·7/1 ARM: Fixed interest rate for seven years, then adjustments generally once per year.
·10/1 ARM: Fixed interest rate for ten years, then adjustments generally once per year.
·5/6 ARM: Fixed interest rate for five years, then adjustments generally every six months.
The first number represents the initial fixed-rate period in years. The second number indicates the adjustment frequency afterward.
For example, a 7/6 ARM generally maintains its introductory rate for seven years before becoming eligible for adjustments every six months.
Advantages of an Adjustable-Rate Mortgage
·Potentially lower introductory rates: Some ARMs offer lower initial interest rates than comparable fixed-rate loans.
·Potential early payment savings: A lower introductory rate can reduce monthly principal and interest payments.
·Flexibility for shorter ownership plans: May suit borrowers who expect to sell or relocate before the first adjustment.
·Potential benefit if rates decline: Future adjustments could reduce the interest rate, depending on the index, margin, and contractual limits.
Disadvantages of an Adjustable-Rate Mortgage
·Your interest rate and payment may increase after the introductory period.
·Future payment amounts are uncertain.
·Refinancing may not be available or financially attractive when you need it.
·Rising payments can create financial stress if your budget is already stretched.
Key takeaway: An ARM isn't automatically riskier for every borrower, but understanding its adjustment structure is essential.
Fixed-Rate vs. Adjustable-Rate Mortgage: Side-by-Side Comparison
Feature | Fixed-Rate Mortgage | Adjustable-Rate Mortgage |
Interest rate | Remains fixed | Fixed initially, then can adjust |
Initial rate | May be higher | May be lower |
Principal and interest payment | Predictable | Can change after initial period |
Rising-rate protection | Throughout loan term | Limited by fixed period and caps |
Long-term budgeting | Easier | More uncertainty |
Common borrower fit | Long-term homeowner | Borrower comfortable with adjustment risk |
Refinancing | Optional strategy | Optional, but not guaranteed |
Neither mortgage type is universally superior.
The best choice is the one that aligns with your expected ownership period, financial flexibility, and long-term goals.
Real-World Example: Fixed-Rate Mortgage vs. 7/6 ARM
Let's compare two hypothetical financing scenarios.
Home purchase price: $450,000
Down payment: $90,000 (20%)
Loan amount: $360,000
Amortization: 30 years
Assume the following illustrative interest rates:
Option A: 30-Year Fixed-Rate Mortgage
·Interest rate: 6.50%
·Monthly principal and interest: Approximately $2,275
·Interest rate stays at 6.50% for the loan term.
Option B: 7/6 Adjustable-Rate Mortgage
·Initial interest rate: 5.75%
·Initial monthly principal and interest: Approximately $2,101
·Rate remains fixed for the first seven years, then can adjust every six months.
Potential Initial Savings
The ARM would save approximately $174 per month in principal and interest during its introductory period.
Over seven years, that represents approximately $14,600 in cumulative payment differences, assuming scheduled payments and unchanged introductory terms.
However, those differences are not the same as total financial savings. The loans amortize differently, and the ARM's interest rate may increase or decrease after year seven.
These figures exclude property taxes, insurance, mortgage insurance, lender fees, points, and other closing costs. Rates are hypothetical, not current loan offers.
What Happens When an ARM Adjusts?
Once the introductory period ends, the ARM's interest rate may move up or down.
Most modern adjustable-rate mortgages use an index, such as the Secured Overnight Financing Rate (SOFR), plus a contractual margin.
For example:
·Index at adjustment: 4.00%
·Contractual margin: 2.75%
·Fully indexed rate: 6.75%
The actual adjusted rate is subject to the mortgage's contractual provisions and applicable caps or floors.
Understanding ARM Rate Caps
ARM rate caps limit how much the interest rate can increase.
A hypothetical 2/1/5 cap structure generally means:
·2% initial adjustment cap: Maximum increase at the first adjustment.
·1% subsequent adjustment cap: Maximum increase at later adjustments.
·5% lifetime adjustment cap: Maximum increase over the initial rate during the life of the loan.
Actual caps vary by product. Some loans also specify downward adjustment limits or interest-rate floors.
Before choosing an ARM, ask your mortgage broker to calculate your possible payment under the maximum permitted interest rate.
When Does a Fixed-Rate Mortgage Make Sense?
A fixed-rate mortgage may be particularly attractive if:
1.You expect to remain in your home for ten years or longer.
2.You prefer stable monthly principal and interest payments.
3.Your household budget has limited room for payment increases.
4.You want protection against future interest-rate increases.
5.You value certainty more than potential introductory savings.
For many first-time homebuyers, the predictability of a fixed-rate mortgage provides valuable peace of mind.
However, long-term stability should still be weighed against the loan's interest rate, fees, and total borrowing costs.
When Does an Adjustable-Rate Mortgage Make Sense?
An ARM may be worth considering when:
1.You expect to relocate within the introductory fixed-rate period.
2.You anticipate selling the property within several years.
3.The ARM provides meaningful initial savings after accounting for fees.
4.You have sufficient income, reserves, and financial flexibility to absorb potential payment increases.
5.You understand the adjustment index, margin, caps, and maximum payment exposure.
An ARM can also be attractive for some medical professionals, executives, or relocating homebuyers who anticipate changes in housing needs.
However, projected career advancement, future income increases, and anticipated refinancing should never be treated as guaranteed.
Should You Choose an ARM If You Expect Mortgage Rates to Fall?
This is one of the most common questions borrowers ask.
If mortgage rates decline, an ARM might eventually adjust downward.
But there are important limitations.
First, your ARM may not adjust until the introductory period expires.
Second, the adjustment depends on the loan's index and contractual provisions, not simply the prevailing advertised mortgage rate.
Third, interest rates could rise instead of fall.
A fixed-rate borrower can also explore refinancing when market rates decline, although refinancing involves new qualification requirements, costs, and potential changes to the loan term.
The better approach is to choose a mortgage you can afford even if your interest-rate forecast turns out to be wrong.
Seven Questions to Ask Before Choosing a Fixed or Adjustable Mortgage
Before making your decision, ask your mortgage broker:
1.What is the initial interest rate and APR for each option?
2.How much are the lender fees, discount points, and closing costs?
3.When can the ARM first adjust, and how frequently afterward?
4.What index, margin, rate caps, and floors apply?
5.What would my payment be at the maximum permitted interest rate?
6.How do the five-year costs and principal balances compare?
7.How does each loan fit my expected ownership period and financial reserves?
A properly prepared Loan Estimate can help you compare interest rates, closing costs, APR, and the projected five-year borrowing costs.
For an ARM, also review the required adjustable-rate disclosures.
Frequently Asked Questions
Is a fixed-rate mortgage better than an ARM?
Not necessarily. Fixed-rate loans offer long-term payment predictability, while ARMs may provide initial savings. The best option depends on your financial circumstances and ownership plans.
Can an adjustable-rate mortgage increase every month?
Not necessarily. Adjustment frequency is specified in the loan documents. For example, a 7/6 ARM generally adjusts no more frequently than every six months after the seven-year introductory period.
Can I refinance an ARM into a fixed-rate mortgage?
Yes, if you qualify for a new loan and refinancing is available. Approval depends on factors such as credit, income, property value, equity, and lender guidelines.
Do adjustable-rate mortgages always start with lower interest rates?
No. ARM pricing depends on market conditions, lender offerings, loan structure, and borrower qualifications. Compare actual offers rather than assuming an ARM is cheaper.
Can an ARM payment decrease?
Yes. If the relevant index declines, an ARM's interest rate and principal and interest payment may decrease, subject to the loan's terms and any applicable floors.
Is a 7/6 ARM better than a 30-year fixed mortgage?
A 7/6 ARM may provide introductory savings, but a fixed-rate loan provides greater long-term certainty. Compare both under realistic scenarios before deciding.
Final Thoughts: Choose the Mortgage That Fits Your Future
Choosing between a fixed-rate mortgage and an adjustable-rate mortgage isn't simply about finding the lowest interest rate today.
It's about understanding your future payment obligations, your financial flexibility, and your long-term homeownership plans.
At Medallion Funds, we help borrowers evaluate financing options, compare loan structures, and understand the potential trade-offs.
Whether you're buying your first home, relocating, purchasing a larger property, or exploring refinancing, the right mortgage strategy begins with the right information.
Let's review your mortgage options together.
Bill Rapp
Partner & Director of Capital Advisory | Medallion Funds
Commercial Lending Nationwide
Residential Lending in AL, CA, CO, NV & TXBottom of Form
https://www.billrapponline.com/
https://findamortgagebroker.com/Profile/WilliamRappJr28883
https://billrapp.commloan.com/
https://billrapponline.com/financingfuturescre-houston-katy
https://houstoncommercialmortgage.com/
https://author.billrapponline.com
https://doctorvideo.billrapponline.com/
https://veteransvideo.billrapponline.com/
https://mortgageviking.billrapponline.com/
https://fha203h.billrapponline.com/
https://renovationvideo.billrapponline.com
https://medallionfunds.com/bill-rapp/
https://www.amazon.com/dp/B0F32Z5BH2
https://veed.cello.so/FOmzTty6oi9
https://buymeacoffee.com/vikingente3
https://creplaybookseries.billrapponline.com
https://creplaybook.billrapponline.com/
© Bill Rapp, Medallion Funds LLC, Director of Capital Advisory
10 Tips for First-Time Homebuyers
Buying your first home can be both exciting and nerve-wracking at the same time. With so many things to consider and....
How To Choose the Right Lender for You
Lorem Ipsum is simply dummy text of the printing and typesetting industry. Lorem Ipsum has been the industry's standard dummy
Refinancing youe loan and when to do it
Lorem Ipsum is simply dummy text of the printing and typesetting industry. Lorem Ipsum has been the industry's standard dummy
🧮 Renovation ROI Calculator
🛠️ Renovation ROI Calculator 💰
Copyright ©2021 | Mortgage Viking Team
Licensed to Do Business | NMLS # 228246
This is not an offer to enter into an agreement. Not all customers will qualify. Information, rates and programs are subject to change without notice. All products are subject to credit and property approval. Other restrictions and limitations may apply. Copyright © 2021 | Medallion Funds
Corporate | NMLS ID NMLS # 1825831
Corporate Address : 2651 N. Green Valley Pkwy STE. 101 Henderson, NV 89014
Corporate NMLS NMLS # 1825831 | Company Website: https://medallionfunds.com/bill-rapp/
Copyright ©2021 | Mortgage Viking Team Licensed to Do Business | NMLS # 228246
This is not an offer to enter into an agreement. Not all customers will qualify. Information, rates and programs are subject to change without notice. All products are subject to credit and property approval. Other restrictions and limitations may apply
Corporate | NMLS ID NMLS # 1825831
Corporate Address : 2651 N. Green Valley Pkwy STE. 101 Henderson, NV 89014 https://medallionfunds.com/bill-rapp/