
The Top 5 Mortgage Mistakes to Avoid
Buying a home can be an exciting and rewarding experience, but it can also be a daunting and overwhelming process, especially for first-time homebuyers.
.
Mortgages are a significant financial commitment, and making mistakes during the process can have serious consequences. In this blog post, we'll explore the top 5 mortgage mistakes to avoid.
1. Failing to Check and Improve Your
Credit Score
Your credit score plays a significant role in determining your eligibility for a mortgage and the interest rate you'll receive. Many first-time homebuyers make the mistake of failing to check their credit score or not taking steps to improve it before applying for a mortgage.
,
To avoid this mistake, check your credit score and take steps to improve it if necessary. This may include paying off outstanding debts, making on-time payments, and disputing any errors on your credit report. A higher credit score can lead to a lower interest rate and a more favorable mortgage offer.
2. Ignoring
Closing Costs
Another common mistake is ignoring closing costs. Many first-time homebuyers are unaware of the various fees associated with closing a mortgage, such as attorney fees, title search fees, and appraisal fees. These costs can add up quickly and significantly impact the total cost of the mortgage.
.
To avoid this mistake, research the average closing costs in your area and budget accordingly. Be sure to factor in these costs when considering the overall cost of the home.
2. Ignoring Closing Costs
Another common mistake is ignoring closing costs. Many first-time homebuyers are unaware of the various fees associated with closing a mortgage, such as attorney fees, title search fees, and appraisal fees. These costs can add up quickly and significantly impact the total cost of the mortgage.
.
To avoid this mistake, research the average closing costs in your area and budget accordingly. Be sure to factor in these costs when considering the overall cost of the home.

3. Not Getting Pre-Approved
Getting pre-approved for a mortgage is an essential step in the home buying process. Pre-approval gives you a clear idea of how much you can afford to spend on a home and helps you avoid the disappointment of falling in love with a home you can't afford.
.
To avoid this mistake, get pre-approved for a mortgage before you start shopping for a home. This will help you narrow down your search to homes that are within your budget and prevent you from wasting time on homes that are out of reach.
4. Taking on Too Much Debt
Taking on too much debt before or during the mortgage process can have serious consequences. Lenders look at your debt-to-income ratio when determining your eligibility for a mortgage. If you have too much debt, you may not qualify for a mortgage or may be offered a higher interest rate.
.
To avoid this mistake, avoid taking on new debt before or during the mortgage process. This includes opening new credit cards, taking out a car loan, or making large purchases on existing credit cards.
4. Taking on Too
Much Debt
Taking on too much debt before or during the mortgage process can have serious consequences. Lenders look at your debt-to-income ratio when determining your eligibility for a mortgage. If you have too much debt, you may not qualify for a mortgage or may be offered a higher interest rate.
.
To avoid this mistake, avoid taking on new debt before or during the mortgage process. This includes opening new credit cards, taking out a car loan, or making large purchases on existing credit cards.
5. Choosing the Wrong Mortgage
Choosing the wrong mortgage can be a costly mistake. There are various types of mortgages available, and each has its pros and cons. Choosing the wrong mortgage can lead to higher interest rates, higher monthly payments, and a more significant financial burden in the long run.
.
To avoid this mistake, research the different types of mortgages available and choose the one that best fits your financial situation and goals. Don't be afraid to ask your lender questions and seek advice from a financial advisor.
Blogs
The Top 5 Mortgage Mistakes to Avoid
Buying your first home can be both exciting and nerve-wracking at the same time. With so many things to consider and....
Mortgage Do and
Do not list
Mortgages can be tricky, and it's easy to make mistakes that can end up costing you dearly. That's why we've put together this list....
Tips On How To Improve Your Credit Score
Let's talk about some ways you can improve your credit score! Your credit score is actually a big deal, and it can affect...
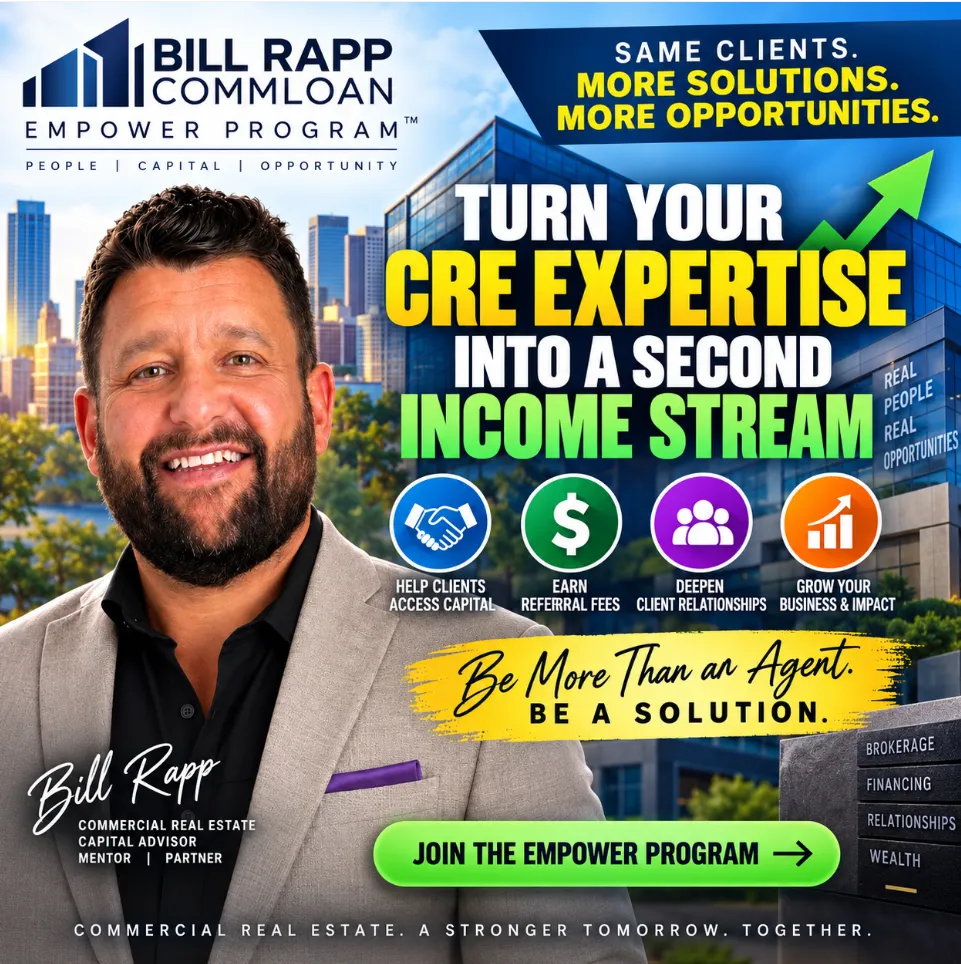
🏢 How Commercial Real Estate Agents Can Add Capital Advisory—and Build a Second Income Stream 💰
🏢 How Commercial Real Estate Agents Can Add Capital Advisory—and Build a Second Income Stream 💰
💵 Stop Leaving Money at the Closing Table: How CRE Agents Can Add Commercial Financing to Their Business 🚀
________________________________________________________________________________
How Commercial Real Estate Agents Can Add Capital Advisory and Create a Second Income Stream
Commercial real estate agents spend their careers helping clients identify opportunities, negotiate transactions, evaluate properties, and get deals to the closing table.
But there is another critical part of nearly every commercial real estate transaction that many agents hand off the moment the purchase contract is signed:
The financing.
That creates an interesting opportunity.
Instead of viewing commercial financing as something completely separate from brokerage, CRE agents can incorporate capital advisory into their client relationships—helping borrowers navigate financing while potentially developing an additional revenue stream.
The goal isn't necessarily to become a full-time commercial mortgage broker.
It's to become a more valuable commercial real estate advisor.
Your Client Already Asks You Financing Questions
Think about the conversations you already have with buyers.
"How much can I borrow?"
"What kind of down payment will I need?"
"Will a bank finance this property?"
"Should I use SBA financing?"
"What happens if the property doesn't meet the lender's DSCR requirement?"
"Can we finance the renovations?"
Those questions are already part of commercial real estate brokerage.
The problem is that many CRE agents have no structured process for answering them.
Instead, they provide the borrower with a few lender names and hope one of those lenders can get the transaction done.
Capital advisory offers another approach.
What Is Capital Advisory in Commercial Real Estate?
Commercial real estate capital advisory is the process of helping borrowers evaluate, structure, and source financing for a transaction.
Depending on the property and borrower, potential capital sources could include:
·Banks and credit unions
·SBA lenders
·CMBS lenders
·Agency multifamily lenders
·Bridge lenders
·Private lenders
·Debt funds
·DSCR lenders
·Construction lenders
·Owner-user commercial lenders
The important point is that different deals require different capital sources.
A bank that loves stabilized industrial properties may have no appetite for transitional multifamily.
A credit union may aggressively finance an owner-user office building but have little interest in a large investment property.
An SBA lender might finance a business acquisition and owner-occupied real estate transaction that doesn't fit conventional bank underwriting.
Capital advisory starts with understanding the transaction before deciding where the transaction should be financed.
Why CRE Agents Are Naturally Positioned for Capital Advisory
Commercial real estate agents already possess many of the skills necessary to participate in the financing conversation.
You understand properties.
You understand purchase contracts.
You work with investors.
You analyze NOI, cap rates, occupancy, lease structures, market rents, and operating expenses.
You also know something lenders care deeply about:
the story behind the transaction.
The missing component for many agents isn't the client relationship.
It's the commercial lending infrastructure behind them.
That's where a platform such as CommLoan can become valuable.
Rather than attempting to independently build hundreds of lender relationships, underwriting processes, technology, processing systems, and commercial lending expertise, an agent can work within an established commercial financing ecosystem.
Capital Advisory Can Create a Second Income Stream
Consider the economics of a typical brokerage transaction.
Traditionally, an agent participates in the real estate commission.
The financing goes somewhere else.
But the same client may need financing for:
Acquisitions → Refinances → Cash-out transactions → Construction → Renovations → Future acquisitions
That means the financing relationship can continue long after the original brokerage transaction closes.
Capital advisory therefore creates the possibility of an additional revenue channel from relationships the CRE agent is already developing.
More importantly, the financing conversation can produce future brokerage opportunities.
A financing client today could become an acquisition client tomorrow.
A refinance client could eventually become a seller.
An owner-user financing a building could later need expansion space.
The relationship becomes broader than one transaction.
Brokerage + Capital Advisory Creates a Stronger Client Relationship
The traditional brokerage model can be highly transactional.
Find the property.
Negotiate the deal.
Close the transaction.
Get paid.
Start looking for the next transaction.
Capital advisory provides another opportunity to remain connected to the client throughout the ownership lifecycle.
Imagine being able to discuss:
Property → Financing → Acquisition → Ownership → Refinance → Expansion → Disposition
Instead of participating in one part of the transaction, you're positioned to help the client navigate several stages of their commercial real estate strategy.
That can create a significantly deeper advisory relationship.
Financing Can Also Help CRE Agents Protect Their Brokerage Pipeline
There is another reason agents should understand commercial financing:
Bad financing can kill good brokerage deals.
Suppose you spend six months helping an investor identify a property.
You negotiate the purchase price.
The contract gets executed.
Due diligence begins.
Then the lender says the property's NOI doesn't support the requested loan amount.
Suddenly the buyer needs another $300,000 at closing.
The transaction may collapse.
A basic financing analysis earlier in the process might have identified the problem before the buyer ever submitted the offer.
That's why financing shouldn't always begin after the purchase contract.
Ideally, financing analysis begins while the buyer is evaluating the opportunity.
Underwrite the Financing Before Writing the Offer
Sophisticated CRE agents increasingly need to understand several lending metrics.
These include:
Loan-to-Value (LTV) – How much of the property's value will the lender finance?
Debt Service Coverage Ratio (DSCR) – Does the property's NOI sufficiently cover the proposed debt payments?
Debt Yield – How much NOI does the lender receive relative to the loan amount?
Liquidity – Does the borrower have sufficient post-closing liquidity?
Net Worth – Does the sponsor have the financial strength required for the transaction?
Sponsor Experience – Does the borrower have experience owning or operating this asset class?
Understanding these metrics allows an agent to identify potential financing problems much earlier.
And that can make the agent far more valuable to both buyers and sellers.
You Don't Need to Build a Commercial Lending Company From Scratch
This is where the CommLoan Empower Program becomes relevant.
The concept is straightforward:
Keep your commercial real estate business—and add commercial lending capabilities alongside it.
Instead of abandoning brokerage to become a lender, CRE professionals can develop capital advisory capabilities supported by lending technology, underwriting resources, lender relationships, processing infrastructure, and commercial finance expertise.
That dramatically shortens the learning curve.
The objective isn't simply to teach someone how to quote an interest rate.
It's to help commercial real estate professionals understand how lenders evaluate transactions and how to identify appropriate capital sources.
The Competitive Advantage: Same Client, More Solutions
Commercial real estate is a relationship business.
The professional who can solve more problems often becomes more valuable to the client.
A CRE agent who can only discuss property has one tool.
A CRE agent who understands:
Property + underwriting + financing + capital structure
can participate in a much broader conversation.
That doesn't mean pretending to know every answer.
It means having the systems, technology, lender access, and support necessary to find the answer.
Stop Giving Away the Financing Relationship
Every time a client asks:
"Who should I call for the loan?"
there is an opportunity.
You can simply hand them a lender's business card.
Or you can become part of the financing solution.
Commercial real estate agents already have one of the hardest parts of the lending business:
relationships with commercial real estate borrowers.
Adding capital advisory can allow those agents to deepen those relationships, protect brokerage transactions, create another potential income stream, and build a more diversified commercial real estate business.
The future of CRE brokerage may not simply be about selling more properties.
It may be about providing more solutions to the same clients.
Same clients. More solutions. More opportunities.
If you're a commercial real estate professional interested in adding commercial financing capabilities to your existing business, learn more about the Bill Rapp – CommLoan Empower Program.
Bill Rapp, CCIM
Director | CommLoan
📞 281-222-0433
📧 [email protected]
🌐 https://billrapp.commloan.com/
🌐 https://HoustonCommercialMortgage.com/
Commercial Real Estate Financing Nationwide
https://billrapp.commloan.com/
https://author.billrapponline.com/
https://www.amazon.com/dp/B0F32Z5BH2
https://veed.cello.so/FOmzTty6oi9
https://buymeacoffee.com/vikingente3
https://creplaybookseries.billrapponline.com
https://creplaybook.billrapponline.com/
©Bill Rapp, CCIM - Director - CommLoan
10 Tips for First-Time Homebuyers
Buying your first home can be both exciting and nerve-wracking at the same time. With so many things to consider and....
How To Choose the Right Lender for You
Lorem Ipsum is simply dummy text of the printing and typesetting industry. Lorem Ipsum has been the industry's standard dummy
Refinancing youe loan and when to do it
Lorem Ipsum is simply dummy text of the printing and typesetting industry. Lorem Ipsum has been the industry's standard dummy
🧮 Renovation ROI Calculator
🛠️ Renovation ROI Calculator 💰
Copyright ©2021 | Mortgage Viking Team
Licensed to Do Business | NMLS # 228246
This is not an offer to enter into an agreement. Not all customers will qualify. Information, rates and programs are subject to change without notice. All products are subject to credit and property approval. Other restrictions and limitations may apply. Copyright © 2021 | Medallion Funds
Corporate | NMLS ID NMLS # 1825831
Corporate Address : 2651 N. Green Valley Pkwy STE. 101 Henderson, NV 89014
Corporate NMLS NMLS # 1825831 | Company Website: https://medallionfunds.com/bill-rapp/
Copyright ©2021 | Mortgage Viking Team Licensed to Do Business | NMLS # 228246
This is not an offer to enter into an agreement. Not all customers will qualify. Information, rates and programs are subject to change without notice. All products are subject to credit and property approval. Other restrictions and limitations may apply
Corporate | NMLS ID NMLS # 1825831
Corporate Address : 2651 N. Green Valley Pkwy STE. 101 Henderson, NV 89014 https://medallionfunds.com/bill-rapp/