
The Top 5 Mortgage Mistakes to Avoid
Buying a home can be an exciting and rewarding experience, but it can also be a daunting and overwhelming process, especially for first-time homebuyers.
.
Mortgages are a significant financial commitment, and making mistakes during the process can have serious consequences. In this blog post, we'll explore the top 5 mortgage mistakes to avoid.
1. Failing to Check and Improve Your
Credit Score
Your credit score plays a significant role in determining your eligibility for a mortgage and the interest rate you'll receive. Many first-time homebuyers make the mistake of failing to check their credit score or not taking steps to improve it before applying for a mortgage.
,
To avoid this mistake, check your credit score and take steps to improve it if necessary. This may include paying off outstanding debts, making on-time payments, and disputing any errors on your credit report. A higher credit score can lead to a lower interest rate and a more favorable mortgage offer.
2. Ignoring
Closing Costs
Another common mistake is ignoring closing costs. Many first-time homebuyers are unaware of the various fees associated with closing a mortgage, such as attorney fees, title search fees, and appraisal fees. These costs can add up quickly and significantly impact the total cost of the mortgage.
.
To avoid this mistake, research the average closing costs in your area and budget accordingly. Be sure to factor in these costs when considering the overall cost of the home.
2. Ignoring Closing Costs
Another common mistake is ignoring closing costs. Many first-time homebuyers are unaware of the various fees associated with closing a mortgage, such as attorney fees, title search fees, and appraisal fees. These costs can add up quickly and significantly impact the total cost of the mortgage.
.
To avoid this mistake, research the average closing costs in your area and budget accordingly. Be sure to factor in these costs when considering the overall cost of the home.

3. Not Getting Pre-Approved
Getting pre-approved for a mortgage is an essential step in the home buying process. Pre-approval gives you a clear idea of how much you can afford to spend on a home and helps you avoid the disappointment of falling in love with a home you can't afford.
.
To avoid this mistake, get pre-approved for a mortgage before you start shopping for a home. This will help you narrow down your search to homes that are within your budget and prevent you from wasting time on homes that are out of reach.
4. Taking on Too Much Debt
Taking on too much debt before or during the mortgage process can have serious consequences. Lenders look at your debt-to-income ratio when determining your eligibility for a mortgage. If you have too much debt, you may not qualify for a mortgage or may be offered a higher interest rate.
.
To avoid this mistake, avoid taking on new debt before or during the mortgage process. This includes opening new credit cards, taking out a car loan, or making large purchases on existing credit cards.
4. Taking on Too
Much Debt
Taking on too much debt before or during the mortgage process can have serious consequences. Lenders look at your debt-to-income ratio when determining your eligibility for a mortgage. If you have too much debt, you may not qualify for a mortgage or may be offered a higher interest rate.
.
To avoid this mistake, avoid taking on new debt before or during the mortgage process. This includes opening new credit cards, taking out a car loan, or making large purchases on existing credit cards.
5. Choosing the Wrong Mortgage
Choosing the wrong mortgage can be a costly mistake. There are various types of mortgages available, and each has its pros and cons. Choosing the wrong mortgage can lead to higher interest rates, higher monthly payments, and a more significant financial burden in the long run.
.
To avoid this mistake, research the different types of mortgages available and choose the one that best fits your financial situation and goals. Don't be afraid to ask your lender questions and seek advice from a financial advisor.
Blogs
The Top 5 Mortgage Mistakes to Avoid
Buying your first home can be both exciting and nerve-wracking at the same time. With so many things to consider and....
Mortgage Do and
Do not list
Mortgages can be tricky, and it's easy to make mistakes that can end up costing you dearly. That's why we've put together this list....
Tips On How To Improve Your Credit Score
Let's talk about some ways you can improve your credit score! Your credit score is actually a big deal, and it can affect...
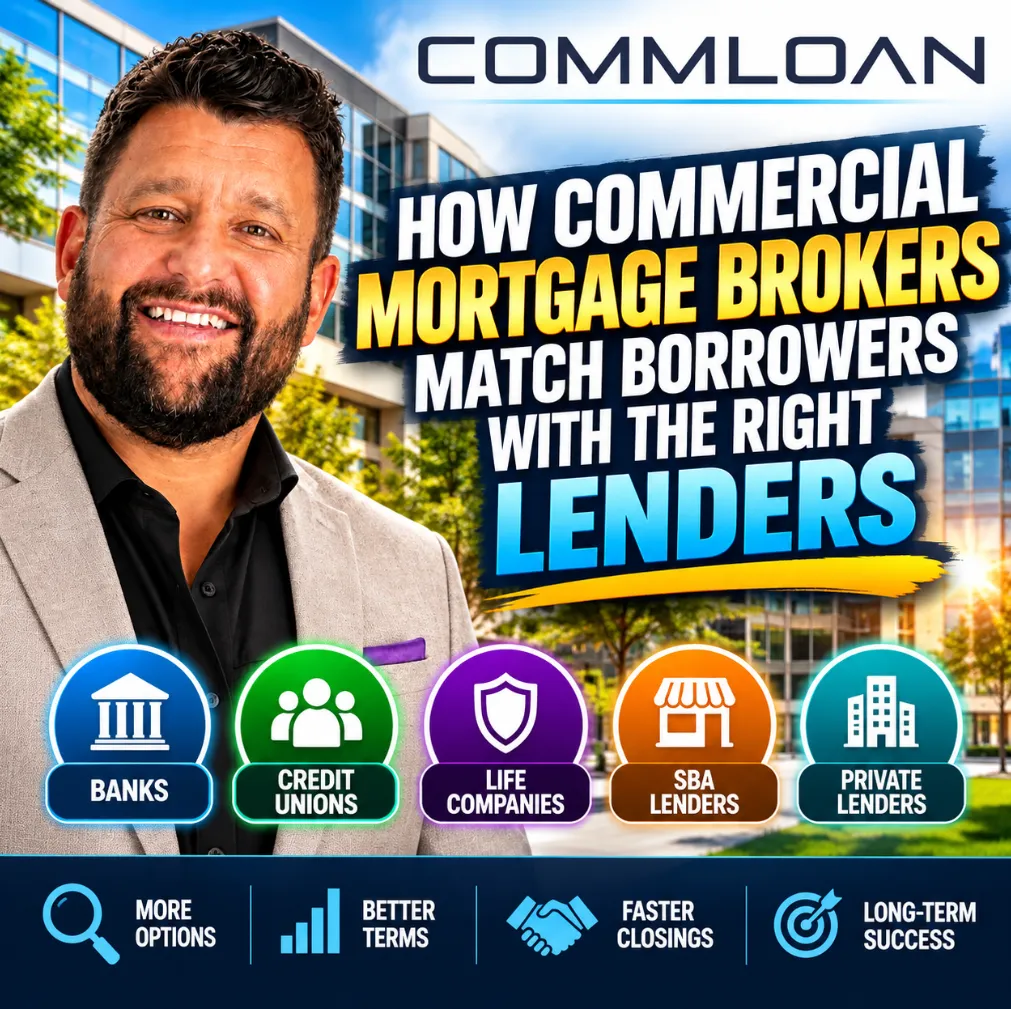
🏦 How Commercial Mortgage Brokers Match Borrowers With the Right Lenders 🔑
🏦 How Commercial Mortgage Brokers Match Borrowers With the Right Lenders 🔑
💰 Find the Right Commercial Real Estate Lender: Why Working With a Mortgage Broker Matters 🏢
________________________________________________________________________________
How Commercial Mortgage Brokers Match Borrowers With the Right Lenders
The right commercial real estate loan isn't always the one with the lowest interest rate. It's the one that fits your property, financial position, investment strategy, and long-term objectives.
Whether you're purchasing an apartment building, refinancing an office property, financing a hotel, or acquiring real estate for your business, finding the right lender can make the difference between a successful closing and a financing disappointment.
Commercial mortgage brokers help bridge the gap between borrowers and lenders by evaluating financing requirements, analyzing the transaction, and identifying lending sources whose programs align with the deal.
I'm Bill Rapp with the CommLoan Empower Program, and here's how that process works.
Why Finding the Right Commercial Mortgage Lender Matters
Commercial real estate financing is not a one-size-fits-all business.
Different lenders have different appetites for property types, geographic markets, loan amounts, borrower profiles, and risk.
For example:
·A community bank may prefer stabilized, owner-occupied commercial properties within its lending footprint.
·A life insurance company may favor larger, stabilized investments with predictable income.
·A private lender may consider transitional properties requiring renovations or lease-up.
·An SBA lender may offer financing options for eligible owner-occupied business properties.
·An agency lender may specialize in qualifying multifamily housing transactions.
A commercial mortgage broker's job is to understand these differences and help position your financing request with lenders that are more likely to consider it.
Step 1: Understanding the Borrower's Financial Goals
Before approaching lenders, an experienced commercial mortgage broker begins by asking questions.
What are you trying to accomplish?
Are you purchasing, refinancing, constructing, renovating, or extracting equity from a property?
Are you looking for maximum loan proceeds, lower monthly payments, a longer fixed-rate period, or greater flexibility?
Other important questions include:
·How much equity or down payment is available?
·How long do you intend to hold the property?
·Is the property stabilized or undergoing a transition?
·What is your experience with similar investments?
·How important is nonrecourse financing?
·Do you anticipate selling or refinancing before maturity?
These answers establish the framework for the financing strategy.
A loan that works for a long-term apartment investor may be completely inappropriate for a developer planning to sell within 18 months.
Step 2: Analyzing the Property and Its Cash Flow
Commercial real estate lenders evaluate more than the borrower's credit score.
They also evaluate the property and its ability to support the proposed debt.
Three common underwriting metrics are particularly important.
Loan-to-Value Ratio (LTV)
LTV measures the loan amount relative to the property's value.
Formula:
LTV = Loan Amount ÷ Property Value
For example, a $1.5 million loan against a $2 million property represents 75% LTV.
Lenders establish different maximum LTV requirements depending on the asset, transaction, and risk profile.
Debt Service Coverage Ratio (DSCR)
DSCR measures how effectively the property's net operating income supports its debt payments.
Formula:
DSCR = Net Operating Income ÷ Annual Debt Service
For example, if a property generates $150,000 in annual NOI and requires $120,000 in annual debt service, the DSCR is 1.25x.
That means the property generates $1.25 in NOI for every $1 of required annual debt service.
Debt Yield
Debt yield measures a property's NOI relative to the proposed loan amount.
Formula:
Debt Yield = Net Operating Income ÷ Loan Amount
If a property produces $150,000 in NOI and the proposed loan is $1.5 million, the debt yield is 10%.
Debt yield provides another perspective on credit risk without relying directly on the property's appraised value or the loan's interest rate.
Important: The maximum available loan is often constrained by whichever underwriting requirement produces the lowest permissible loan amount.
Step 3: Identifying the Right Type of Commercial Lender
Commercial mortgage brokers evaluate multiple lender categories rather than assuming one financing source is appropriate for every borrower.
Banks and Credit Unions
Banks and credit unions may be strong candidates for stabilized investment properties and owner-occupied commercial real estate.
They may offer competitive pricing and established banking relationships, but underwriting requirements, recourse provisions, geographic restrictions, and deposit expectations can vary.
Life Insurance Companies
Life insurance lenders often focus on stabilized, income-producing commercial real estate with experienced sponsorship.
Certain programs may offer long-term fixed-rate structures and nonrecourse financing, subject to customary carveouts.
Agency Multifamily Lenders
Fannie Mae and Freddie Mac multifamily programs may be appropriate for eligible apartment properties.
These programs can provide competitive financing structures for qualifying transactions, although eligibility, affordability requirements, property condition, and borrower qualifications matter.
SBA Lenders
SBA 7(a) and 504 programs can help eligible small businesses finance owner-occupied commercial real estate.
These programs are not generally intended for passive real estate investment.
Bridge and Private Lenders
Bridge lenders and private capital sources can be valuable for properties that are not yet suitable for permanent financing.
Examples include properties undergoing renovation, lease-up, repositioning, or other transitional business plans.
However, borrowers must carefully evaluate financing costs, maturity dates, extension options, and exit strategies.
CMBS and Other Capital Markets Lenders
Commercial mortgage-backed securities financing may provide another option for qualifying income-producing properties.
These loans can have distinctive requirements regarding servicing, reserves, cash management, defeasance, and prepayment.
Understanding those provisions before closing is essential.
Step 4: Matching the Financing Strategy to the Property
Consider three different borrowing situations.
Scenario A: Stabilized Apartment Building
An investor is acquiring a 60-unit apartment property with consistent occupancy and predictable operating income.
Potential lender categories could include agency multifamily lenders, banks, and life insurance companies.
The best choice depends on proceeds, interest rate, amortization, recourse, reserves, and the investor's anticipated hold period.
Scenario B: Vacant Retail Property Requiring Renovations
An investor is acquiring a partially vacant retail center and plans to renovate the property, attract tenants, and refinance after stabilization.
A bridge lender may be more appropriate than a permanent lender because the property's current cash flow may not support conventional financing.
The financing should be structured around the renovation budget, lease-up assumptions, carrying costs, and realistic exit strategy.
Scenario C: Business Owner Purchasing an Office Building
A growing professional services company wants to purchase the building it will occupy.
A conventional bank loan or qualifying SBA program may be worth evaluating.
Owner-occupancy, operating business cash flow, eligibility, equity requirements, and loan structure will influence the decision.
These examples demonstrate why identifying the right lender requires more than comparing advertised interest rates.
Step 5: Comparing Commercial Mortgage Loan Offers
Once potential lenders are identified, the next step is comparing the actual financing structures.
At a minimum, borrowers should evaluate five factors:
1.Interest Rate: What is the actual borrowing cost, and is the rate fixed or floating?
2.Loan Proceeds: How much financing is available after applying LTV, DSCR, debt yield, and other constraints?
3.Loan Term: When does the loan mature, and does the amortization extend beyond the maturity date?
4.Recourse: Is the borrower personally liable, or is the loan nonrecourse subject to carveouts?
5.Prepayment: What happens financially if the property is sold or refinanced before maturity?
Borrowers should also compare lender fees, reserves, covenants, closing requirements, and extension options.
A lower interest rate does not necessarily create the lowest total financing cost.
For example, a loan with attractive pricing but expensive yield maintenance or defeasance provisions may be a poor fit for an investor planning an early sale.
Step 6: Preparing the Loan Package
A commercial mortgage broker helps assemble a financing package that allows lenders to evaluate the opportunity efficiently.
Common documentation includes:
·Current rent roll
·Trailing 12-month operating statement
·Historical property financial statements
·Borrower financial statement and liquidity verification
·Sponsor real estate experience
·Purchase contract, when applicable
·Property description and capital improvement budget
·Existing loan information for refinances
·Business financial statements for owner-occupied properties
A well-organized submission helps lenders understand the transaction and can reduce unnecessary underwriting questions.
It does not eliminate due diligence or guarantee approval.
Step 7: Navigating Underwriting and Closing
Identifying a lender is only part of the financing process.
Once a financing proposal is accepted, the transaction typically proceeds through underwriting, appraisal, environmental review, title work, legal documentation, and final credit approval.
A commercial mortgage broker helps coordinate communications, address outstanding conditions, and identify potential issues before they jeopardize the closing timeline.
Experienced financing guidance becomes particularly valuable when unexpected challenges arise.
Examples include a lower-than-expected appraisal, insufficient DSCR, changes in tenant occupancy, or newly identified property repairs.
How the CommLoan Empower Program Helps Borrowers
Through the CommLoan Empower Program, I help commercial real estate investors and business owners evaluate financing alternatives using a marketplace-oriented approach.
CommLoan's CUPID™ platform provides access to a network of 700+ lending sources, creating opportunities to identify financing programs across multiple lender categories.
Rather than starting with one lender's product menu, the process begins with the borrower's transaction and financial objectives.
The goal is to help borrowers:
·Identify lenders that fit their property and financing requirements.
·Understand how lenders evaluate cash flow and risk.
·Compare financing structures beyond the quoted interest rate.
·Prepare stronger loan submissions.
·Make more informed capital decisions.
Access to a broad lender network does not mean every lender will finance every transaction, and all financing remains subject to eligibility, underwriting, and lender approval.
Frequently Asked Questions
Is a commercial mortgage broker better than going directly to a bank?
It depends on the transaction. A bank relationship may be an excellent financing source, but a commercial mortgage broker can help compare alternative lender programs and structures that may not be available through a single institution.
Can commercial mortgage brokers finance properties nationwide?
Many commercial mortgage brokerage platforms work with lenders across the United States. Availability depends on the property's location, lender licensing and geographic requirements, loan size, and asset type.
What credit score is required for a commercial real estate loan?
Requirements vary significantly. Lenders may consider personal credit, sponsor experience, liquidity, net worth, property cash flow, collateral, and guarantor strength.
Can a commercial mortgage broker help with refinancing?
Yes. Brokers can assist with rate-and-term refinancing, qualifying cash-out transactions, maturity refinancing, and financing for repositioned properties.
How are commercial mortgage brokers compensated?
Compensation structures vary. Fees may be paid by borrowers, lenders, or through other disclosed arrangements, depending on the program and applicable requirements. Borrowers should request a clear explanation of all compensation and financing costs.
Final Thoughts: The Right Lender Can Change the Outcome
Successful commercial real estate financing begins with understanding the deal.
A property may be attractive, but the wrong financing structure can create unnecessary risk, restrict future options, or undermine an investment strategy.
The right commercial mortgage broker helps evaluate the property, understand the borrower's objectives, identify suitable lending sources, and compare loan structures before important decisions are made.
The objective isn't simply to get a loan. It's to secure financing that supports the investment strategy.
Let's Discuss Your Commercial Real Estate Financing
I'm Bill Rapp, CCIM, with the CommLoan Empower Program.
Whether you're acquiring, refinancing, developing, or repositioning commercial real estate, let's evaluate the transaction and explore available financing options.
Website: https://billrapp.commloan.com/
Schedule a Consultation: https://calendly.com/vikingenterprise
Top of Form
Bottom of Form
Bill Rapp, CCIM
Director | CommLoan
📞 281-222-0433
📧 [email protected]
🌐 https://billrapp.commloan.com/
🌐 https://HoustonCommercialMortgage.com/
Commercial Real Estate Financing Nationwide
https://billrapp.commloan.com/
https://author.billrapponline.com/
https://www.amazon.com/dp/B0F32Z5BH2
https://veed.cello.so/FOmzTty6oi9
https://buymeacoffee.com/vikingente3
https://creplaybookseries.billrapponline.com
https://creplaybook.billrapponline.com/
©Bill Rapp, CCIM - Director - CommLoan
10 Tips for First-Time Homebuyers
Buying your first home can be both exciting and nerve-wracking at the same time. With so many things to consider and....
How To Choose the Right Lender for You
Lorem Ipsum is simply dummy text of the printing and typesetting industry. Lorem Ipsum has been the industry's standard dummy
Refinancing youe loan and when to do it
Lorem Ipsum is simply dummy text of the printing and typesetting industry. Lorem Ipsum has been the industry's standard dummy
🧮 Renovation ROI Calculator
🛠️ Renovation ROI Calculator 💰
Copyright ©2021 | Mortgage Viking Team
Licensed to Do Business | NMLS # 228246
This is not an offer to enter into an agreement. Not all customers will qualify. Information, rates and programs are subject to change without notice. All products are subject to credit and property approval. Other restrictions and limitations may apply. Copyright © 2021 | Medallion Funds
Corporate | NMLS ID NMLS # 1825831
Corporate Address : 2651 N. Green Valley Pkwy STE. 101 Henderson, NV 89014
Corporate NMLS NMLS # 1825831 | Company Website: https://medallionfunds.com/bill-rapp/
Copyright ©2021 | Mortgage Viking Team Licensed to Do Business | NMLS # 228246
This is not an offer to enter into an agreement. Not all customers will qualify. Information, rates and programs are subject to change without notice. All products are subject to credit and property approval. Other restrictions and limitations may apply
Corporate | NMLS ID NMLS # 1825831
Corporate Address : 2651 N. Green Valley Pkwy STE. 101 Henderson, NV 89014 https://medallionfunds.com/bill-rapp/