
The Top 5 Mortgage Mistakes to Avoid
Buying a home can be an exciting and rewarding experience, but it can also be a daunting and overwhelming process, especially for first-time homebuyers.
.
Mortgages are a significant financial commitment, and making mistakes during the process can have serious consequences. In this blog post, we'll explore the top 5 mortgage mistakes to avoid.
1. Failing to Check and Improve Your
Credit Score
Your credit score plays a significant role in determining your eligibility for a mortgage and the interest rate you'll receive. Many first-time homebuyers make the mistake of failing to check their credit score or not taking steps to improve it before applying for a mortgage.
,
To avoid this mistake, check your credit score and take steps to improve it if necessary. This may include paying off outstanding debts, making on-time payments, and disputing any errors on your credit report. A higher credit score can lead to a lower interest rate and a more favorable mortgage offer.
2. Ignoring
Closing Costs
Another common mistake is ignoring closing costs. Many first-time homebuyers are unaware of the various fees associated with closing a mortgage, such as attorney fees, title search fees, and appraisal fees. These costs can add up quickly and significantly impact the total cost of the mortgage.
.
To avoid this mistake, research the average closing costs in your area and budget accordingly. Be sure to factor in these costs when considering the overall cost of the home.
2. Ignoring Closing Costs
Another common mistake is ignoring closing costs. Many first-time homebuyers are unaware of the various fees associated with closing a mortgage, such as attorney fees, title search fees, and appraisal fees. These costs can add up quickly and significantly impact the total cost of the mortgage.
.
To avoid this mistake, research the average closing costs in your area and budget accordingly. Be sure to factor in these costs when considering the overall cost of the home.

3. Not Getting Pre-Approved
Getting pre-approved for a mortgage is an essential step in the home buying process. Pre-approval gives you a clear idea of how much you can afford to spend on a home and helps you avoid the disappointment of falling in love with a home you can't afford.
.
To avoid this mistake, get pre-approved for a mortgage before you start shopping for a home. This will help you narrow down your search to homes that are within your budget and prevent you from wasting time on homes that are out of reach.
4. Taking on Too Much Debt
Taking on too much debt before or during the mortgage process can have serious consequences. Lenders look at your debt-to-income ratio when determining your eligibility for a mortgage. If you have too much debt, you may not qualify for a mortgage or may be offered a higher interest rate.
.
To avoid this mistake, avoid taking on new debt before or during the mortgage process. This includes opening new credit cards, taking out a car loan, or making large purchases on existing credit cards.
4. Taking on Too
Much Debt
Taking on too much debt before or during the mortgage process can have serious consequences. Lenders look at your debt-to-income ratio when determining your eligibility for a mortgage. If you have too much debt, you may not qualify for a mortgage or may be offered a higher interest rate.
.
To avoid this mistake, avoid taking on new debt before or during the mortgage process. This includes opening new credit cards, taking out a car loan, or making large purchases on existing credit cards.
5. Choosing the Wrong Mortgage
Choosing the wrong mortgage can be a costly mistake. There are various types of mortgages available, and each has its pros and cons. Choosing the wrong mortgage can lead to higher interest rates, higher monthly payments, and a more significant financial burden in the long run.
.
To avoid this mistake, research the different types of mortgages available and choose the one that best fits your financial situation and goals. Don't be afraid to ask your lender questions and seek advice from a financial advisor.
Blogs
The Top 5 Mortgage Mistakes to Avoid
Buying your first home can be both exciting and nerve-wracking at the same time. With so many things to consider and....
Mortgage Do and
Do not list
Mortgages can be tricky, and it's easy to make mistakes that can end up costing you dearly. That's why we've put together this list....
Tips On How To Improve Your Credit Score
Let's talk about some ways you can improve your credit score! Your credit score is actually a big deal, and it can affect...
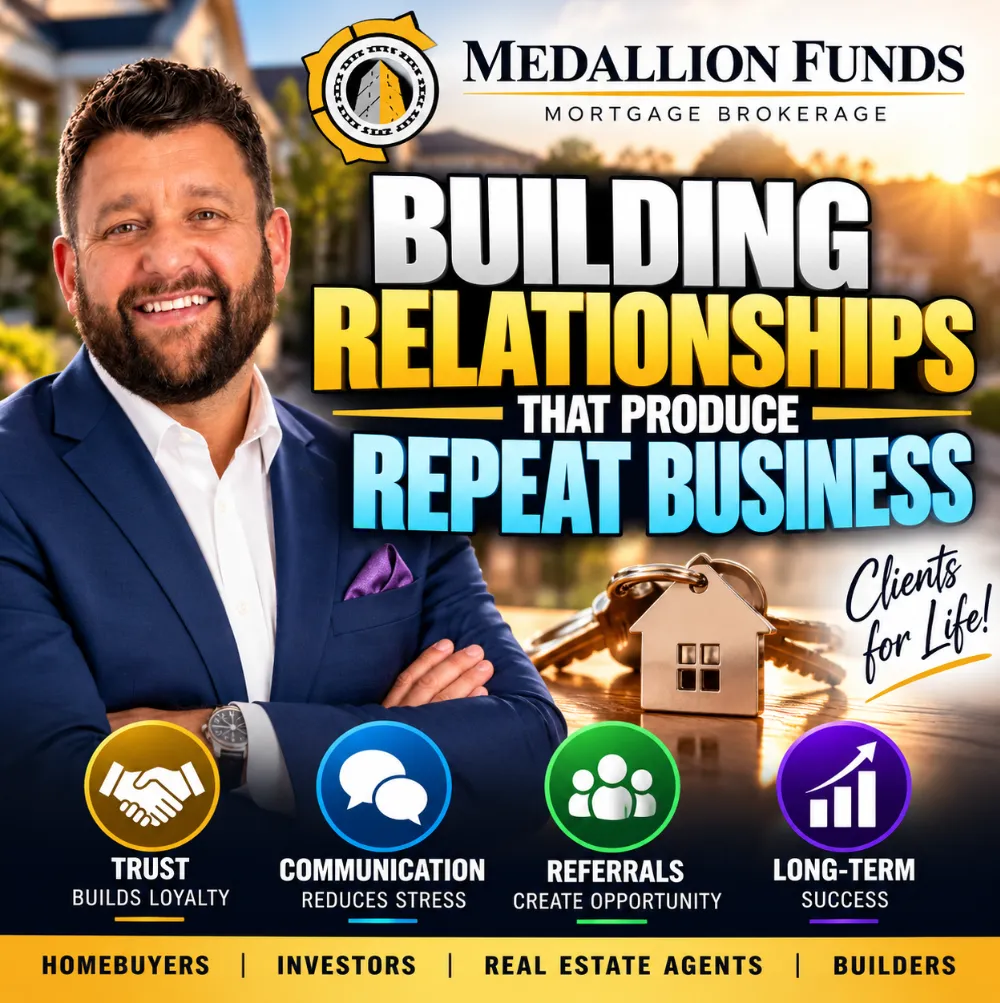
🏠 Building Relationships That Produce Repeat Business: Why the Best Mortgage Experience Goes Beyond the Closing 🤝
🏠 Building Relationships That Produce Repeat Business: Why the Best Mortgage Experience Goes Beyond the Closing 🤝
🤝 From Mortgage Client to Client for Life: How Trust Creates Repeat Business & Referrals 🏡
________________________________________________________________________________
Building Relationships That Produce Repeat Business
In the mortgage business, closing the loan should not be the end of the relationship. In many ways, it should be the beginning.
A homebuyer may need a mortgage today, but their financial and real estate needs can change significantly over the next several years. They may refinance, move into a larger home, purchase an investment property, buy a second home, access home equity, or need financing for a family member.
That is why I believe a successful mortgage brokerage relationship should be built around more than simply completing a transaction.
At Medallion Funds, the objective is to become a long-term mortgage resource clients can call before, during, and long after closing.
A Mortgage Is a Transaction. A Client Relationship Is Long Term.
Many borrowers approach the mortgage process thinking primarily about one question:
“Can I get approved?”
That is obviously important, but a good mortgage strategy should consider more than today's approval.
Questions worth discussing can include:
·How much house comfortably fits the borrower's budget?
·Should the borrower put more money down or preserve liquidity?
·Does paying discount points make sense?
·Could the borrower benefit from refinancing later?
·How might future real estate goals affect today's financing decision?
·Is there another mortgage structure that better supports the borrower's objectives?
The goal isn't simply to find a loan. It is to help the borrower understand the available financing options and make an informed decision.
Trust Is Built Through Communication
Mortgage transactions involve dozens of moving pieces: income documentation, assets, credit, appraisal, insurance, title, underwriting conditions and closing requirements.
When communication breaks down, the mortgage process can become unnecessarily stressful.
That is why consistent communication is one of the foundations of a strong mortgage-client relationship.
Borrowers should understand what is happening, what is needed from them and what comes next.
Sometimes that also means delivering information a borrower wasn't hoping to hear. A trusted mortgage advisor should be willing to explain the numbers, identify potential problems and discuss alternatives rather than simply telling someone what they want to hear.
Great Service Creates Mortgage Referrals
Most people know someone who will eventually need mortgage financing.
It might be a friend buying a first home, a coworker relocating, a family member purchasing an investment property, or a business owner whose income doesn't fit neatly into a conventional lending box.
When someone has had a positive mortgage experience, they are more likely to remember the person who helped them when one of those conversations comes up.
That is how relationships naturally create mortgage referrals and repeat business.
The objective shouldn't be to constantly ask clients for referrals. It should be to provide enough value that clients feel comfortable making the introduction.
Stay Useful After the Closing
One of the biggest mistakes mortgage professionals can make is disappearing after the closing documents are signed.
Homeownership continues after closing—and so should the relationship.
There are plenty of reasons for homeowners to stay connected with a mortgage professional. Mortgage rates change. Property values change. Household income changes. Families grow. Investment opportunities emerge.
A past client might eventually have questions about:
Mortgage refinancing. Would replacing the existing mortgage improve the homeowner's financial position after considering closing costs?
Home equity. Could available equity help accomplish another financial objective?
Investment property financing. Is it time to purchase a rental property?
Moving or upgrading. How would the existing home, equity and mortgage affect the next purchase?
Non-traditional financing. Could a bank statement, DSCR, jumbo, doctor or other mortgage program fit a future situation?
The best time to establish a trusted financing relationship is before one of these decisions becomes urgent.
Relationships Also Matter With Real Estate Professionals
Strong mortgage relationships extend beyond borrowers.
Real estate agents, builders, CPAs, financial advisors, attorneys and other professionals frequently encounter clients with financing questions.
A mortgage broker who communicates effectively and solves problems can become a valuable resource for those professionals.
The relationship works both ways.
When a real estate agent refers a buyer, that agent is placing part of their own reputation in the mortgage professional's hands. Communication, realistic expectations and reliable execution therefore matter far beyond a single transaction.
Why a Mortgage Broker Can Add Value to the Relationship
A mortgage broker can evaluate financing across multiple lending options rather than approaching every borrower through a single lending institution's product menu.
That can be particularly useful when borrowers have more complex circumstances involving self-employment, investment properties, jumbo financing, unique income structures or other non-standard situations.
It doesn't mean every borrower will qualify for every program or that a broker will always have the lowest-cost option.
It means borrowers can have someone helping them evaluate available structures and determine which options align with their situation.
The Goal: Become the First Call
For me, one of the strongest indicators of a successful mortgage relationship isn't simply getting someone to closing.
It's receiving a call years later that starts with:
“Bill, I'm thinking about buying another property. Can we run some numbers?”
That means the relationship survived the transaction.
At Medallion Funds, my objective is to help clients understand their mortgage options today while remaining a resource for whatever comes next.
Because mortgages eventually get paid off.
Relationships can last much longer.
Bill Rapp
Partner & Director of Capital Advisory | Medallion Funds
Commercial Lending Nationwide
Residential Lending in AL, CA, CO, NV & TXBottom of Form
https://www.billrapponline.com/
https://findamortgagebroker.com/Profile/WilliamRappJr28883
https://billrapp.commloan.com/
https://billrapponline.com/financingfuturescre-houston-katy
https://houstoncommercialmortgage.com/
https://author.billrapponline.com
https://doctorvideo.billrapponline.com/
https://veteransvideo.billrapponline.com/
https://mortgageviking.billrapponline.com/
https://fha203h.billrapponline.com/
https://renovationvideo.billrapponline.com
https://medallionfunds.com/bill-rapp/
https://www.amazon.com/dp/B0F32Z5BH2
https://veed.cello.so/FOmzTty6oi9
https://buymeacoffee.com/vikingente3
https://creplaybookseries.billrapponline.com
https://creplaybook.billrapponline.com/
© Bill Rapp, Medallion Funds LLC, Director of Capital Advisory
10 Tips for First-Time Homebuyers
Buying your first home can be both exciting and nerve-wracking at the same time. With so many things to consider and....
How To Choose the Right Lender for You
Lorem Ipsum is simply dummy text of the printing and typesetting industry. Lorem Ipsum has been the industry's standard dummy
Refinancing youe loan and when to do it
Lorem Ipsum is simply dummy text of the printing and typesetting industry. Lorem Ipsum has been the industry's standard dummy
🧮 Renovation ROI Calculator
🛠️ Renovation ROI Calculator 💰
Copyright ©2021 | Mortgage Viking Team
Licensed to Do Business | NMLS # 228246
This is not an offer to enter into an agreement. Not all customers will qualify. Information, rates and programs are subject to change without notice. All products are subject to credit and property approval. Other restrictions and limitations may apply. Copyright © 2021 | Medallion Funds
Corporate | NMLS ID NMLS # 1825831
Corporate Address : 2651 N. Green Valley Pkwy STE. 101 Henderson, NV 89014
Corporate NMLS NMLS # 1825831 | Company Website: https://medallionfunds.com/bill-rapp/
Copyright ©2021 | Mortgage Viking Team Licensed to Do Business | NMLS # 228246
This is not an offer to enter into an agreement. Not all customers will qualify. Information, rates and programs are subject to change without notice. All products are subject to credit and property approval. Other restrictions and limitations may apply
Corporate | NMLS ID NMLS # 1825831
Corporate Address : 2651 N. Green Valley Pkwy STE. 101 Henderson, NV 89014 https://medallionfunds.com/bill-rapp/